
NEXTAGE Stock And 2 Other Japanese Undervalued Stocks
Global bond yields have climbed sharply, and Japan's 10 year government bond yield recently reached its highest level since 1996. When borrowing costs reset like this, money often moves away from companies with weaker balance sheets and toward businesses that already produce solid cash and carry limited debt. In this environment, high quality Japanese companies that still appear inexpensive may attract more attention. This article highlights 3 such undervalued stocks from our screener.
The three stocks below are just a sample, and the full screen surfaced 14 more high quality Japanese companies with equally compelling stories that are not covered here. If you want to move quickly from ideas to a focused watchlist, head straight into the High Quality Undervalued Stocks screener to identify, analyze, and zero in on your highest conviction opportunities.
NEXTAGE (TSE:3186)
Overview: NEXTAGE runs a large car retail network in Japan, trading new and used vehicles and providing related maintenance, inspection, and coating services.
Operations: NEXTAGE generates ¥734.3b in revenue from automobile sales and associated services, all sourced from customers within Japan.
Market Cap: ¥228.5b
NEXTAGE aligns closely with the High Quality Undervalued Stocks theme because vehicle trading and related services generate sizeable cash flows backed by updated profit guidance and higher earnings for 2026. That combination of income strength and a discounted valuation can appeal to investors who care about balance-sheet resilience if there is a shift in funding costs or debt service.
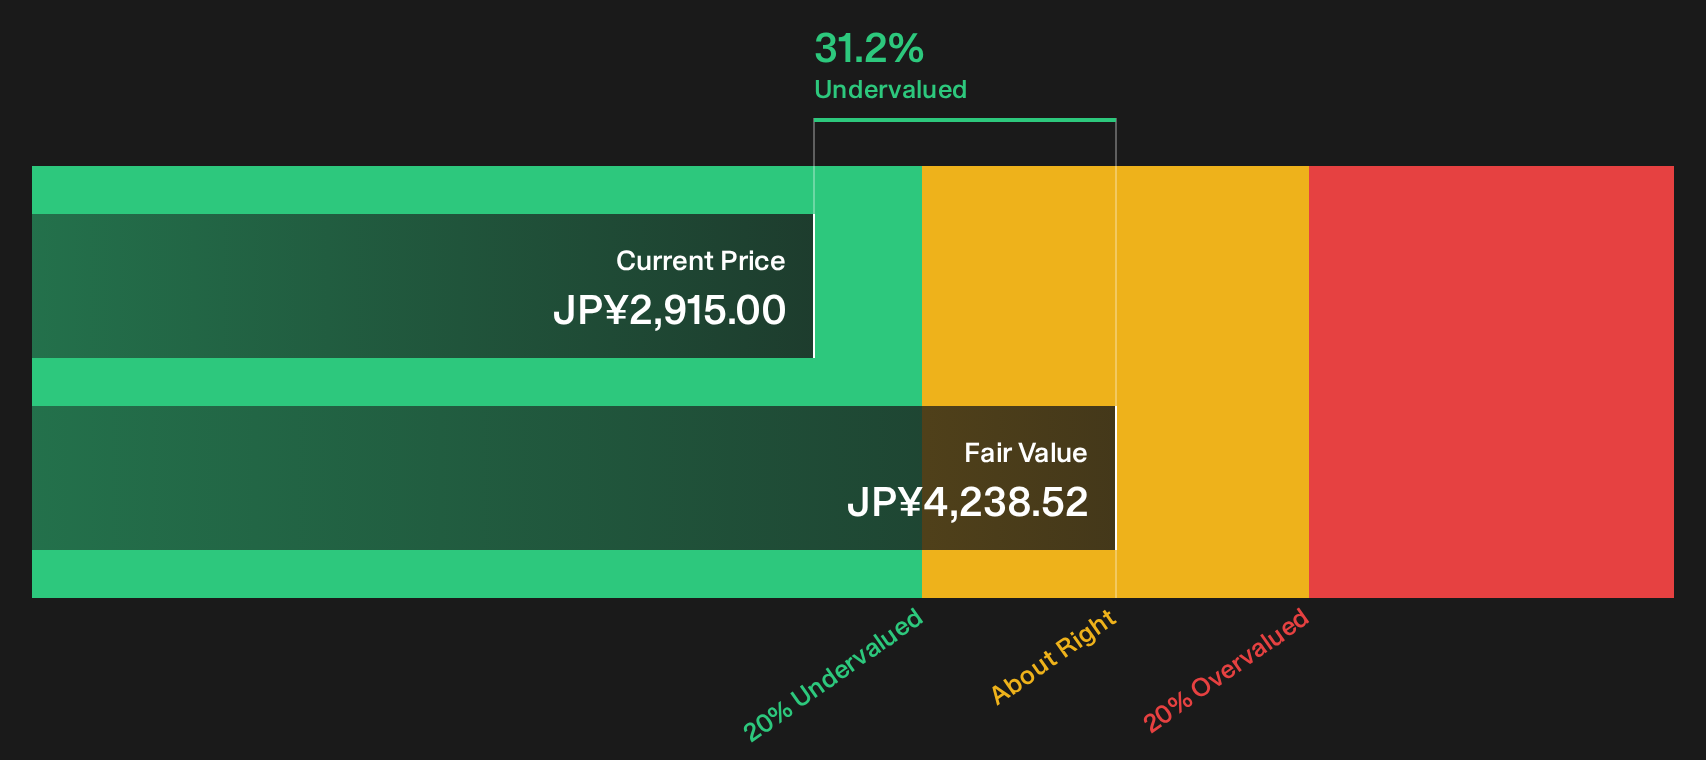
That kind of cash and balance sheet focus makes it worth lining NEXTAGE up against peers using the DCF valuation analysis for NEXTAGE to see what the market might be missing.
Rakus (TSE:3923)
Overview: Rakus runs a Japan based cloud software and IT staffing operation, with its recurring SaaS tools anchoring the high quality undervalued thesis.
Operations: Rakus generates ¥60.4b in revenue from customers in Japan, combining cloud subscriptions with IT engineering and infrastructure services.
Market Cap: ¥380.0b
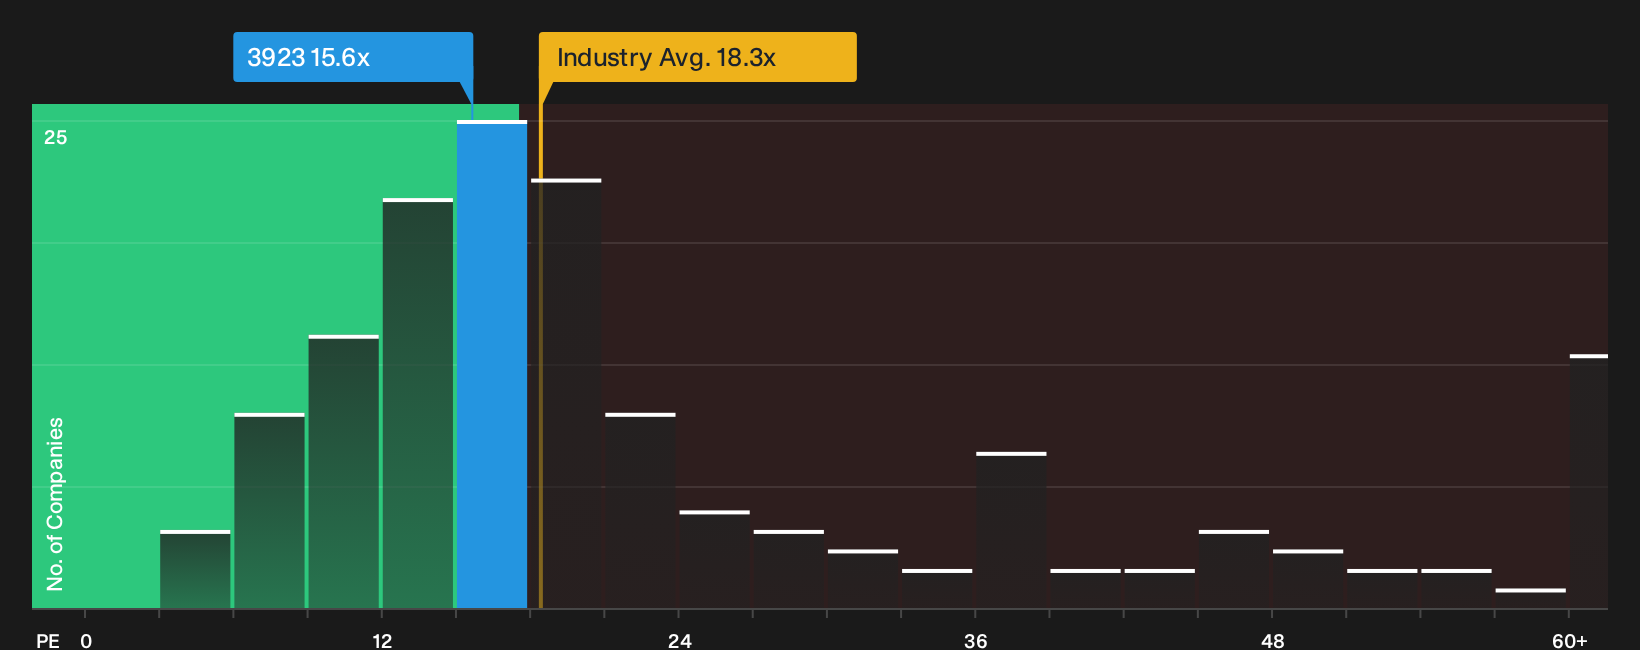
Rakus brings together recurring cloud subscriptions, value oriented metrics and a P/E that screens attractively against peers. The Cloud Business supplies predictable software fees that support balance sheet strength, while IT human resource services add scale. Investor interest now rests on how a single pressure point around funding and capital allocation shapes future returns on that expanding SaaS base.
That funding question is exactly why the analysis report for Rakus could be useful for identifying when Rakus returns may be diverging from its SaaS fundamentals.
BuySell TechnologiesLtd (TSE:7685)
Overview: BuySell TechnologiesLtd runs a reuse business in Japan, buying and reselling kimonos and other branded pre-owned goods across multiple channels.
Operations: BuySell TechnologiesLtd generates ¥124,962 million in revenue from its reuse business for kimonos and branded products, all within Japan.
Market Cap: ¥188.9b
BuySell TechnologiesLtd fits this screener because its reuse franchise and recycling platform generate recurring cash flows from kimonos and branded goods, supported by margin expansion and rising guidance that indicate a healthier balance sheet. Investors watching for a potentially undervalued story may pay attention to how changes in funding conditions influence those underlying economics.
As that funding backdrop shifts for BuySell TechnologiesLtd, the analysis report for BuySell TechnologiesLtd helps you see where the reuse story might be decoupling from expectations.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first, and late money often gets caught chasing momentum as breakouts fade and prices drop back. Scan under the radar for now, then act with a clear plan.
- Track income ideas that aim to keep paying while others are cutting by reviewing the 15 dividend fortresses curated from balance sheets built around steady cash generation.
- Spot companies involved in the backbone of AI infrastructure before attention increases by scanning the 85 AI infrastructure stocks and focusing on businesses supplying the picks and shovels of this build out.
- Position for potential electrification spending by checking the 39 power grid technology and infrastructure stocks and filtering for firms tied to upgrades in transmission, software, and grid stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com