
Will Pipeline Sale Change TC Energy Stock Narrative
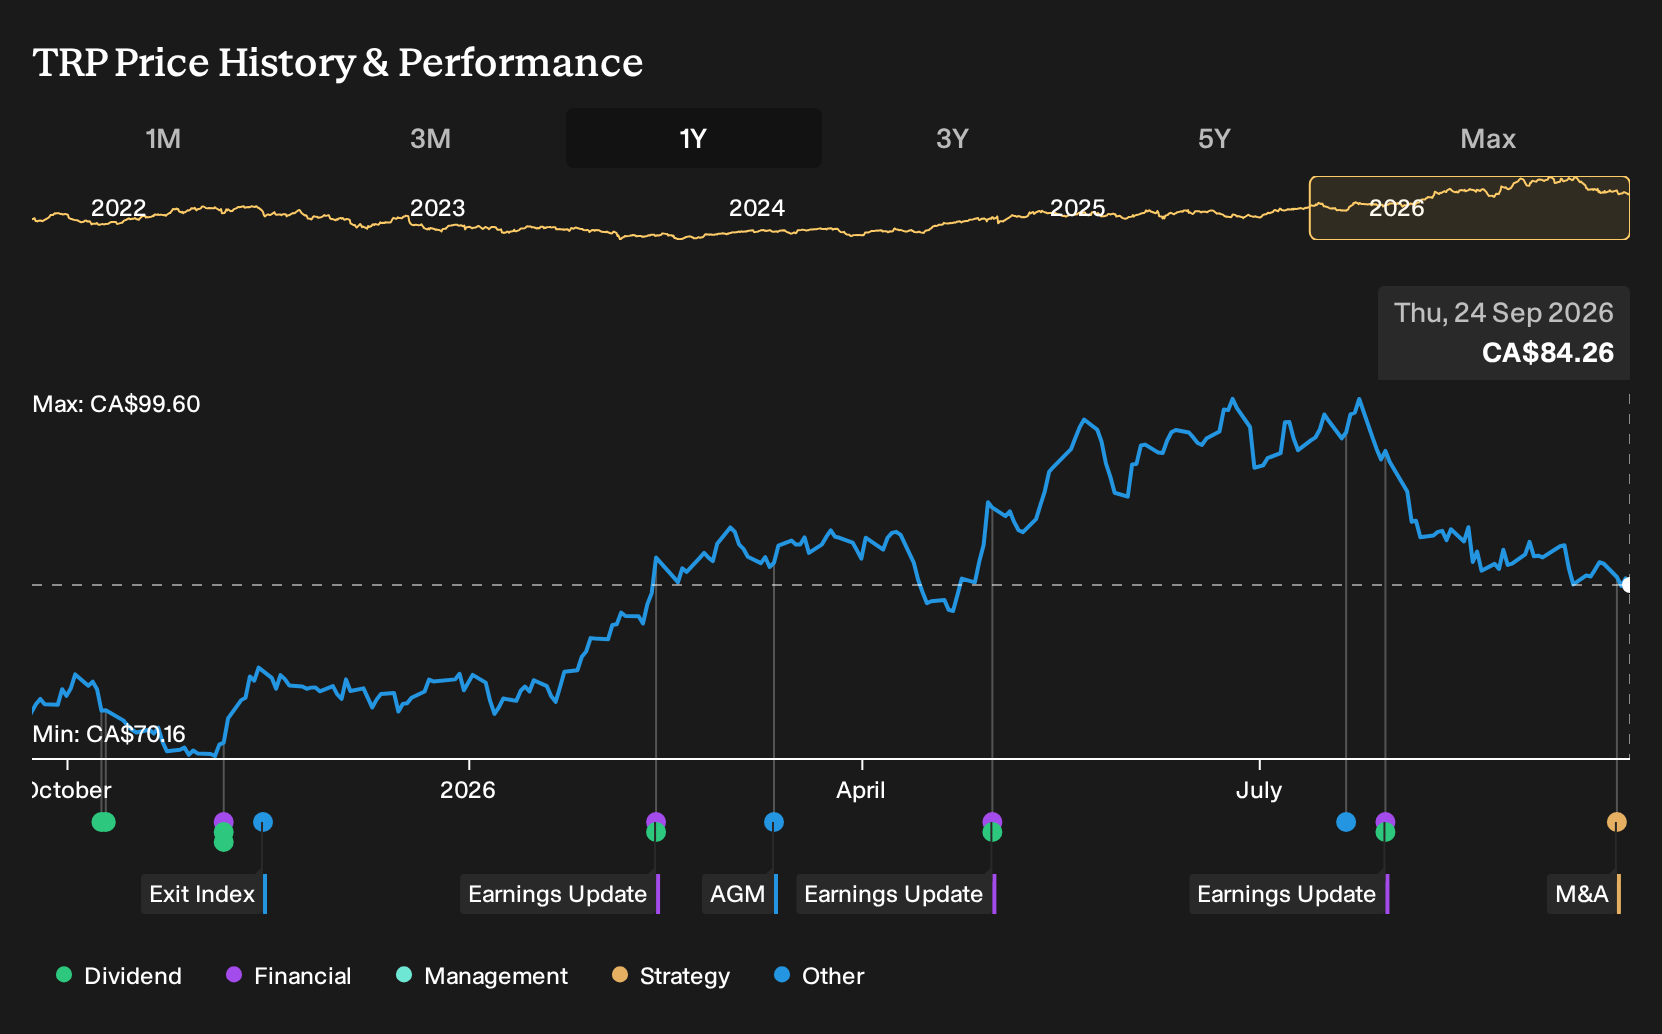
- TC Energy agreed to sell its Guadalajara-Manzanillo natural gas pipeline in Mexico to Esentia Energy Development for US$560 million, with closing targeted in the first half of 2027 subject to regulatory and other approvals.
- The disposal fits TC Energy's portfolio optimization plan, redirecting capital away from a single Mexican pipeline and toward higher-return gas infrastructure projects that are tied to long-term contracts and systemwide demand drivers.
- Investors will now be watching how this Mexican pipeline sale could influence TC Energy's broader investment narrative, including capital allocation priorities and the balance of risk across its asset base.
Look beyond TC Energy and evaluate other gas and infrastructure plays that follow this same capital allocation story with our hand picked 39 power grid technology and infrastructure stocks
TC Energy Investment Narrative Recap
To own TC Energy, you need to buy into a story where long-haul natural gas pipelines and power assets generate steady cash flows tied to contracts and regulated returns. The Guadalajara Manzanillo sale aligns with that approach by recycling capital from a single Mexican asset into projects that are intended to rely on systemwide demand, not one route.
The near-term swing factor remains execution on its gas growth projects and how cleanly those translate into earnings and cash coverage, especially with a 4.14% dividend yield flagged as not well covered. The biggest current risk is the balance sheet. Interest costs are already a pressure point, so any delay or cost increases on new builds would be significant.
The Guadalajara Manzanillo pipeline deal is the key announcement that connects most directly to those catalysts. TC Energy plans to receive US$560 million, subject to approvals and a closing targeted in the first half of 2027. That provides management with a defined source of capital for planned gas and power projects across its North American footprint.
For investors, the question is how effectively that future cash is redeployed. The firm has a large network and a history of brownfield expansions, yet it also carries leverage where interest payments are not well covered. The sale sits at the center of that trade-off between capital recycling and financial risk.
TC Energy's narrative projects CA$18.2b revenue and CA$5.3b earnings by 2029. This assumes 5.2% yearly revenue growth and an earnings increase of about CA$1.6b from CA$3.7b today.
Uncover why TC Energy's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only shows two fair value estimates for TC Energy, stretched between about CA$33.85 and CA$98.78 per share. That gap signals how far apart retail views can be. Before the pipeline sale fully feeds into models, weigh those upbeat gas demand assumptions against the risk of slower long term fossil fuel use and potential pressure on future contracts and financing costs.
Explore another TC Energy fair value estimate, including one that suggests as much as 17% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TC Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TC Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TC Energy's overall financial health at a glance.
Looking for more TC Energy style investment ideas?
If the TC Energy story has you thinking about how to balance income, balance sheet strength, and valuation, the Simply Wall St Screener can help you widen the field without losing that focus on fundamentals.
- If you want potential upside with a margin of safety, start with a curated set of 5 high quality undervalued stocks that pair quality fundamentals with pricing that may not fully reflect them yet.
- If capital preservation matters most to you, filter for resilience by running through the 8 resilient stocks with low risk scores that emphasize stronger financial profiles and lower risk scores.
- If you care about balance sheets as much as cash generation, scan the list of solid balance sheet and fundamentals (7 results) to find businesses where debt and liquidity look more manageable on the numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com