
Dividend Raise Might Change The Case For Investing In W. P. Carey Stock (WPC)
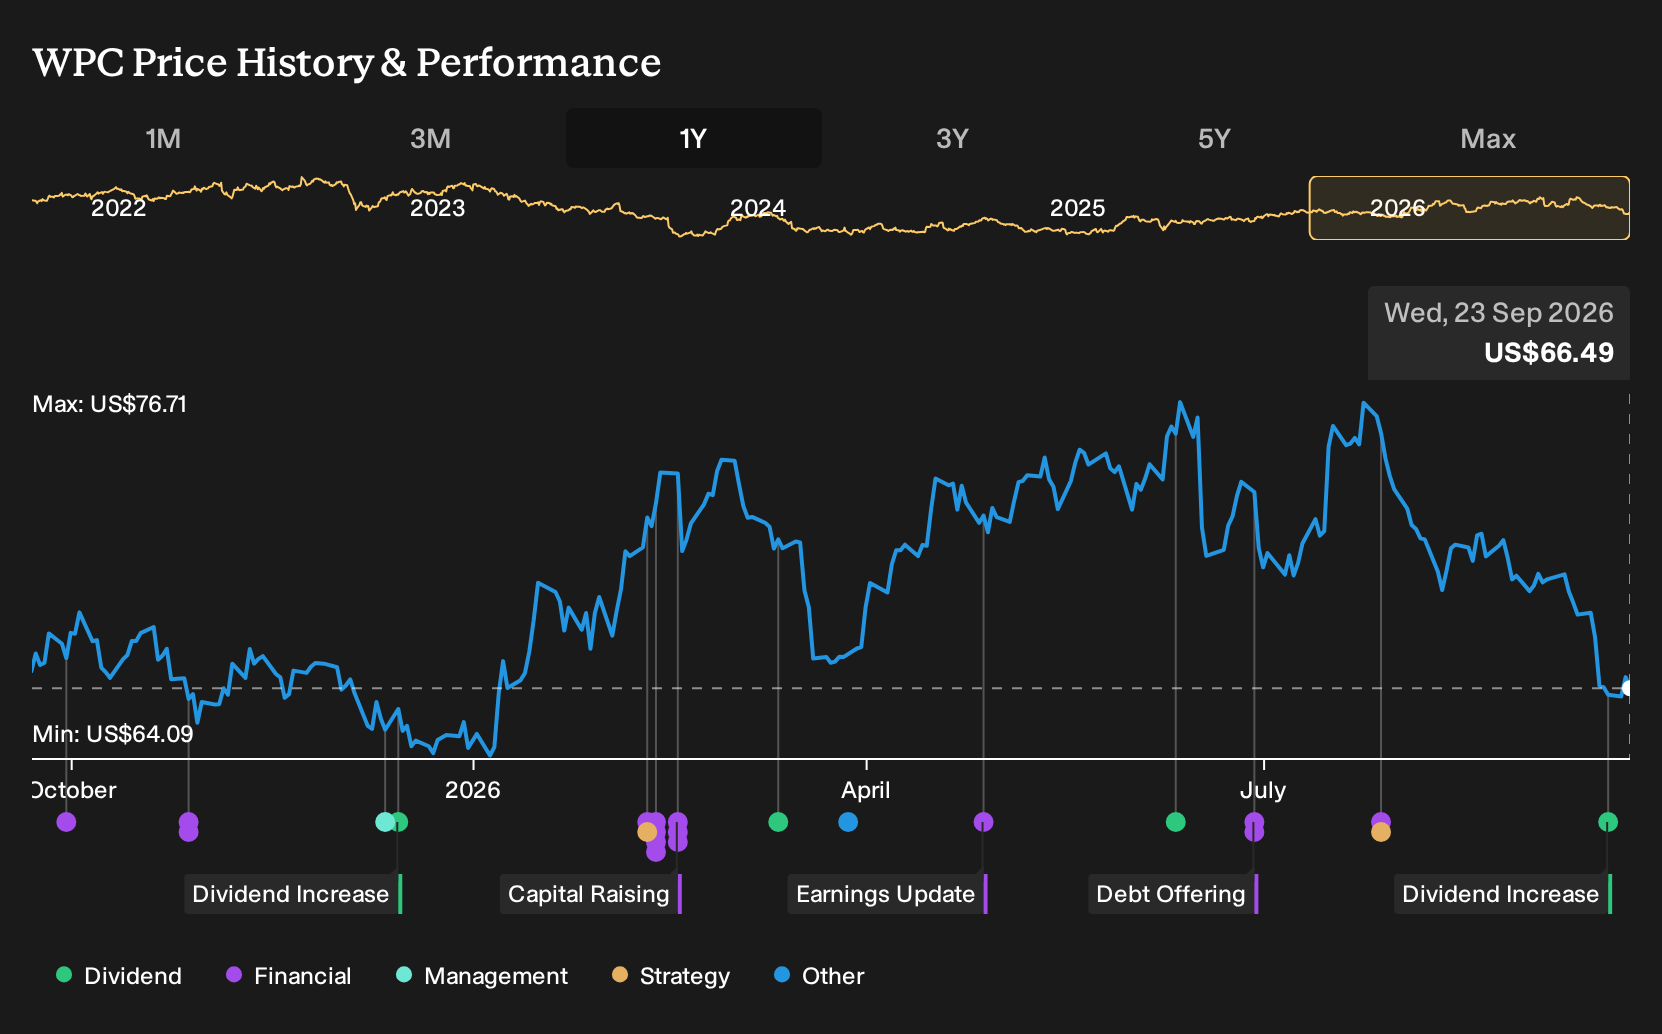
- W. P. Carey increased its quarterly cash dividend to $0.950 per share, or $3.80 on an annualized basis, payable on October 15, 2026 to investors of record as of September 30, 2026.
- The higher payout indicates that W. P. Carey’s board views its current rent base and cash flows as sufficient to support a larger recurring distribution.
- We will now explore how W. P. Carey's higher quarterly dividend could influence the investment narrative around its net lease strategy.
Scan beyond W. P. Carey’s higher payout and explore additional income ideas with our curated 7 dividend fortresses built for investors who care about durability as much as yield.
W. P. Carey Investment Narrative Recap
To hold W. P. Carey, you need to be comfortable with a large, long lease net lease portfolio that leans on inflation linked rent bumps and steady deal flow in industrial, warehouse and retail properties. The higher quarterly dividend signals confidence in current cash generation, but it does not change the near term focus on sourcing accretive sale leasebacks and keeping occupancy around current high levels.The biggest swing factor remains tenant credit concentration. Any cluster of weaker single tenant outcomes could hit rent and challenge dividend cover. Balance sheet funding is another watchpoint, since debt is not well covered by operating cash flow. The dividend increase does not remove those risks, although it may sharpen attention on payout sustainability.
The dividend move sits alongside an investment plan built on high volume net lease deployment. Management flagged year to date 2026 investing of US$1.3b at a 7.4% initial cash cap rate, with full year deployment guidance of US$1.7b to US$2.1b. For you as a shareholder, the question is whether W. P. Carey can keep finding properties that support both AFFO and the higher dividend.
Pre funded capacity matters here. Around US$1.5b of recent bond issuance, roughly US$900m of forward equity and total liquidity near US$2.7b to US$2.8b give W. P. Carey room to continue that acquisition program without a sudden jump in interest expense. That same funding mix, combined with an already higher payout, also raises the bar on execution, since weaker tenant credit or a less friendly capital market would pressure margins and financial flexibility at the same time.
W. P. Carey’s analyst playbook currently rests on revenue reaching about US$2.2b and earnings landing near US$808.3m by 2029. This aligns with a 7.3% yearly revenue growth assumption and an earnings increase of roughly US$157m from the current US$651.0m base.
Uncover why W. P. Carey's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$79.6 to US$170.1 per share, so retail opinions on W. P. Carey already stretch across more than a twofold range. When you set that against tenant credit concentration risk and capital market dependence, you can see why views diverge sharply and why exploring multiple perspectives matters.
Explore 3 other W. P. Carey fair value estimates, including one that suggests a potential increase of up to 158% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your W. P. Carey research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for W. P. Carey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate W. P. Carey's overall financial health at a glance.
Looking For More Ideas Beyond W. P. Carey?
If W. P. Carey has helped sharpen your thinking around income, risk and valuation, it can be useful to line that view up against a wider set of companies that match your priorities on balance sheet strength, dividends or potential mispricing.
- If you want sturdier finances to sit behind your income, consider reviewing a list of solid balance sheet and fundamentals (23 results) that filters for healthier leverage and liquidity profiles.
- For investors hunting for mispriced quality, scan through a focused group of 30 high quality undervalued stocks that pair stronger fundamentals with potentially more attractive entry points.
- If you prefer to cast a wider net for future opportunities, broaden your watchlist with a curated set of 16 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com