
DoorDash (DASH) Agrees $131.5 Million Settlement Over New York Courier Pay
- DoorDash (NasdaqGS:DASH) agreed to a US$131.5 million settlement to resolve New York City delivery worker pay allegations.
- The deal covers more than 260,000 couriers who alleged underpayment and late payment for work completed in the city.
- The company acknowledged technical and compliance failures around worker compensation practices and committed to correcting these issues going forward.
- The US$131.5 million DoorDash settlement over New York City courier pay is important, but investors may want to consider a broader set of factors. Our analysis turns up 4 other big wins for DoorDash as well.
For readers comparing DoorDash with other opportunities in this corner of the market, the next stop is 30 high quality undervalued stocks.
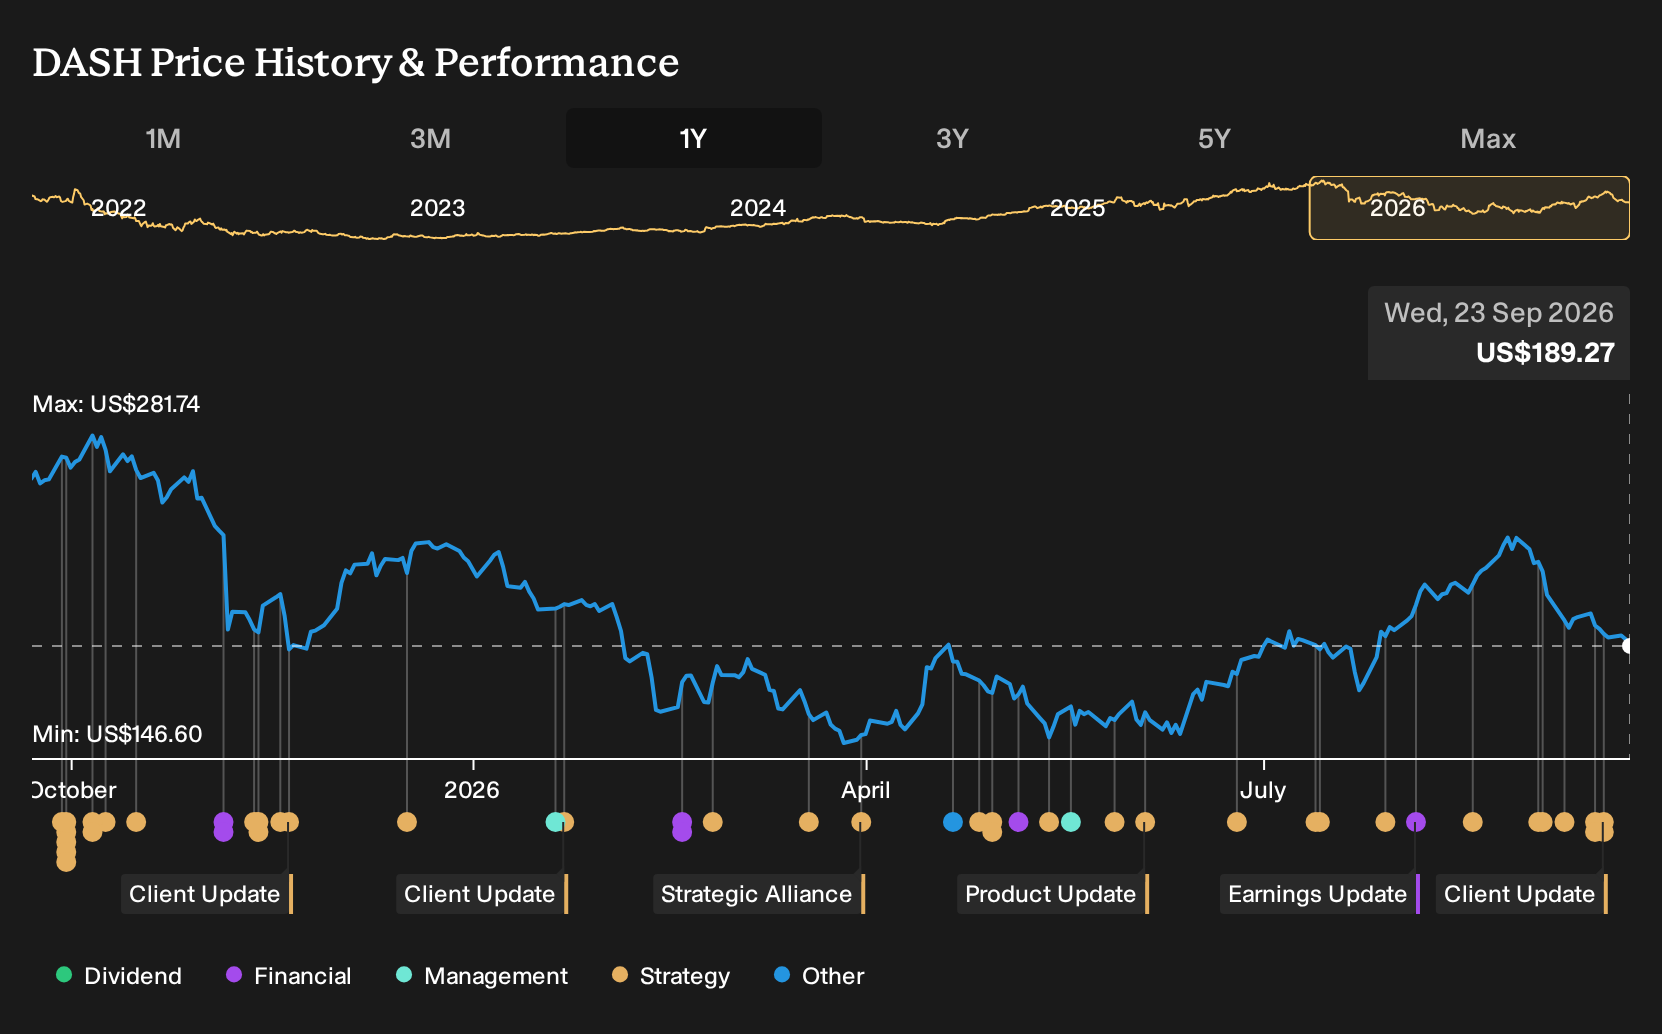
DoorDash runs a large-scale food and commerce platform that links restaurants, retailers, customers, and more than 260,000 couriers, so any shift in how it handles worker pay touches a core part of its operating model. For readers, this settlement sits squarely at the intersection of labor practices, compliance costs, and the reliability of the service itself.
See how DoorDash's balance sheet measures up.
DoorDash settlement tests the "regulatory pressure" side of its growth story
The Narrative on DoorDash is built around expanding local commerce and squeezing more efficiency out of each order. This depends heavily on a large, flexible gig workforce. A US$131.5 million payout over worker compensation in New York City pushes directly on how sustainable that model looks as regulation tightens.
"Rising labor costs, seasonally variable Dasher expenses, and potential regulatory pressures surrounding gig economy work present persistent risks to fulfillment cost structure, which could erode DoorDash's net margins and challenge long-term profitability..."
See how the full story points towards a $254 fair value for DoorDash.
This settlement confirms that the regulatory risk in DoorDash's Narrative is not theoretical, because past pay practices have already resulted in a nine figure cost. It also suggests compliance systems were not keeping pace with product and geographic expansion, which matters when rivals like Uber and Grubhub face similar legal scrutiny.
On the other side, resolving years of disputes in one package helps clear a known overhang and gives management a chance to reset pay logic, data tracking, and controls. The impact on long-term earnings power depends on whether tighter worker protections settle into a stable cost base or keep triggering fresh claims in other regions.
For readers, interpreting headlines like this really comes down to whether DoorDash can grow local commerce faster than regulatory and labor costs eat into the economics. That is exactly what a clear Narrative forces you to judge.
The DoorDash detail most holders skip is hiding in the long range forecasts
Most people stop at the headline story, yet the real curveball for DoorDash sits in where professional forecasters think this operation could land a few years from now. See where analysts expect DoorDash to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com