
Does Earnings Upgrade Change The Bull Case For Bridgestone Stock (TSE:5108)?
- Bridgestone recently saw its consensus full year earnings estimate move 6.9% higher over the past quarter, pointing to a more optimistic profit outlook from analysts.
- The upward shift in projected earnings draws greater attention to how Bridgestone’s cost actions, product mix and regional restructuring efforts are affecting underlying profitability.
- We will now explore how Bridgestone's upgraded earnings outlook could influence its investment narrative for long term oriented investors.
Scan for other auto and industrial stocks where analysts are upgrading profit expectations and cost levers are starting to bite, starting with our curated 17 high quality undervalued stocks.
Bridgestone Investment Narrative Recap
To own Bridgestone, you need to be comfortable with a tire group leaning hard into premium and specialty products while restructuring underperforming regions. The recent earnings upgrade points to cost work and product mix shifts gaining some traction. The key near term swing factor is whether those savings and premium volumes hold as global auto and replacement demand moves around.
The biggest operational risk right now sits in markets where pricing pressure from low cost imports and ongoing restructuring costs are already squeezing returns, especially Latin America and parts of Europe. If those issues persist or deepen, the benefit from cost cuts and higher value tires could be partly offset. If they remain contained, the impact of this latest upgrade is helpful but not transformational.
With no fresh corporate announcements tied directly to this move in earnings expectations, the most relevant reference point is still Bridgestone’s broad plan to lean into premium and specialty tires while cutting costs and rebuilding underperforming regions. The higher forecast effectively tests how durable those efforts are when analysts update their models.
For you as a shareholder, the question becomes execution speed. Restructuring in Europe and Latin America, global cost reductions and a push into premium segments like ultra large mining and aircraft tires all support the same thesis. If management sticks to that playbook and keeps a lid on start up and restructuring expenses, the upgraded outlook reinforces the current catalysts rather than adding a new one.
Bridgestone’s current analyst framework points to revenues of ¥5,180.9b and earnings of ¥457.4b by 2029, based on assumed yearly top line expansion of 3.8% and a move in earnings from ¥408.0b today to the ¥457.4b consensus, an increase of about ¥49.4b.
Uncover why Bridgestone's fair value indicates a 4% potential upside to its current price that could close sooner than many investors expect.
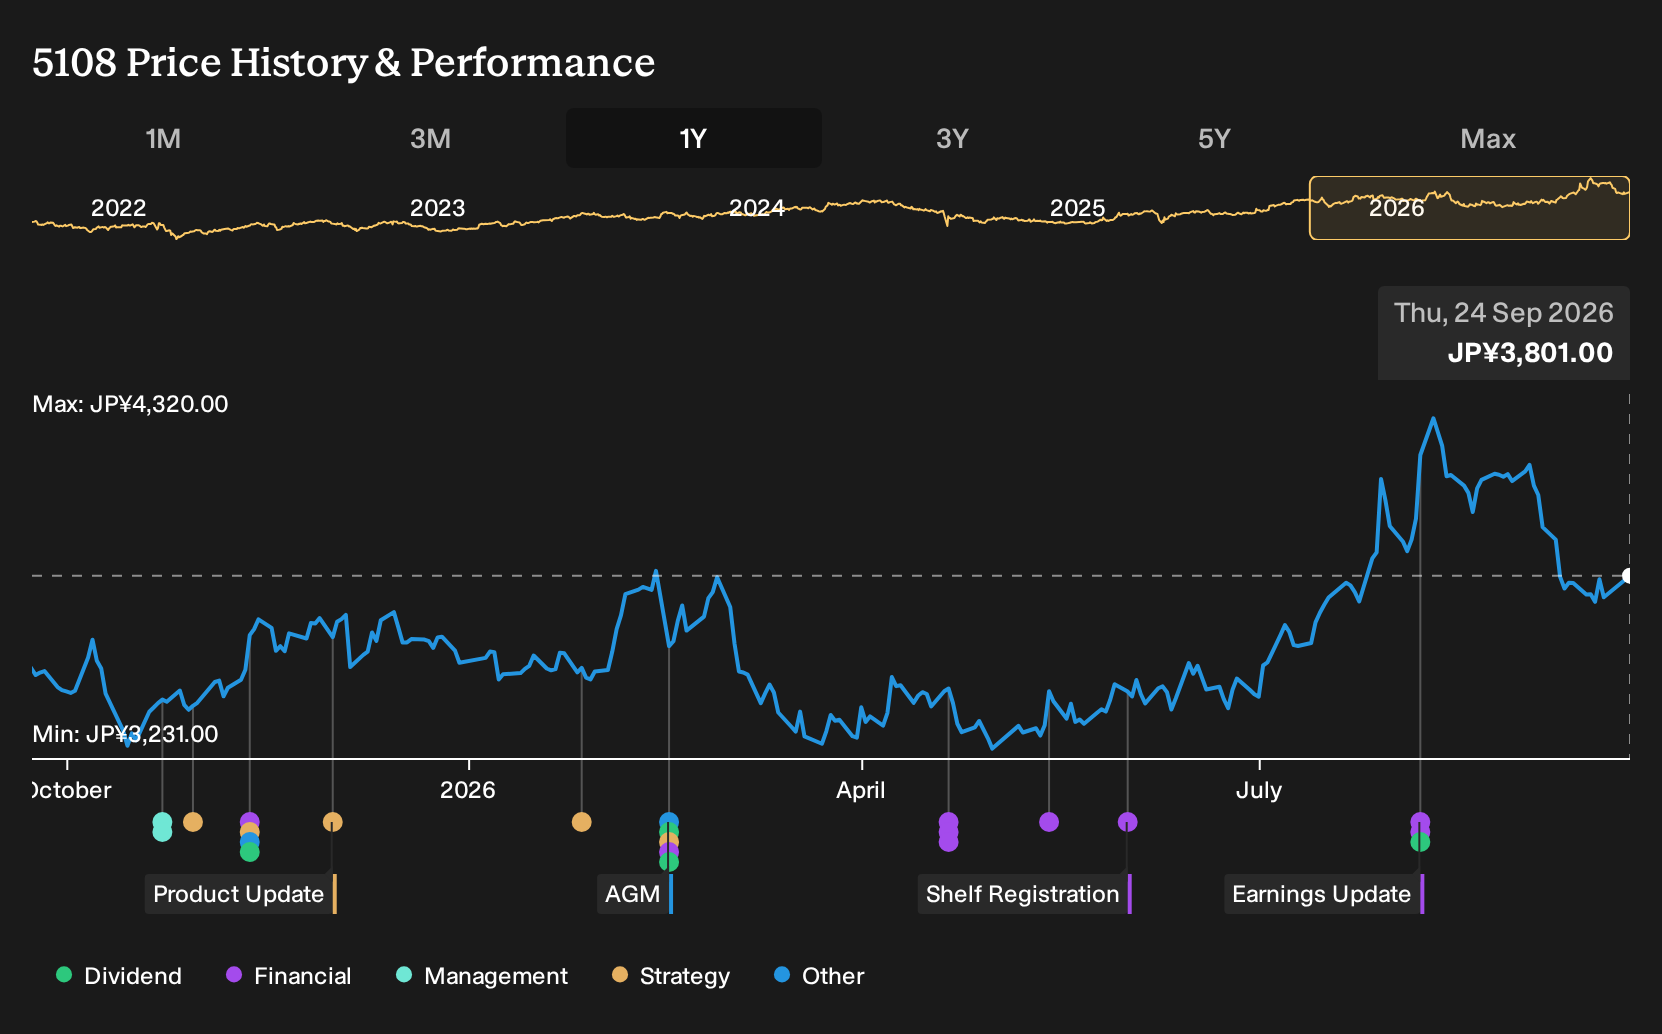
Exploring Other Perspectives
For Bridgestone, the bearish story leans heavily on North American truck and bus demand. Some of the lowest ranked analysts were working off revenue of about ¥4,754.3b and earnings of ¥363.2b by 2029, far below the ¥5,180.9b and ¥457.4b consensus path. That wide gap shows how sharply views could shift after this earnings news.
Explore another Bridgestone fair value estimate, including one that suggests it could be worth just ¥3953.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis.
- A great starting point for your Bridgestone research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bridgestone. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bridgestone's overall financial health at a glance.
Looking for more Bridgestone style investment ideas?
If the Bridgestone story has you thinking about where else upgraded earnings, solid balance sheets or resilient dividends might be quietly reshaping the risk and reward trade off, it can help to widen the lens beyond a single stock using the Simply Wall St Screener.
- For investors who want resilience first and upside second, start with a basket of companies that score well on financial strength using our list of solid balance sheet and fundamentals (21 results).
- If consistent income matters most to you, focus on businesses that currently offer higher yields with more robust payouts through our curated 15 dividend fortresses.
- When you prefer to hunt for opportunities where quality and valuation meet, filter for companies that combine stronger fundamentals with more modest pricing using the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com