
Is Investor Day Plan Altering The Investment Case For Nomad Foods (NOMD)?
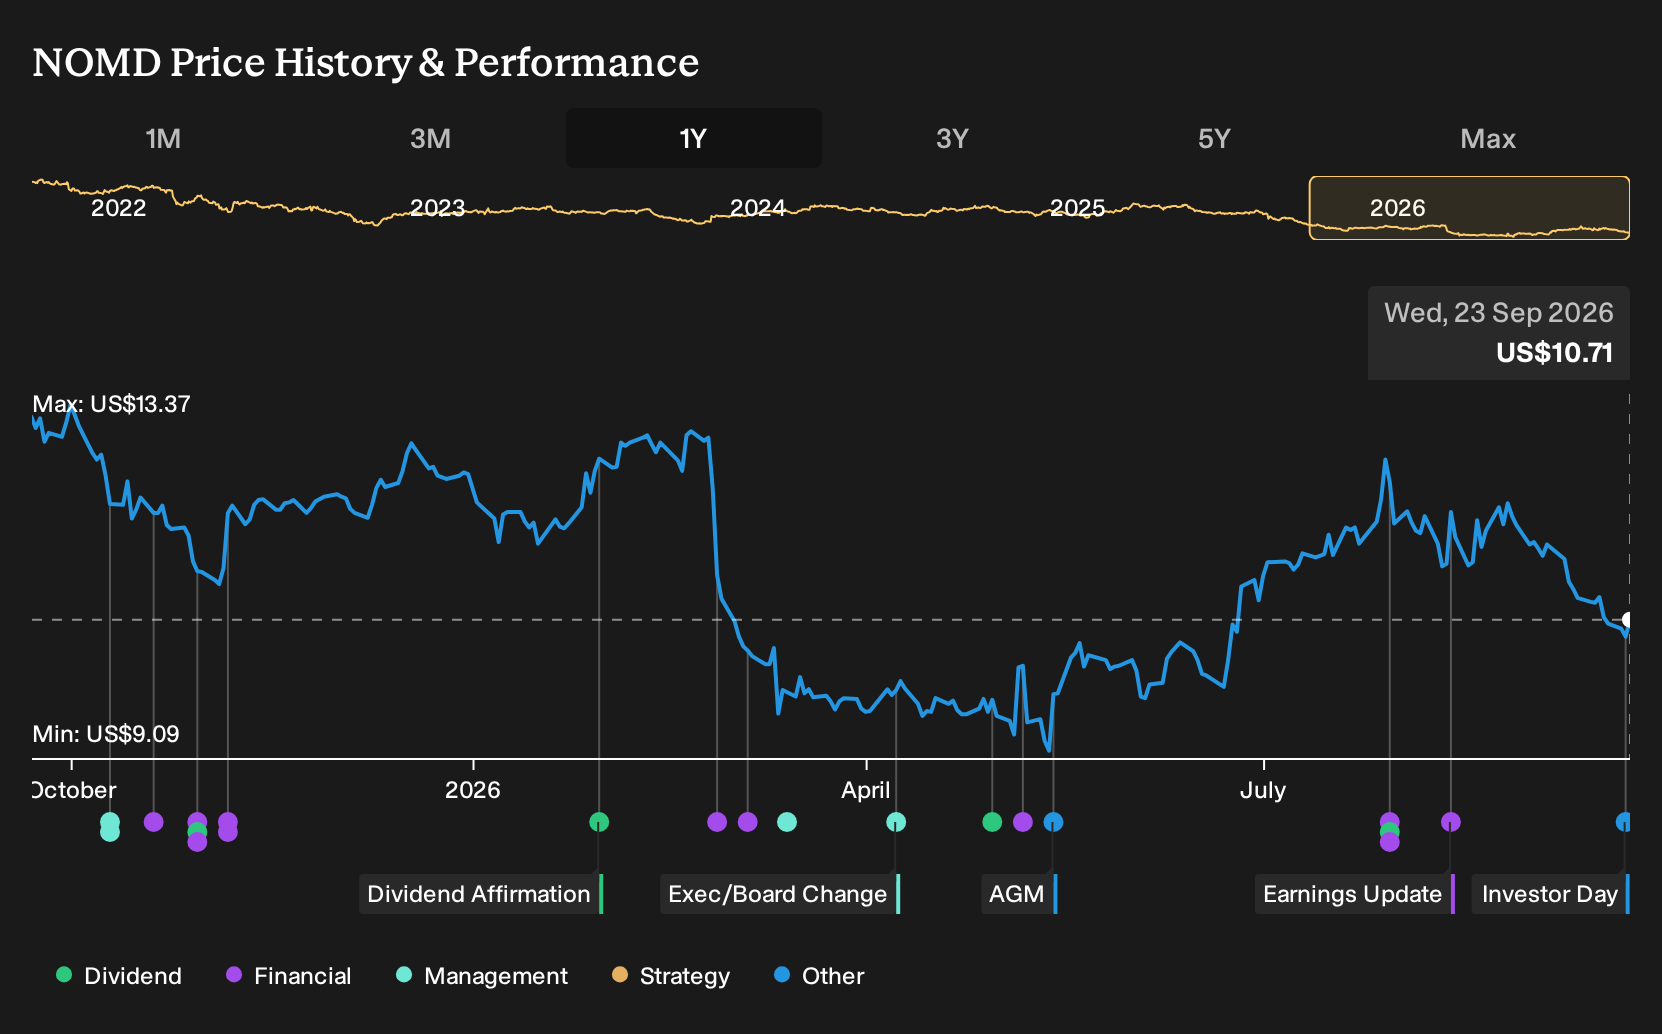
- Nomad Foods has scheduled an Analyst and Investor Day at the New York Stock Exchange on October 6, 2026. Senior leaders will review recent business performance and outline a multi-year Value Creation Plan covering growth, execution, and capital allocation priorities.
- The planned introduction of a detailed multi-year Value Creation Plan gives investors a clearer view of how Nomad Foods’ leadership is thinking about balancing product investment, cost discipline, and future capital deployment.
- We will now look at how Nomad Foods’ upcoming multi-year Value Creation Plan presentation could influence the company’s broader investment narrative.
Compare Nomad Foods’ upcoming Value Creation Plan with other potential compounders by scanning our hand picked list of 30 high quality undervalued stocks.
Nomad Foods Investment Narrative Recap
To own Nomad Foods, you need to believe the frozen portfolio can still support steady cash generation while management lifts earnings quality after a tough stretch. The big operational swing factor is execution. Previous ERP and inventory missteps, softer margins at 4.2% versus 6.9% last year, and a relatively new management team all put more scrutiny on day-to-day delivery.
The upcoming Value Creation Plan looks important for clarifying near-term priorities rather than changing the story. The key short-term catalyst is whether Nomad Foods can stabilise volumes and margins in its largely European footprint while keeping cost inflation in check. The main risk is that further operational hiccups or regional demand shocks keep pressure on profitability and cash flow coverage of debt.
The Analyst and Investor Day at the New York Stock Exchange is the clearest near-term operational milestone. Management has flagged a multi-year Value Creation Plan that will set out growth, execution, and capital allocation priorities, plus a business performance update and Q&A. That format gives investors a concentrated read on how the leadership team plans to address recent missteps.
For anyone tracking catalysts, the session matters because it links directly to known pressure points. Investors get a chance to see how Nomad Foods frames margin recovery after one-off losses, discusses debt relative to operating cash flow, and positions categories such as snacking, chicken, and natural fish. Execution against the plan, rather than the plan itself, will be what investors focus on afterward.
Nomad Foods' current analyst narrative points to €3.0 billion of revenue and €221.9 million of earnings by 2029, with earnings today at €132.9 million. This setup assumes relatively flat revenue over the next few years and an earnings increase of about €89 million from current levels to the 2029 consensus figure.
Uncover why Nomad Foods' fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on execution risk and more on product innovation as a potential upside swing factor for Nomad Foods. Before this Investor Day was announced, the bullish camp was already modelling €3.0b of revenue and about €198.6m of earnings by 2029. Those views could shift once the new plan lands, so compare several perspectives before deciding what feels reasonable to you.
Explore 8 other Nomad Foods fair value estimates, including one that suggests as much as 203% above the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nomad Foods research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nomad Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nomad Foods' overall financial health at a glance.
Looking for more ideas beyond Nomad Foods?
Once you have a view on Nomad Foods, it can help to set it against a wider watchlist so you see how its risk and return profile compares with other opportunities.
- For investors who prioritise resilient balance sheets and dependable fundamentals, start by scanning a list of solid balance sheet and fundamentals (23 results) that can help you stress test your quality bias.
- If your focus is on companies that the market may be underpricing based on their fundamentals, compare Nomad Foods with a 30 high quality undervalued stocks that share a similar quality and valuation mix.
- Income focused portfolios can benefit from a shortlist of higher yielding options, so round out your research with a curated set of 7 dividend fortresses that might complement a holding like Nomad Foods.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com