
How Strong Earnings Will Impact Matson Stock Investors
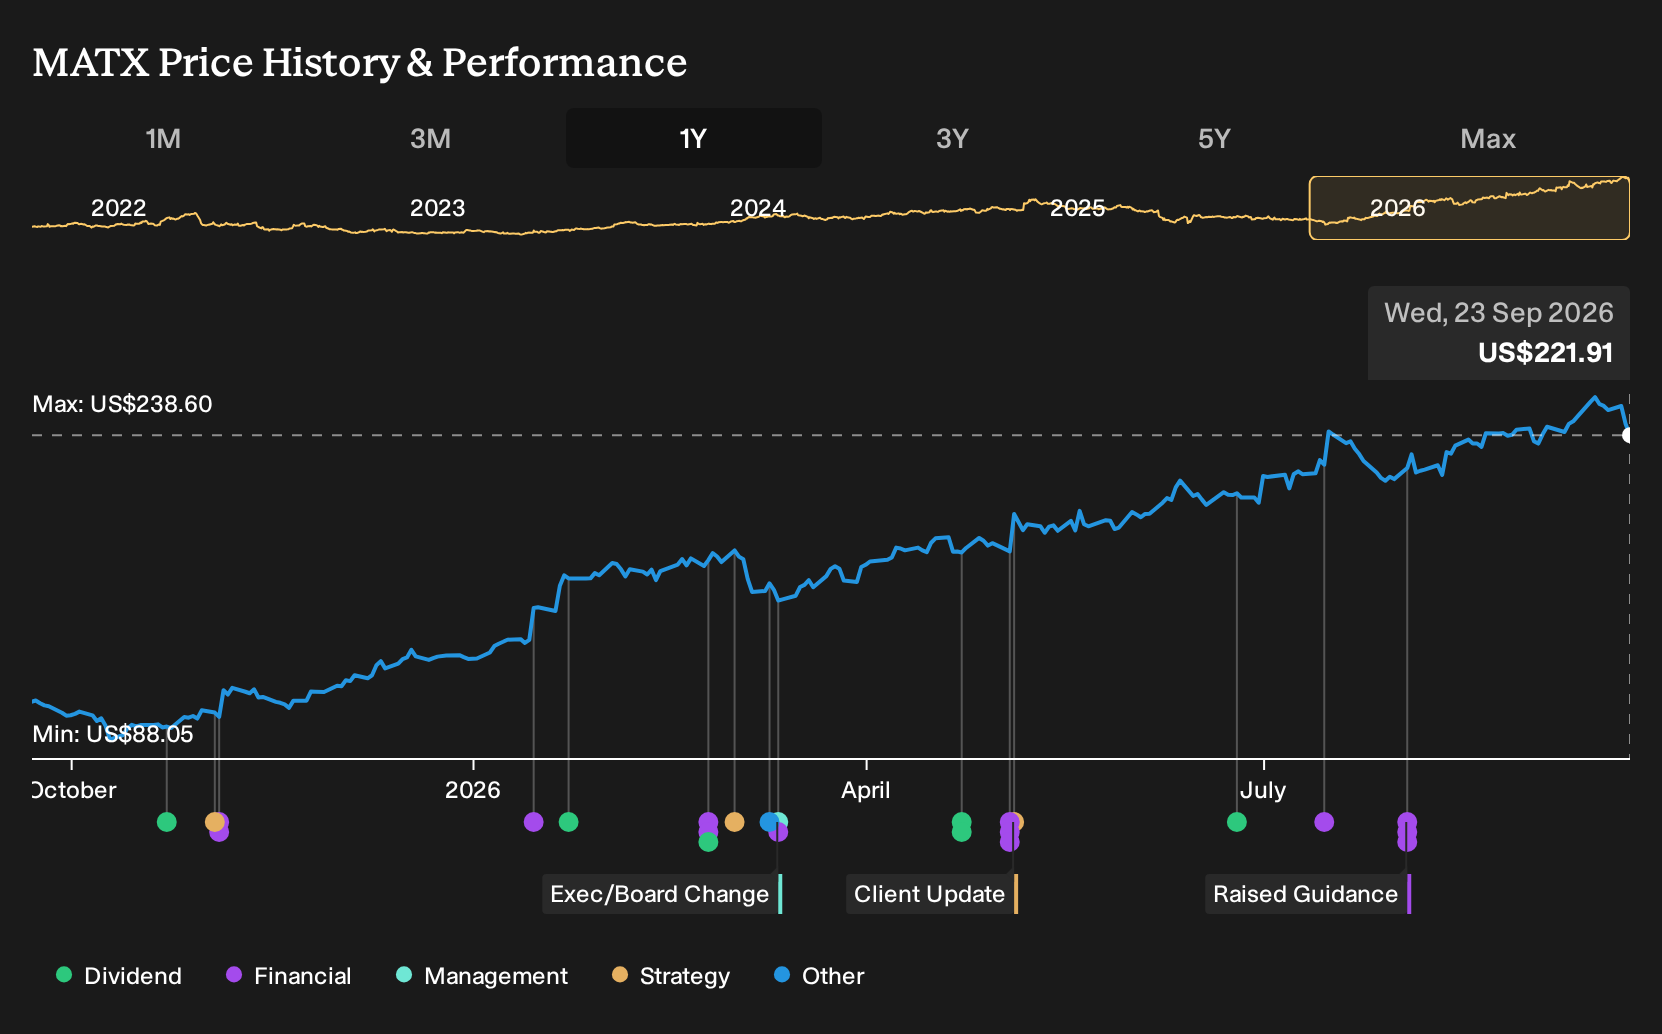
- Matson reported exceptional Q2 2026 results, with operating income up 40.6% year over year, driven mainly by strong China service performance.
- Management raised the quarterly dividend and expanded share repurchase capacity, signaling confidence even as domestic volumes softened and insiders sold stock.
- We will now look at how Matson's investment narrative could be influenced by its stronger China earnings and richer shareholder returns.
Scan beyond Matson's surge and insider selling, and line up other transport and logistics plays with resilient balance sheets using our curated list of solid balance sheet and fundamentals (23 results) as a comparison set.
Matson Investment Narrative Recap
To own Matson, you need to be comfortable with a story that leans on protected U.S. routes and higher margin transpacific services, particularly China. The recent surge in China earnings and Q2 strength keeps that thesis intact for now. The key near term swing factor remains freight demand and pricing on those expedited lanes, which the latest quarter supported.
The biggest risk still sits with concentrated trade exposure and heavy capital needs for vessels if volumes soften. Domestic weakness and insider selling add another layer of caution but do not fundamentally change the operational debate. You are weighing resilient lanes against trade volatility and cash flow pressure.
The Q2 move to raise the dividend and expand buybacks is especially important in this context. It indicates that Matson currently has room in its cash generation to fund higher shareholder payouts alongside its operating needs, at least based on recent conditions. That connects directly to how you think about near term returns from the China service and core Jones Act routes.
Those capital return decisions also intersect with the main risks. Higher dividends and repurchases can appear attractive when the stock trades below some intrinsic estimates, yet they may limit flexibility if trade volumes weaken or vessel spending rises. For you as an investor, execution on fleet investment and pricing in key lanes now sits under a brighter spotlight.
What The Current Forecasts Assume For Matson
Analyst models for Matson lean heavily on steady revenue expansion and only modest compression in profitability. Consensus expectations point to revenue increasing by 5.1% a year over the next three years, while profit margins are modeled to ease from 13.4% today to 12.4% in three years.
On earnings, the group of forecasters has Matson moving from $463.8 million today to $496.8 million by 2029, with earnings per share at $17.88. That shift implies an earnings increase of about $33 million from current levels, which is a relatively contained step up compared with the absolute size of the profit base.
Overlaying those profit assumptions, the same reports imply a re-rating in the stock. To match the analyst price target, Matson would be trading on a P/E of 17.2x by 2029, compared with 14.4x today and a US shipping peer group around 11.5x. Forecasters also build in ongoing buybacks, with the share count expected to fall by roughly 4.09% each year for the next three years, which can lift earnings per share even if headline profit growth is modest.
Matson's narrative projects $4.0b revenue and $496.8 million earnings by 2029. This requires 5.1% yearly revenue growth and an earnings increase of about $33 million from $463.8 million.
Those inputs carry clear implications for how you treat the recent China strength and the richer capital return story. For the analyst case to hold, top line trends need to track that 5.1% annual growth path and margins only need to slip slightly, even while Matson retires stock and maintains higher dividends. Any combination of weaker freight conditions in the China service, tougher pricing in domestic lanes, or higher than planned vessel spending would challenge that setup and could make the implied 2029 earnings and valuation multiple harder to justify.
Uncover how Matson's fair value indicates an 18% potential upside to its current price that could narrow quickly if expectations stay intact.
Exploring Other Perspectives
For a different angle on Matson, focus on the bullish catalyst around Southeast Asia growth. The most optimistic analysts were already penciling in about $4.0b of revenue and $528.7 million of earnings by 2029, before this strong Q2 and the upcoming Morgan Stanley Laguna conference, so their upbeat storyline could shift again as new information lands.
Explore 7 other Matson fair value estimates, including one that suggests as much as 226% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Matson research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Matson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Matson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Matson?
Once you have a view on Matson, it can help to put that thesis alongside other companies with different risk and return profiles. Use the Simply Wall St Screener to build a short list that fits the type of opportunities you want to research next.
- If you want potential value opportunities with solid fundamentals, line up a comparison set using the 16 high quality undiscovered gems.
- For investors who care most about balance sheet resilience and durable financial footing, start with the list of solid balance sheet and fundamentals (23 results).
- If lower volatility and steadier characteristics are a priority, narrow your search using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com