
StandardAero (SARO) Could Be 41% Undervalued Following India Service Agreement
StandardAero (SARO) just signed a Supplier Service Agreement with GMR Aero Technic, tying its engine maintenance expertise more closely to India’s large narrowbody fleet and creating a fresh angle for investors to track.
Despite the new GMR Aero Technic agreement and a recent appearance at MRO Asia on 22 September 2026, StandardAero’s share price has drifted, with a 30 day share price return down 8.1% and a year to date share price return down 23.8%, while the 1 year total shareholder return is down 13.8%, pointing to fading momentum even as the business lines up new work in key aviation markets.
Compare StandardAero’s new India-focused opportunity set with other aviation and industrial stocks on our curated 39 power grid technology and infrastructure stocks
StandardAero now trades at a steep discount to analyst targets even as it signs fresh work in India. Is this simple mispricing, or is the market treating recent growth and contracts with justified caution as investors weigh valuation next?
Price-to-Earnings of 22.7x: Is it justified?
StandardAero changes hands at a P/E of 22.7x, and at a last close of $22.58 the stock screens as cheaper than peers that carry higher earnings multiples.
The P/E ratio compares what the market is willing to pay today for each dollar of current profit. For an aerospace engine services group like StandardAero, which earns the bulk of its $6.3b revenue from recurring maintenance and repair work, that lens focuses attention directly on profitability rather than sheer top line scale.
SARO is described as trading at good value compared to peers and the wider Aerospace & Defense sector, with its 22.7x P/E below both the peer average of 57.1x and the industry average of 34.9x. The fair P/E estimate of 25.9x is also higher than where the shares currently sit, which indicates a level that pricing could plausibly gravitate toward if the market aligns more closely with that regression based fair ratio.
In that context, earnings quality and growth assumptions play an important role. SARO is assessed as having high quality earnings, reports improved net profit margins of 5.1% compared with 2.4% a year earlier, and has grown net income annually based on the supplied statements. At the same time, forecasts point to earnings growth of 17.5% per year that is described as not significant and slightly slower than the wider US market, which may help explain why the P/E has not moved closer to peer levels despite this track record.
Result: Price-to-Earnings of 22.7x (UNDERVALUED).
Explore the SWS fair ratio for StandardAero.
Still, StandardAero’s story can break if the share price slide deepens into a broader de-rating or if large customers slow engine maintenance spending and squeeze margins.
Find out about the key risks to this StandardAero narrative.
Another view on StandardAero’s value
The SWS DCF model presents a different perspective on StandardAero. At a share price of $22.58, the stock is described as trading 40.6% below an estimated future cash flow value of $38.04, which is characterized as undervalued by that approach.
This gap reflects two very different analytical lenses. One approach uses today’s earnings multiple against peers; the other projects future cash flows and discounts them back. If both approaches are accurate, that suggests a wide margin of safety. If the DCF proves too optimistic, the room for error is smaller than it appears on paper.
For readers who rely on cash flow based analysis, our DCF model for StandardAero is laid out in full so you can evaluate the inputs directly. Look into how the SWS DCF model arrives at its fair value.
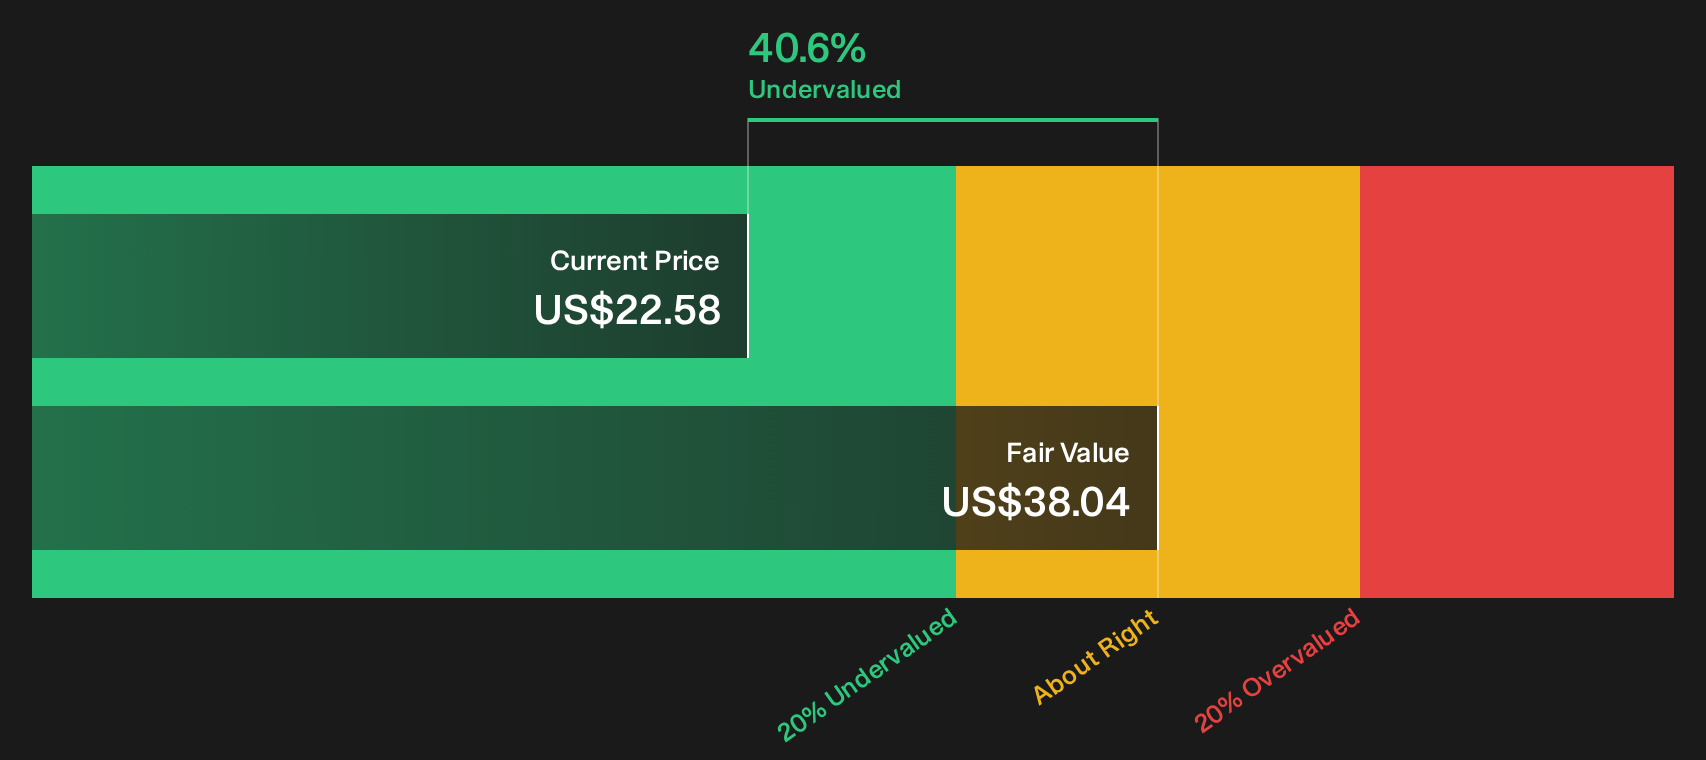
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out StandardAero for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on StandardAero so far. If you want to move quickly and form your own stance using the latest data, start with our breakdown of 5 key rewards and 2 important warning signs.
Looking for more StandardAero sized investment ideas?
If StandardAero has sharpened your focus on valuation, do not stop here. Your next strong idea might come from a very different corner of the market.
- Scan for potential bargains that combine quality and attractive pricing by running the 30 high quality undervalued stocks before the crowd catches on.
- Strengthen your income toolkit and check which companies offer dependable cash returns through the 7 dividend fortresses while yields remain compelling.
- Prioritise resilience and protect your downside by filtering for sturdier balance sheets using the list of solid balance sheet and fundamentals (23 results) right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com