
Learn Why The Bull Case For Astronics (ATRO) Could Change Following Record Backlog
- Astronics reported a record backlog and strong near term revenue visibility across its aerospace and defense systems portfolio, reinforcing line of sight on contracted demand.
- The focus on converting that backlog into free cash flow has put Astronics' cash generation and execution discipline at the center of investor attention.
- This analysis reviews how Astronics' investment narrative is influenced by record backlog levels and clearer near term revenue visibility.
Scan beyond Astronics and identify other aerospace and defense contractors with growing order books by using our curated list of list of solid balance sheet and fundamentals (23 results)
Astronics Investment Narrative Recap
To own Astronics, you need to believe its record backlog in aerospace and defense can convert into durable cash generation rather than just paper demand. The short term swing factor is execution on that order book, especially turning near term revenue visibility into consistent free cash flow while keeping program delivery on schedule and cost estimates tight.
The biggest near term risk remains cost and complexity. Tariffs, restructuring, and the historically weaker Test Systems segment create room for project overruns or margin pressure. The recent backlog news does not remove those issues. It increases the stakes on whether Astronics can run its operations with tighter discipline.
The most relevant development around this story is the discounted cash flow work suggesting Astronics trades below an estimate of its future cash flow value. That view relies on the idea that the current backlog in aerospace and defense systems converts into higher free cash flow over time rather than being held back by cost inflation or delays.
For investors, this links directly to catalysts and execution. Higher aircraft production, portfolio simplification, and tariff mitigation only matter if they translate into cleaner earnings and better cash conversion. At the same time, debt levels, legal and one off items, and exposure to commercial aerospace cycles remain key operational watchpoints for the Astronics thesis.
Astronics' current analyst narrative points to revenues of US$1.1b and earnings of US$201.7m by 2029, based on an assumed 5.3% yearly revenue growth rate. That path implies earnings today of US$79.1m would need to increase by about 2.6x to reach the 2029 consensus figure.
Uncover why Astronics' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
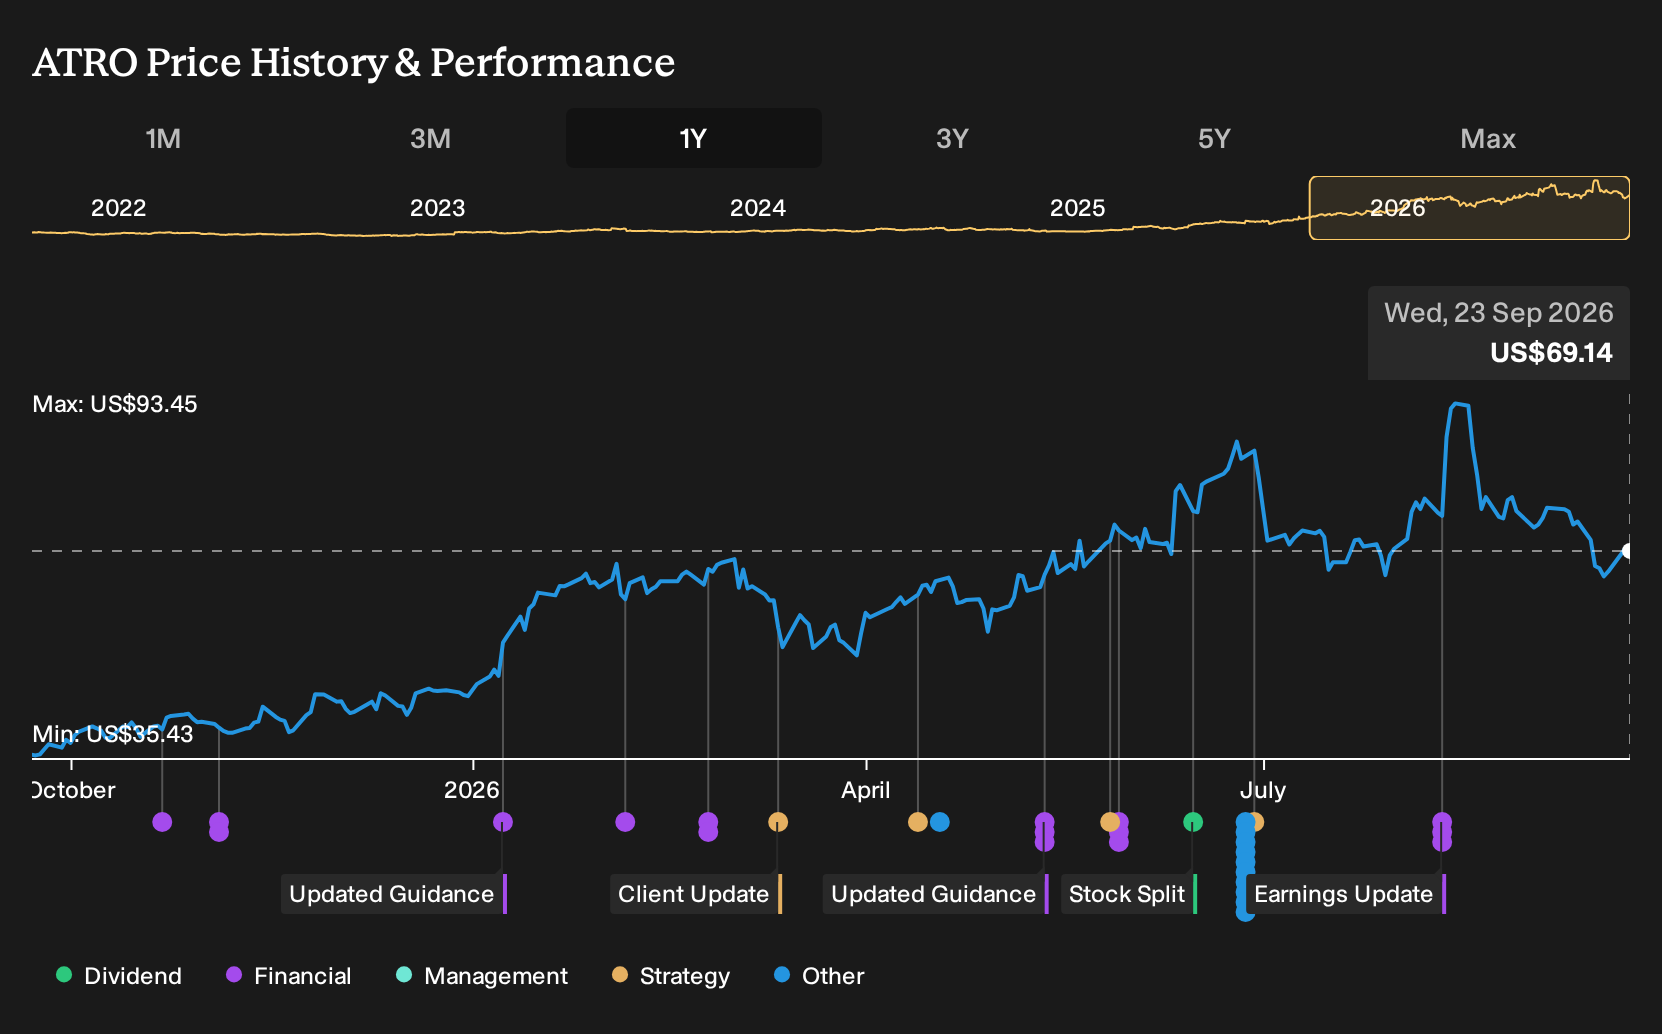
Exploring Other Perspectives
One alternate angle on Astronics focuses less on tariffs and more on customer concentration. The most optimistic analysts were already modeling revenue reaching about US$1.5b and earnings of roughly US$276.4m by 2029 before this backlog update. You can compare that upbeat view with your own, and watch how opinions shift as new data lands.
Explore 3 other Astronics fair value estimates, including one that suggests up to 55% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Astronics research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Astronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astronics' overall financial health at a glance.
Looking For More Astronics-Like Investment Ideas?
If the Astronics story has sharpened your focus on cash generation, balance sheets, and execution risk, widen the lens and use the Simply Wall St Screener to find other businesses that match the traits you care about most.
- If capital preservation ranks high for you, filter for sturdier businesses using our 31 resilient stocks with low risk scores to target approaches that aim to keep drawdowns in check while still offering equity upside.
- For readers hunting for quality at a reasonable price, scan our 30 high quality undervalued stocks to explore companies with strong fundamentals trading below estimated fair value.
- Income focused investors who want cash returns from day one can review our 7 dividend fortresses to see higher yielding stocks with robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com