
NiSource (NI) Could Be 21% Undervalued Following Its Long Term Growth Update
Why NiSource Stock Is Back In Focus
NiSource (NI) is drawing fresh attention after analysts collectively reiterated a strongly positive stance on the regulated utility, highlighting its role as a steady natural gas and power provider across six states.
For investors tracking income-focused utilities, the reiterated optimism around NiSource, together with its 14-year streak of dividend increases, is prompting another look at how the stock fits into long term portfolios.
Recent trading has been choppy for NiSource, with the share price down 1.6% on the day and weaker 7 day and 30 day share price returns feeding into a 90 day decline of 17.9%. At the same time, the 3 year total shareholder return of 71.1% and 5 year total shareholder return of 90.6% keep the longer term story firmly in positive territory.
Scan beyond NiSource and see how it compares to a hand picked 7 dividend fortresses that also aims to pair income potential with regulated or resilient cash flows.
NiSource now trades well below the average analyst target after a sharp 90 day slide, so the next step is simple: Is that discount a clear opportunity or a warning the market is flagging something real?
Most Popular Narrative: 21% Undervalued
NiSource is trading at $39.25 compared with a widely followed fair value estimate of about $49.86. This suggests a sizeable valuation gap that the market is being asked to justify.
Strong visibility into multi year, rate based capital expenditure has been updated to a plan through 2033 that supports 9 to 11% consolidated rate base growth and higher long term adjusted EPS CAGR guidance of 9 to 10%. This can compound regulated revenue and earnings as projects enter the rate base.
See why 9 investors see NiSource as 21% undervalued.
Result: Fair Value of $49.86 (UNDERVALUED)
Still, two pressure points could disrupt the NiSource story: faster policy pushes away from natural gas and heavy funding needs that lean on fresh equity and debt.
Find out about the key risks to this NiSource narrative.
Another View: NiSource Through a Cash Flow Lens
The upbeat fair value of $49.86 for NiSource contrasts with our DCF model, which estimates future cash flows at $36.52 per share. On that measure the stock trades above intrinsic value, so the market is already paying up for the growth story. Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
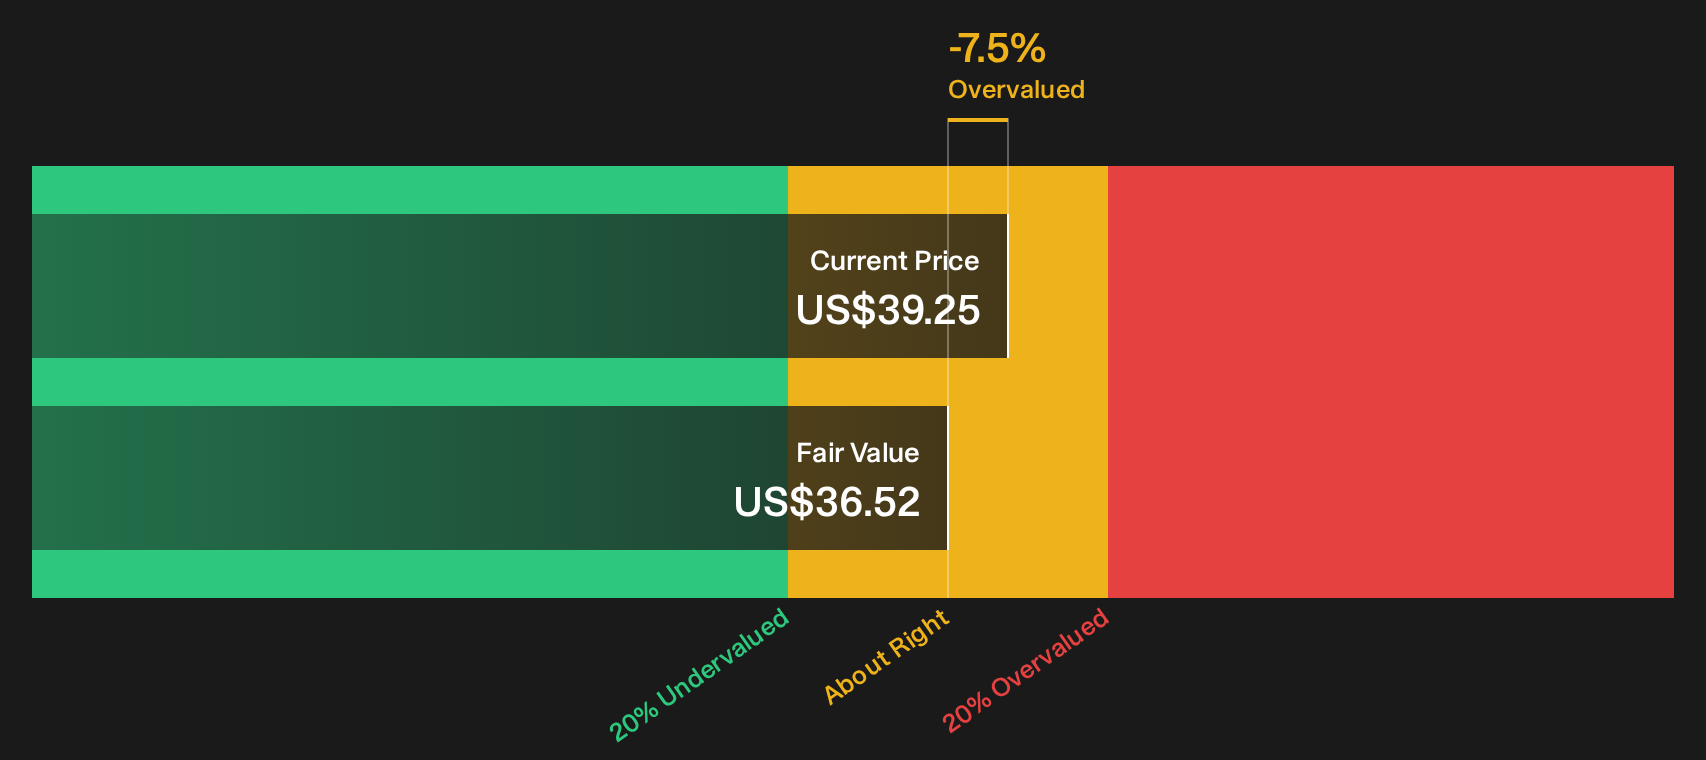
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NiSource for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around NiSource can feel confusing, so move quickly, look through the full data, then weigh the 3 key rewards and 3 important warning signs against your own view.
Looking For More Ideas Beyond NiSource?
If NiSource has you thinking more carefully about where your next dollar goes, use that momentum and scan wider before the market moves without you.
- Target resilience first and stress test your portfolio with a 31 resilient stocks with low risk scores that focuses on businesses built to handle tougher conditions.
- Hunt for pricing gaps and let the data surface 30 high quality undervalued stocks that might not stay mispriced for long.
- Round out your watchlist and surface a list of solid balance sheet and fundamentals (23 results) that can support operations without leaning too heavily on fragile funding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com