
Phillips 66 (PSX) Faces Bayway Labor Spotlight, Is The Stock Expensive?
Phillips 66 (PSX) is back in focus after Bayway Refinery workers, represented by Teamsters Local 877, scheduled a rally ahead of contract talks, putting labor relations and operating continuity on investors' radar.
Recent trading suggests investors are reassessing risk around Phillips 66. The share price has pulled back over the past week but still posts a 30-day share price return of 6% and a 90-day gain of 49.3%. The 1-year total shareholder return of 93.3% and 5-year total shareholder return of about 3.4x indicate strong longer term momentum building behind the story.
Spot 30 high quality undervalued stocks that, like Phillips 66, are drawing fresh attention as investors weigh operational risks against strong recent share price momentum.After a near doubling in 1-year total return and a recent pullback on labor headlines, Phillips 66 now forces a choice: pay up after the run, or wait and risk missing it. Let the valuation work answer that.
Most Popular Narrative: 24% Overvalued
Phillips 66 last closed at $256.48 while the most followed valuation story pegs fair value at $207.53. The narrative implies investors are paying a clear premium and raises the question of what could justify it.
Phillips 66 is executing on transformational growth opportunities like enhancing its NGL value chain and achieving growth in Midstream, which could drive revenue growth and earnings stability.
The company is improving its refining operations through low-capital, high-return projects, enabling better feedstock flexibility and yield, which can boost net margins.
See why 46 investors see Phillips 66 as 24% overvalued.
Result: Fair Value of $207.53 (OVERVALUED)
Still, the Phillips 66 story can change quickly if refining and renewable fuels margins compress, or if Midstream faces regulatory shifts that put cash flow under pressure.
Find out about the key risks to this Phillips 66 narrative.
Another View: Phillips 66 Through The DCF Lens
The first narrative flags Phillips 66 as 24% overvalued against a $207.53 fair value. Our DCF model points in the opposite direction. On that framework, PSX at $256.48 trades at a large discount to an estimated future cash flow value of $497.99, which screens as undervalued. Which story feels more realistic to you as an investor?
Look into how the SWS DCF model arrives at its fair value.
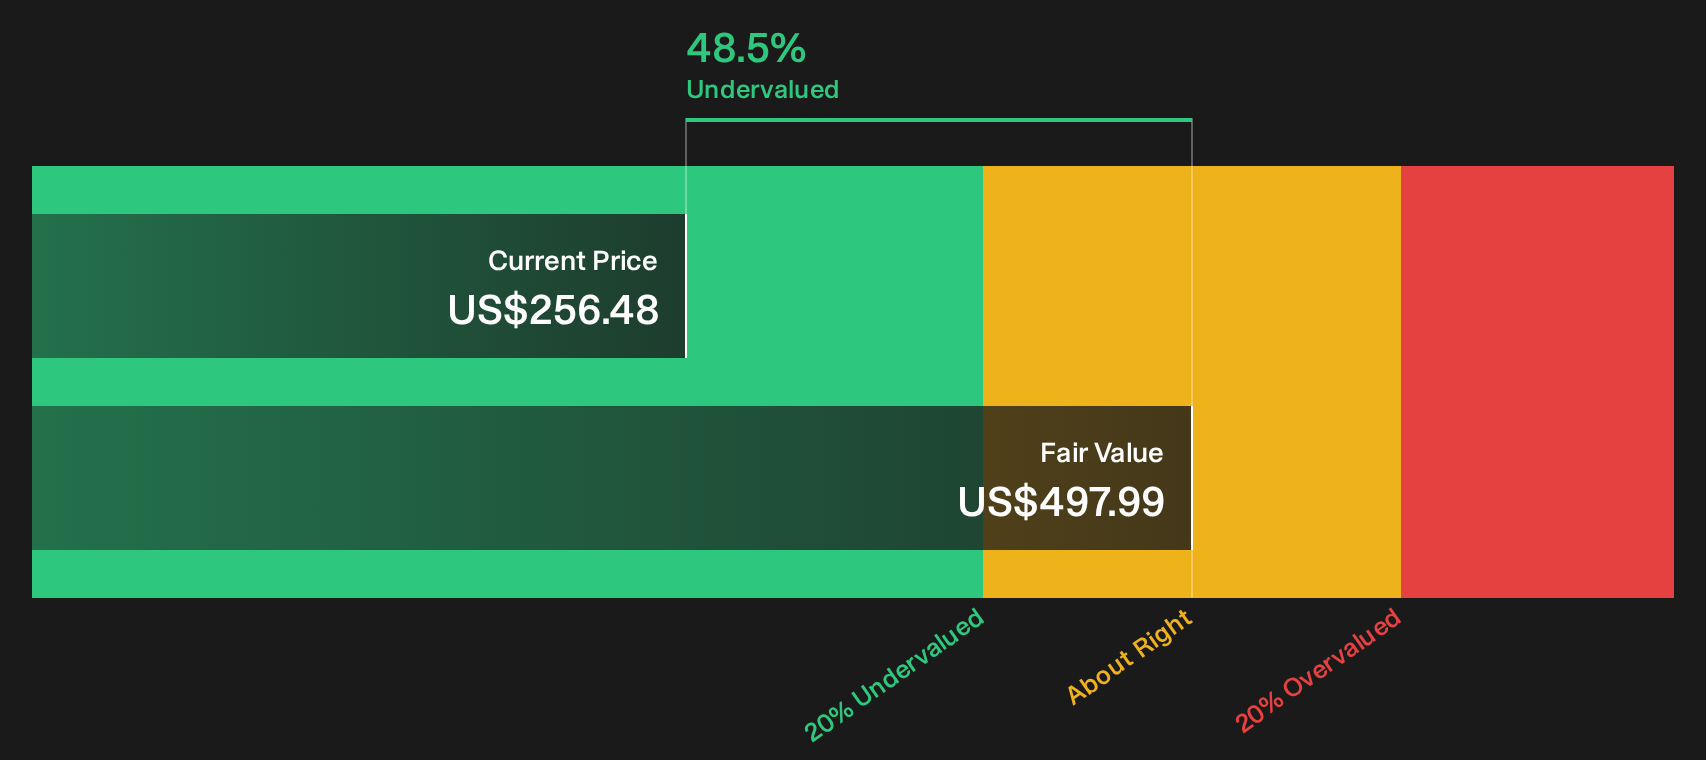
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Phillips 66 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Phillips 66 can feel confusing, so move quickly, look through the numbers, weigh the upsides against the red flags, then ground your own view in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Phillips 66?
If Phillips 66 has your attention, do not stop there. Cast the net wider now so you are not chasing the same crowded trades later.
- Target potential mispriced opportunities early by scanning the 30 high quality undervalued stocks that match your quality and valuation checklist.
- Build a sturdier core to your portfolio by focusing on companies with resilient finances through the list of solid balance sheet and fundamentals (23 results).
- Spot under-the-radar potential before the crowd notices by running your filters across the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com