
How PowerPort Verdict At Becton Dickinson (BDX) Has Changed Its Investment Story
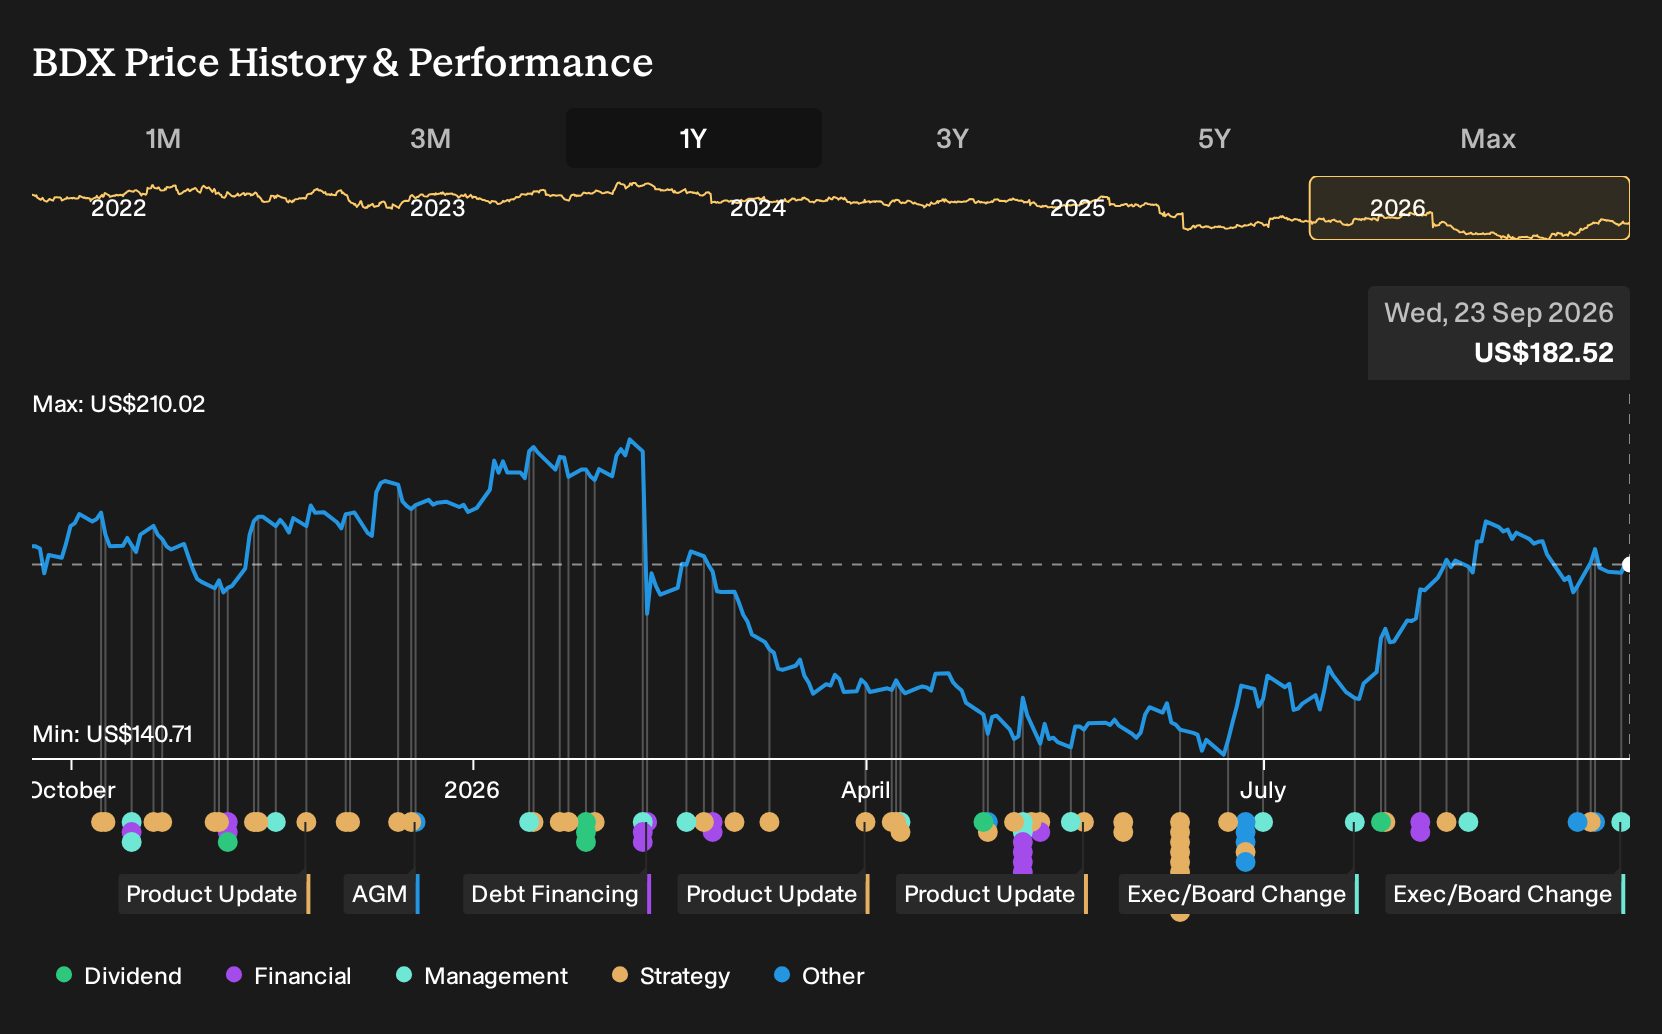
- Becton Dickinson faces growing product liability pressures as thousands of Bard PowerPort lawsuits advance, following a recent $40 million compensatory verdict against C.R. Bard.
- The scale of alleged device complications and nearly 4,000 pending cases introduces a legal overhang that could influence cash allocation priorities and future risk management costs at Becton Dickinson.
- This large Bard PowerPort verdict could also influence how investors view Becton Dickinson's broader narrative and overall risk profile.
Compare how Becton Dickinson handles legal and technology inflection points with peers by scanning hand picked 31 resilient stocks with low risk scores that also score well on balance sheet resilience and operational discipline.
Becton Dickinson Investment Narrative Recap
To own Becton Dickinson, you need to be comfortable with a slow top line, heavier regulatory and legal scrutiny, and a story that leans on margin improvement and cash generation rather than fast revenue expansion. The biggest near term swing factor is execution on productivity and product launches while absorbing tariff pressures and procurement volatility in places like China.
The most immediate risk sits in regulatory and legal exposure. The SEC settlement around Alaris disclosures, the Bard PowerPort litigation and the planned Biosciences and Diagnostics separation all stack on top of existing reimbursement and trade headwinds. These events can pull management attention and raise compliance and risk management costs, even if core demand stays stable.
The SEC cease and desist order around Alaris disclosures is the announcement most tightly linked to this legal backdrop. A US$175,000,000 penalty and a Fair Fund process that runs through December 2026 keep disclosure practices and internal controls under the microscope. For you, the question is whether stronger compliance systems become a durable operating cost or a catalyst for cleaner execution.
Set that beside BD Vmax 160 landing at Fairview Health Services. Pharmacy automation and the broader Incada Connected Care platform speak directly to one of the key catalysts analysts focus on: connected care and automation that can support pharmacy workflows and medication safety. If BD executes on these deployments while tightening regulatory governance, the mix of automation, recurring consumables and digital platforms remains central to the longer term thesis.
Becton Dickinson's current analyst script points to revenues of US$21.4b and earnings of US$3.3b by 2029, based on a projected 1.6% yearly decline in revenue and an increase in earnings of about US$1.7b from roughly US$1.6b today.
Uncover why Becton Dickinson's fair value indicates a 7% potential upside to its current price, which investors may see materialize sooner than expected.
Exploring Other Perspectives
One alternate view focuses less on product launches and more on pricing pressure. The most cautious analysts were assuming a 3.3% yearly revenue decline and earnings of about US$2.4b by 2029, well below the consensus US$3.3b. With the Bard PowerPort lawsuits in focus, that more pessimistic Becton Dickinson story could shift again.
Explore 2 other Becton Dickinson fair value estimates, including one that suggests it could be worth just $195.67.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Becton Dickinson research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Becton Dickinson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Becton Dickinson's overall financial health at a glance.
Looking For More Becton Dickinson Investment Ideas?
If you want to frame Becton Dickinson in a wider watchlist, it can help to scan other companies with different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about capital preservation and steadier risk profiles, review a 31 resilient stocks with low risk scores that can help you stress test ideas alongside Becton Dickinson.
- If income is your priority and you want to compare Becton Dickinson with cash generating payers, check out 7 dividend fortresses that currently clear a 5% yield hurdle.
- When you are hunting for under followed opportunities instead of well known large caps like Becton Dickinson, scan 16 high quality undiscovered gems that pair solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com