
Comcast (CMCSA) Stock May Be Undervalued After Fresh Streaming Network News
Comcast has seen its share price under pressure in recent years, and the question for investors now is whether the current valuation still lines up with what the business earns.
- Over the past 5 years, Comcast stock has fallen 49.3%, which puts the focus squarely on whether the earnings profile supports where the shares trade today.
- Recent moves to deepen streaming and enterprise network partnerships, including work with Fastly and Equinix, can influence expectations for future profit growth and the timing of cash generation.
- The analysts covering Comcast have run their own numbers. See what analysts think Comcast's shares could be worth.
The issue now is whether Comcast's current share price is adequately supported by its earnings power today and what investors expect those profits to look like over time.
If you are weighing Comcast against other plays on digital infrastructure and streaming, it can help to compare it with stocks filtered through the 85 AI infrastructure stocks.
Is Comcast Still Cheap on Earnings?
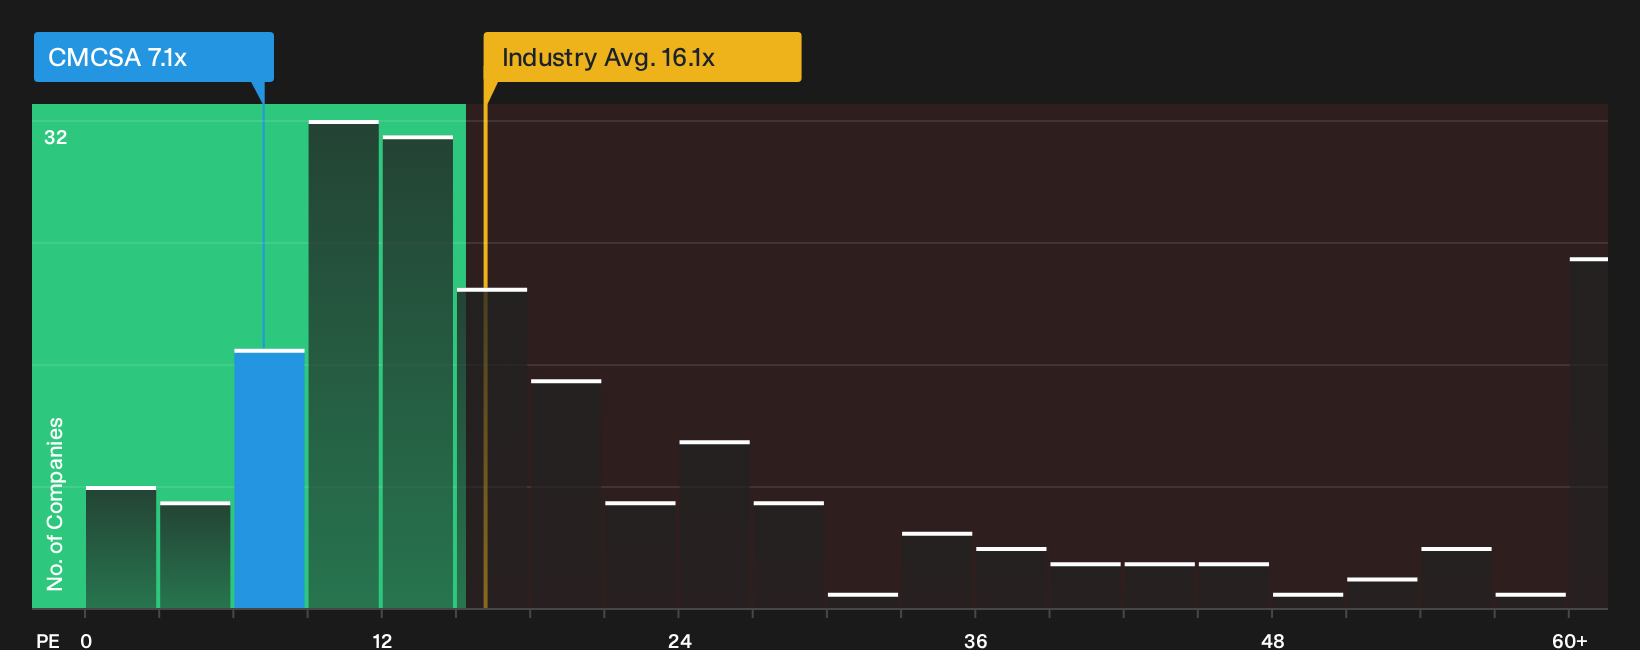
The P/E ratio fits Comcast because earnings still do most of the heavy lifting in how investors frame the business. On this yardstick, the stock trades on about 7.1x earnings, which is well below the broader telecom sector on roughly 16.1x and also under the peer group around 11.4x.
The gap to the sector is wide enough that a basic comparison suggests Comcast is currently trading at a lower earnings multiple than those peers. Because the recent Fastly and Equinix partnerships have put more attention on Comcast's streaming and enterprise prospects, the fact that the shares still change hands at this discount is an important data point for anyone weighing whether the current price already reflects that story. Explore the numbers behind Comcast's P/E valuation.
The Comcast Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Comcast valuation puzzle leaves off by explaining which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than it is today on the market. Each narrative links its figure to a clear view of where Comcast's expansion, profitability and key risks might go next, giving you a reference point you can revisit as new information becomes available.
Community views on Comcast are split between those who see underappreciated cash flows building and those who focus on structural pressure in broadband and media.
Bull case: 24% undervalued
"The main thing that has to go right is that Comcast converts its low-penetration wireless opportunity, Peacock’s early profitability, and growing experiences portfolio into sustained, higher quality cash flows..."
Discover why this Narrative puts Comcast at 24% undervalued.
Bear case: 7% overvalued
"Stagnant broadband growth remains a serious risk as the US market for broadband is reaching saturation, with slowing population growth and minimal expansion in addressable households..."
Explore why this Narrative puts Comcast at 7% overvalued.
One big Comcast question still sits just over the horizon
Valuation only tells you where Comcast is priced today, while professional forecasts sketch out where earnings and cash flows might be a few years down the road and how that lines up with the current multiple. Explore where analysts expect Comcast to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com