
New Leadership Might Change The Case For Investing In QXO Stock (QXO)
- QXO appointed Ken West as President and COO effective September 1, following its acquisition of TopBuild, after which QXO became the second largest publicly traded building products distributor in North America.
- Management is targeting more than double EBITDA by 2030 and US$50b in revenue within the decade, which places integration execution and Ken West's acquisition experience at the center of QXO's operating plan.
- We will now look at how QXO's investment narrative could be affected by Ken West taking charge of day to day operations.
Scan beyond QXO and this TopBuild integration story, and line up other potential consolidators with acquisition runways using our 16 high quality undiscovered gems in adjacent sectors.
What Is QXO's Investment Narrative?
The core QXO thesis is simple. You have to believe that a large scale building products distributor can turn an acquisitive roll up story into a disciplined operator that eventually earns its cost of capital on nearly US$10.0b of sales. That means efficient branches, clean integration of TopBuild, stable demand and pricing in roofing and siding, and enough free cash flow to justify past dilution and ongoing capital intensity. The Laguna conference slot on September 15 fits this. It gives management a high profile stage to explain how Ken West will translate big revenue targets into day to day execution.
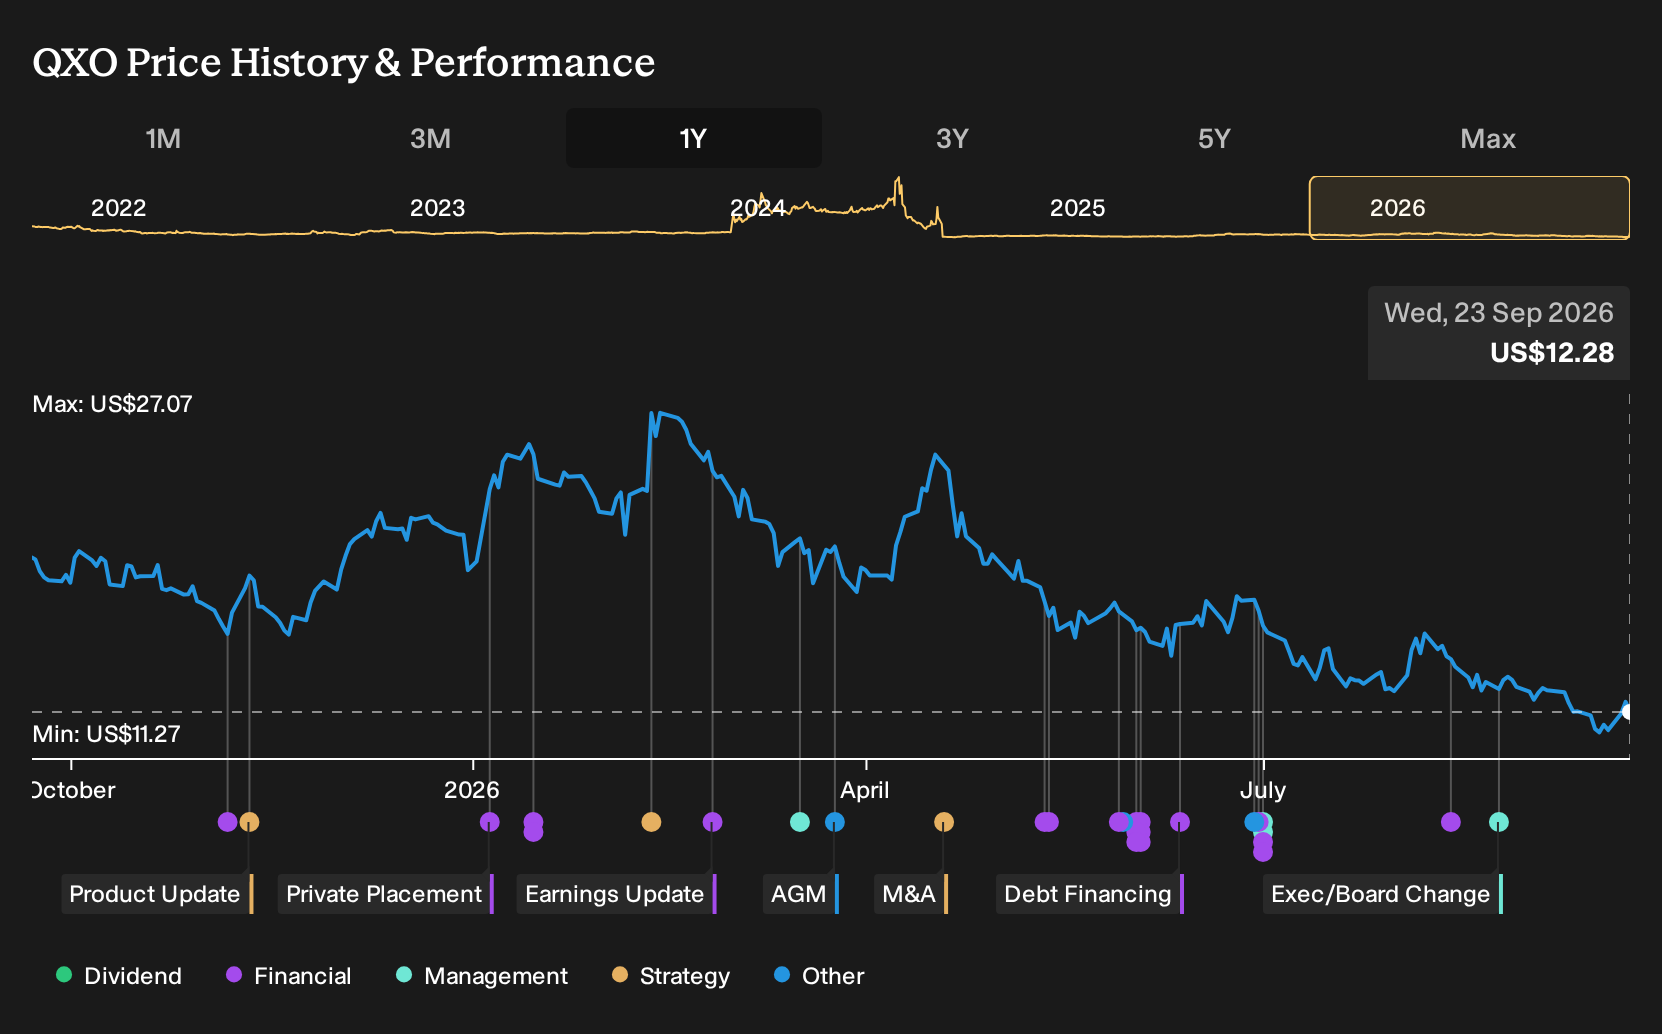
Short term, the key swing factors are integration progress, proof that QXO can move toward profitability on US$9,898.2m of revenue, and how it funds any further deals without repeating the heavy shareholder dilution flagged over the past year. The stock has fallen 38% year to date and 36% over twelve months, which tells you investors already price in execution risk. Any incremental detail at Laguna on acquisition cadence, funding mix, or returns on invested capital could matter a lot more than high level guidance slides.
That said, there is one pressure point in the QXO story that rarely makes it into the conference decks...
There's only one way to know the right time to buy, sell or hold QXO. Head to Simply Wall St's company report for the latest analysis of QXO's Fair Value.
Exploring Other Perspectives
Five fair value views from the Simply Wall St Community span a wide band, from US$12.54 to about US$57.82 per share. As a result, QXO attracts both deep discount hunters and far more optimistic holders. These opinions were formed before the Laguna presentation and Ken West’s expanded role, so you should treat the conference as fresh input and explore multiple angles before drawing your own conclusion.
Explore 4 other QXO fair value estimates, including one that suggests it could be worth just $12.54.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your QXO research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QXO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QXO's overall financial health at a glance.
Looking For More Investment Ideas Beyond QXO?
If QXO's story has you thinking about position sizing and portfolio balance, it can help to line it up against other opportunities that share some of the same qualities, or deliberately contrast it with very different types of businesses.
- For investors focused on quality at a sensible entry point, start by scanning a curated set of 30 high quality undervalued stocks that pair fundamentals with more grounded pricing.
- If income is a priority, compare QXO with companies designed to throw off cash to shareholders by reviewing a selection of 7 dividend fortresses that combine yield with business resilience.
- For a more defensive tilt, round out your watchlist by checking a 31 resilient stocks with low risk scores that screens for balance sheets and risk profiles built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com