
Is Jungheinrich (XTRA:JUN3) Undervalued Or Is Its High P/E Still A Warning Sign?
Jungheinrich (XTRA:JUN3) has drawn fresh attention after recent trading left the share price at €23.84, with the stock down over the past week and month but showing a gain over the past 3 months.
Recent trading sits against a tougher backdrop, with the share price return down sharply year to date while the 1 year total shareholder return has also declined. The latest pullback suggests momentum in Jungheinrich is still fading rather than recovering.
Compare how Jungheinrich stacks up against other potential rebound candidates by reviewing our hand picked 177 high quality undervalued stocks.
For Jungheinrich, a share price near €23.84 sits well below both analyst targets and some intrinsic value estimates. Is that discount pointing to genuine mispricing, or a fair markdown on the business?
Price-to-Earnings of 64.3x: Is it justified?
Jungheinrich trades on a P/E of 64.3x, which is high relative to many peers, even with the recent share price pullback to €23.84.
The P/E multiple compares what investors pay for each euro of current earnings. For a machinery and intralogistics specialist like Jungheinrich, a rich P/E usually implies the market is placing a strong emphasis on forward profit potential rather than recent headline results.
Recent fundamentals paint a mixed picture. Net profit margins have retreated from 5.2% to 0.7%, and earnings have declined by 11.2% per year over the past 5 years. On top of that, the latest 12 month figures include a large one off loss of €115.9m, which clouds the quality of reported profits and makes the 64.3x headline P/E harder to interpret as a clean signal of underlying performance.
Even allowing for those one off effects, the market is paying a much higher multiple than both the German machinery industry average P/E of 16.6x and a peer group average of 22.2x. It also sits above an estimated fair P/E of 42.8x, which points to a level the market could move toward if sentiment or earnings expectations reset.
Explore the SWS fair ratio for Jungheinrich.
Result: Price-to-Earnings of 64.3x (OVERVALUED)
Still, Jungheinrich faces clear risks, including pressure on already thin net income of €37.8m, as well as the potential for further share price weakness after a 33.9% YTD decline.
Find out about the key risks to this Jungheinrich narrative.
Another View on Jungheinrich's Value
On a different yardstick, Jungheinrich looks cheap. The SWS DCF model points to an estimated future cash flow value of €34.96 per share, with the current price of €23.84 sitting at a sizeable discount. Is the market overreacting to recent earnings noise, or is the model too optimistic?
Look into how the SWS DCF model arrives at its fair value.
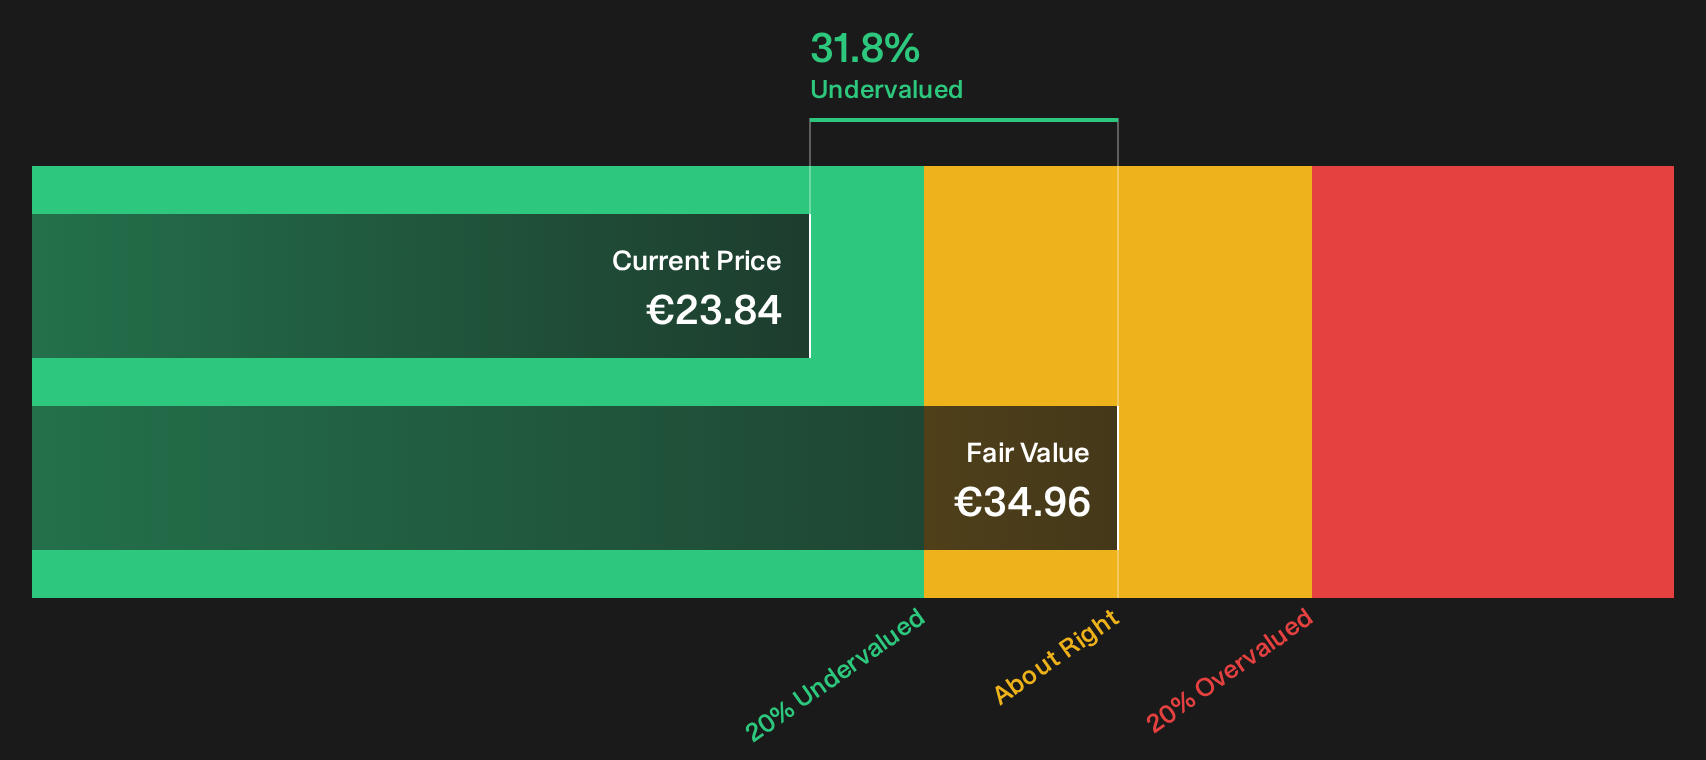
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jungheinrich for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 177 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Jungheinrich so far? Use this pullback as a prompt to review the key signals yourself and stress test the upside and downside. To see both sides of the story clearly, start with the 2 key rewards and 3 important warning signs.
Looking for more Jungheinrich sized investment ideas?
Do not stop your research with Jungheinrich. Broaden your watchlist with other stocks that match clear criteria so you are not relying on one turnaround story.
- Target potential turnaround stories where expectations look low but fundamentals still matter by reviewing the 177 high quality undervalued stocks.
- Build a portfolio that aims to keep income flowing even when prices move around by checking the 158 dividend fortresses.
- Prioritise resilience first and look for companies with stronger finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (200 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com