
Kratos Defense & Security Solutions (KTOS) Clears GEK800 Test As Fair Value Debate Builds
Kratos Defense & Security Solutions (KTOS) just cleared a key technical hurdle, with partner GE Aerospace confirming successful ignition of the GEK800 cruise missile engine at the X-58 test site.
For context, Kratos Defense & Security Solutions shares trade at US$46.16, with the 30 day share price return down 13.02% and the year to date share price return down 41.78%. The 3 year total shareholder return is more than 3x and the 5 year total shareholder return is 103.89%. This suggests that longer term holders have still seen strong gains despite the recent pullback as investors reassess both growth prospects and project execution risk around news like the GEK800 milestone.
Scan the defense sector for other propulsion, missile, and drone contractors with similar program momentum using our curated list of 93 robotics and automation stocks
Kratos Defense & Security Solutions now pairs a sharp pullback with fresh validation on a flagship engine program. Does that mix still tilt the risk reward toward new buyers, or has the easy upside already been used up?
Most Popular Narrative: 56% Undervalued
On the most followed narrative, Kratos Defense & Security Solutions screens as materially cheaper than an assessed fair value of $105.62, even after the recent slide to $46.16. That gap rests on a detailed view of how hypersonics, unmanned systems, and software heavy franchises might scale over time under an 8.0% discount rate.
Kratos' early investments in serial production of tactical drones (e.g., Valkyrie) and rapid scaling in missile propulsion and microelectronics put it ahead of competitors as demand for unmanned and autonomous solutions escalates globally. With sole-source and first-to-market positions, Kratos is positioned for significant incremental revenue and higher-margin growth as large contracts come online, particularly as international orders (with premium margins) ramp up.
See why 143 investors see Kratos Defense & Security Solutions as 56% undervalued.
Result: Fair Value of $105.62 (UNDERVALUED)
Still, that bullish Kratos Defense & Security Solutions narrative can crack if U.S. defense budgets shift or if heavy upfront spending does not translate into cash generation.
Find out about the key risks to this Kratos Defense & Security Solutions narrative.
Another View: Kratos Defense & Security Solutions Looks Pricey On Sales
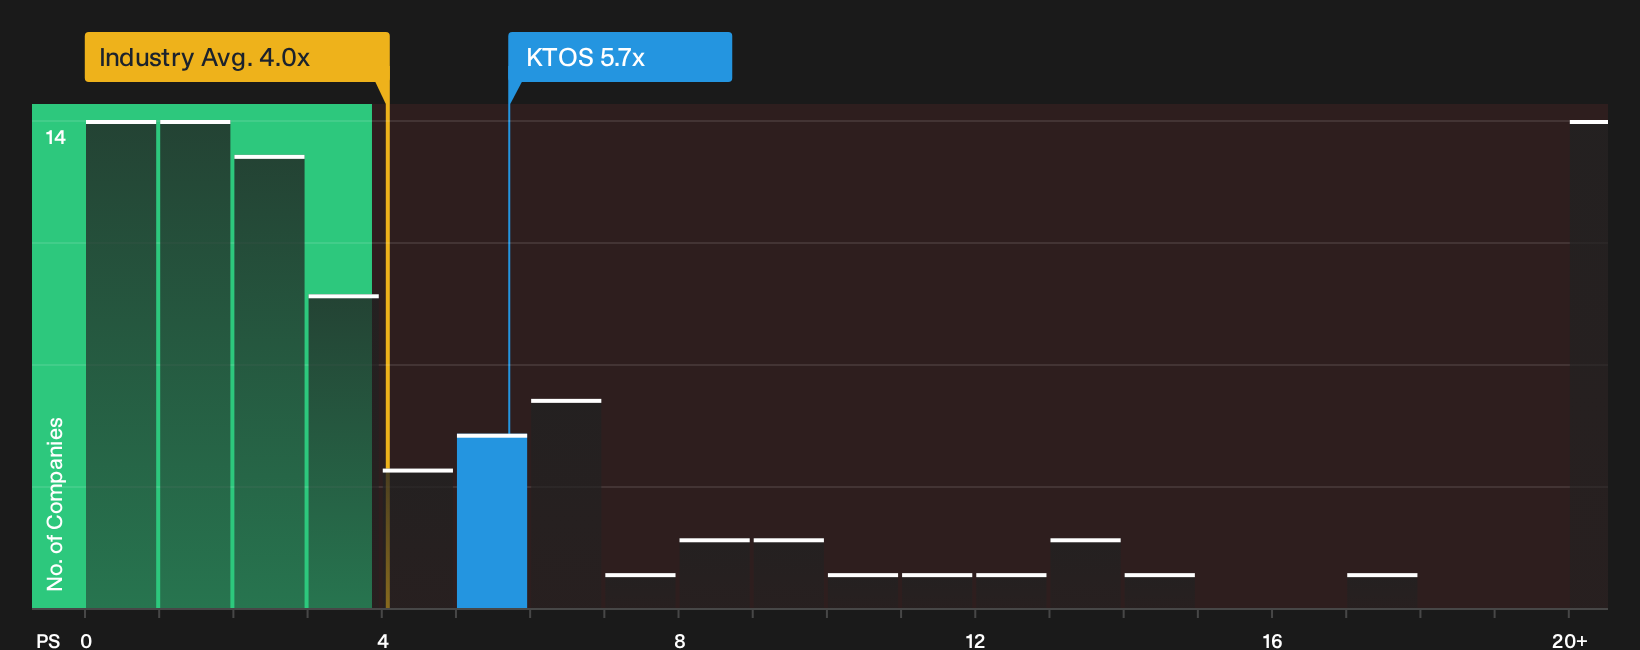
That fair value narrative paints Kratos Defense & Security Solutions as deeply undervalued, yet the market is already paying up on simple sales metrics. At a P/S of 5.7x versus a fair ratio of 3.2x, the stock also trades rich to the US Aerospace & Defense average of 4x and a peer mark of 2.5x. Is the crowd paying in advance for years of execution that still needs to be delivered?
To see how that premium pricing stacks up against the underlying numbers, take a closer look at our valuation breakdown, including the fair ratio and peer comparisons, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
This mix of optimism and concern around Kratos Defense & Security Solutions invites you to move quickly and examine the underlying data yourself before sentiment shifts again. To weigh both sides of the story in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more Kratos Defense & Security Solutions style ideas?
If you stop at Kratos Defense & Security Solutions, you risk missing other setups where quality, valuation, and risk balance might line up even better for your portfolio.
- Target potential upside by focusing on companies that pair resilient balance sheets with healthy fundamentals using our list of solid balance sheet and fundamentals (23 results)
- Look for possible mispriced opportunities where price and quality occasionally fall out of sync by screening through a curated pool of 16 high quality undiscovered gems
- Prioritise resilience first and tap into a pre filtered universe of 31 resilient stocks with low risk scores
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com