
Higher Rates Are Testing US Regional Bank Stocks Investors May Be Missing
Higher for longer is no longer just a slogan from the Fed; it is a test for every regional bank that lives off rate sensitive deposits. When borrowing costs sit in a 3.75% to 4.00% range and another hike is described as reasonable, investors who ignore this shift risk missing where pressure or resilience could build next. This article explains how that backdrop ties into three specific U.S. regional and community bank stocks exposed to the latest Fed signals, and outlines why each could matter for your watchlist.
The banks in focus below are just a starting sample. The full screen surfaced 32 more regional and community players with equally compelling rate sensitive deposit stories that are not covered here. To go straight to the broader opportunity set, analyze and compare candidates directly through the U.S. Regional and Community Banks with Rate-Sensitive Deposit Franchises screener.
GBank Financial Holdings (GBFH)
GBank Financial Holdings plugs directly into the screener theme as a Nevada community bank that leans on local business and consumer deposits, so its earnings story is closely tied to how short term rates shape funding costs and loan yields.
GBank Financial Holdings runs a Las Vegas based commercial and consumer bank that earns all its US$75 million in revenue from banking services and has a market cap of about US$277 million.
"Although the bank’s net interest margin of 4.03% is positioned at the higher end of peers, the combination of a 50 basis point market rate decrease flowing through a largely repricing loan book and funding costs that remain high may keep net interest income growth constrained if deposit pricing proves slow to reset, which could cap improvement in overall profitability."
The real swing factor for GBank Financial Holdings is how one quiet shift in its funding mix ultimately feeds through to those margins investors watch.
That funding pivot is exactly where the full narrative for GBank Financial Holdings shows whether margin pressure is masking a stronger long term earnings story.

Norwood Financial (NWFL)
Norwood Financial is a classic community bank story for this screener, relying heavily on local deposits to fund a broad mix of loans and fee services that respond directly to where short term rates settle over the next few years.
Norwood Financial, the parent of Wayne Bank, runs a full service regional banking and wealth platform that earns about US$100 million from banking and related financial services and carries a market cap of roughly US$361 million.
"Ongoing repricing of the loan portfolio at higher yields, combined with the 2024 securities repositioning, is expected to continue to push net interest margin toward management’s target and support earnings expansion."
What happens if one key pressure on Norwood Financial’s funding costs shifts faster than expected will be central to how that story plays out.
If that funding shift is what you care about, read the full narrative for Norwood Financial to see whether repricing momentum is quietly accelerating Norwood Financial’s earnings power.

Midland States Bancorp (MSBI)
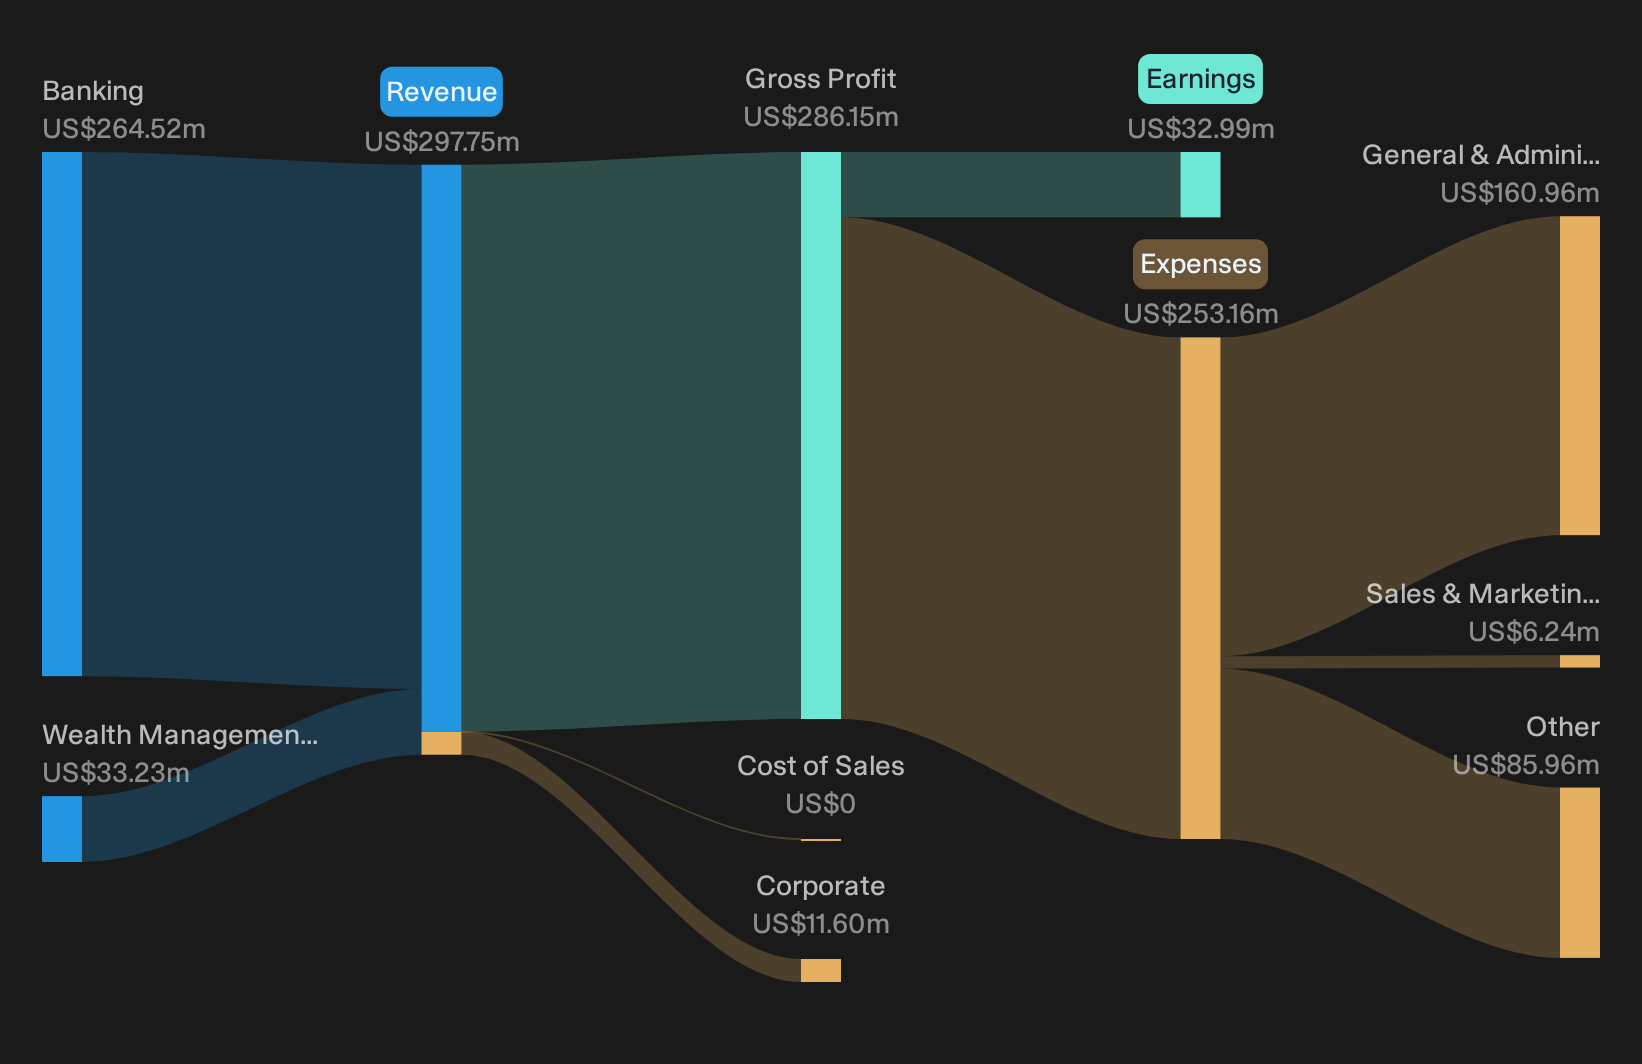
Midland States Bancorp is a regional financial holding company built around a broad retail, business, and municipal deposit base that feeds a traditional lending and wealth management engine. Banking generates about US$265 million of its roughly US$286 million in revenue, with wealth management adding US$33 million, and the group carries a market cap near US$682 million.
Midland States Bancorp fits this rate sensitive bank screen through its traditional deposit funded loan book, where Fed driven pricing directly shapes spread income and earnings. Investors watching a higher for longer policy may see potential benefits if a single pressure point on those funding costs moves in their favor.
If that pressure starts to ease, the Midland States Bancorp financial health report could show whether Midland States Bancorp’s funding profile is quietly setting up a stronger earnings engine.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Breakout stories often fly before the crowd even looks, and under the radar opportunities can be caught slipping or dropping fast, so act now.
- Spot early strength in cash rich businesses by checking the curated list of solid balance sheet and fundamentals (23 results). Do not wait until everyone else notices the balance sheet quality.
- Explore potential income momentum with a focused set of high yield payers using the 7 dividend fortresses. Let others focus on the story after payouts receive more attention.
- Target resilient performers that may be suited for a later breakout phase by reviewing the 31 resilient stocks with low risk scores. Avoid getting caught chasing momentum once risk scores change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com