
How Rapid Heart Attack Test Launch Will Impact bioMérieux (ENXTPA:BIM) Investors
- bioMérieux has launched SPINCHIP®, a compact point-of-care platform in Europe, with its first high-sensitivity cardiac troponin I test, SPINCHIP® hs-cTnI, aimed at faster triage of suspected acute myocardial infarction in emergency settings using a single drop of capillary blood.
- The SPINCHIP® platform extends bioMérieux’s GO•28 plan into point-of-care immunoassays, linking bedside testing to hospital information systems and leveraging the SpinChip Diagnostics acquisition to broaden the long-term product mix beyond traditional laboratory instruments.
- We will now look at how bioMérieux's investment narrative could be influenced by SPINCHIP® bringing 10 minute troponin testing to emergency care.
Scan how SPINCHIP® fits into the broader diagnostics opportunity and line up other potential beneficiaries of this shift with a curated list of 135 healthcare AI stocks.
bioMérieux Investment Narrative Recap
For a shareholder in bioMérieux, the core belief is that this diagnostics group can keep turning a broad test menu and large installed base into steady, higher quality earnings. The business already has €3.99b of revenue and €462.6m of net income, with forecasts pointing to mid single digit top line and mid single digit to high single digit profit growth. SPINCHIP® fits that story as another test platform, but on its own it does not change the near term picture.
The more immediate swing factors still sit around BIOFIRE contract renewals, pricing pressure in U.S. respiratory testing and foreign exchange headwinds. SPINCHIP® could gradually diversify the product mix toward point of care immunoassays. At the same time, execution risk on new platforms now overlaps with existing concerns on U.S. exposure, reimbursement complexity for SPOTFIRE and reliance on higher risk funding sources.
The most relevant recent development alongside SPINCHIP® is the ongoing rollout of BIOFIRE SPOTFIRE, which is already positioned as a point of care PCR system. Together, SPOTFIRE and SPINCHIP® show bioMérieux leaning harder into decentralized testing rather than relying only on central labs, which matters for how you think about future product mix and capital intensity.
These point of care moves link directly to the key catalysts analysts already focus on. Strong SPOTFIRE uptake and cross selling of BIOFIRE non respiratory panels are cited as growth drivers, while SPINCHIP® brings another testing model that could support that narrative if adoption is broad and contract structures prove resilient when older BIOFIRE deals expire and competitors keep pressing on price.
bioMérieux's narrative projects €4.7b revenue and €583.2m earnings by 2029. This aligns with analysts assuming 5.4% yearly revenue growth and an earnings increase of about €120.6m from €462.6m today.
Uncover why bioMérieux's fair value indicates that bioMérieux is in line with its current price.
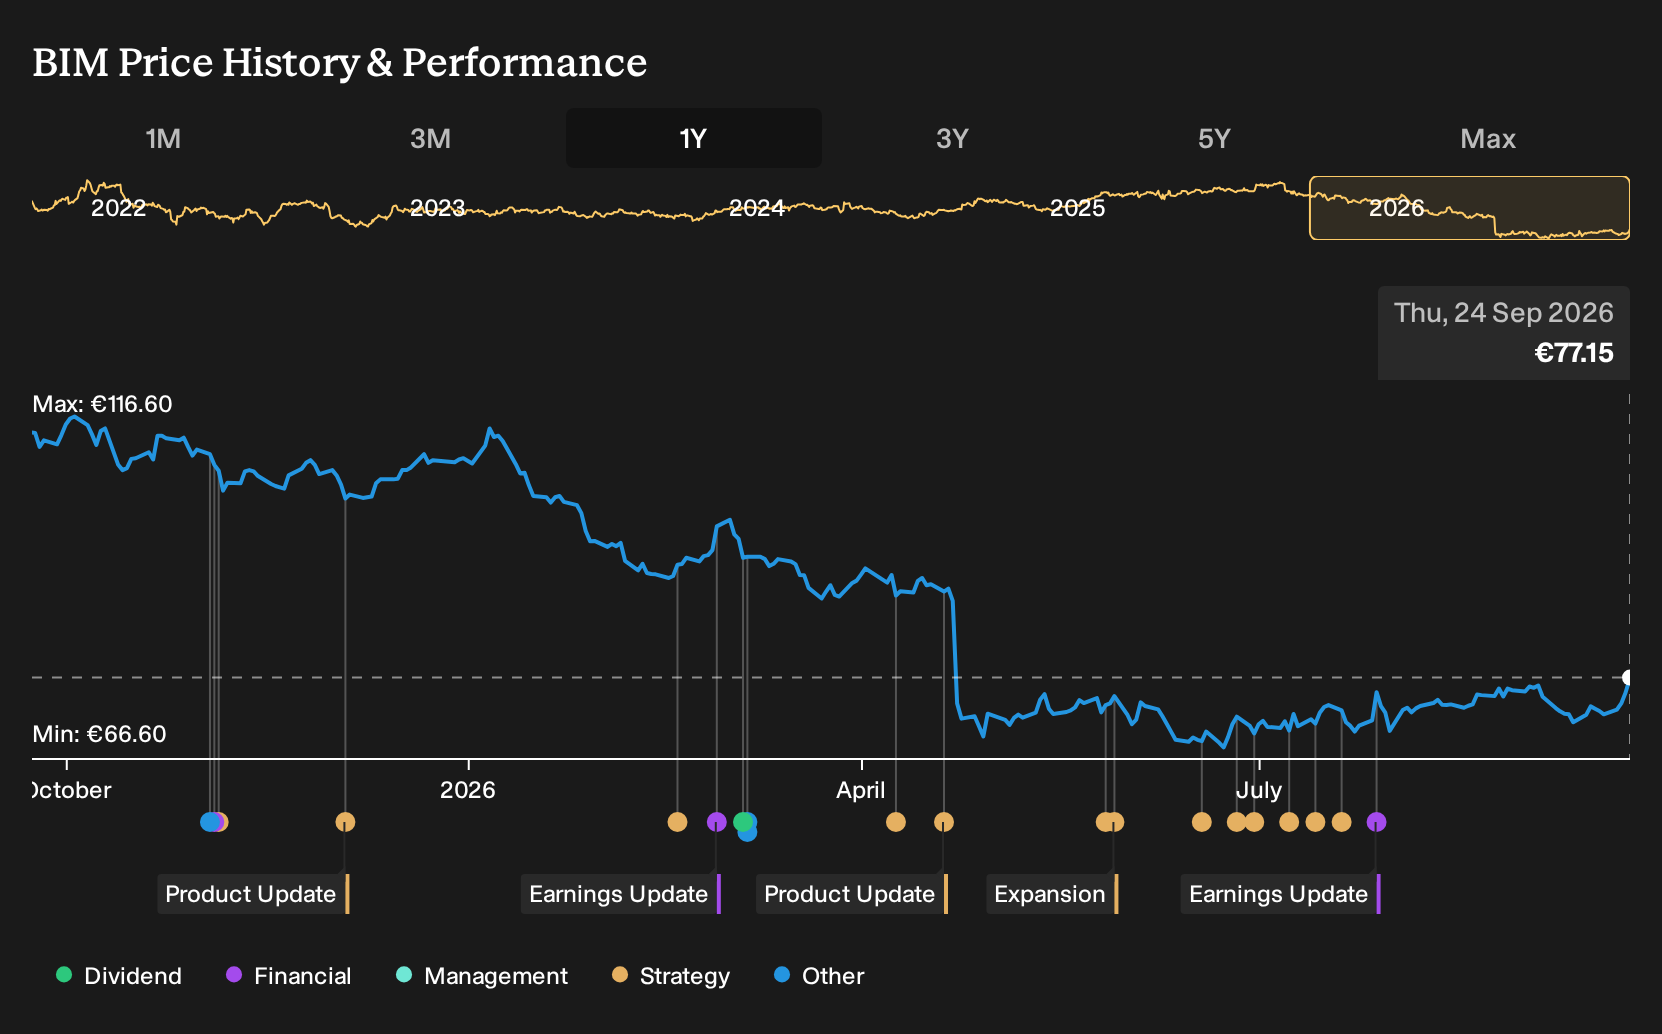
Exploring Other Perspectives
For the most optimistic bioMérieux watchers, the big swing factor is not contract risk but faster growth from point of care. They were already pencilling in revenue of €4.9b and earnings of €648.2m by 2029. A 10 minute SPINCHIP® troponin test could push those expectations higher, lower or simply reshape them. Opinions differ widely, so explore several viewpoints before deciding how this launch fits your own thesis.
Explore 2 other bioMérieux fair value estimates, including one that suggests potential upside of up to 46% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your bioMérieux research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for bioMérieux. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate bioMérieux's overall financial health at a glance.
Looking For More Investment Ideas Beyond bioMérieux?
Once you have a view on bioMérieux, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles. The Simply Wall St Screener lets you do that quickly by filtering for specific traits that match your own approach.
- If capital preservation is front of mind, start by focusing on resilience and financial strength with a curated 230 resilient stocks with low risk scores that may suit a more cautious style.
- For investors hunting for quality at a reasonable entry point, scan a 177 high quality undervalued stocks that combines solid fundamentals with potentially attractive pricing.
- Income focused portfolios can use a 158 dividend fortresses to identify higher yielding alternatives that still clear basic balance sheet checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com