
China Nonferrous Mining (SEHK:1258) Stock May Be Overvalued Against Its Earnings Base
China Nonferrous Mining has delivered very strong shareholder gains over the past few years, which naturally raises a question about what you are paying for its earnings today. The key issue is whether the current share price fairly reflects the profit stream that the business is generating.
- China Nonferrous Mining has returned about 431.1% over 5 years, so a lot of future profit expectations are now embedded in the price and need to be weighed carefully.
- The group’s value story now leans heavily on how efficiently it can turn its mining assets and capital spending into sustainable earnings, since that drives how much profit each Hong Kong dollar of investor capital is really buying.
- The analysts covering China Nonferrous Mining have run their own numbers. See what analysts think China Nonferrous Mining's shares could be worth.
The stock’s next move may depend on whether China Nonferrous Mining’s current earnings justify the valuation that recent price gains have produced.
If you want to pressure test whether China Nonferrous Mining’s 431.1% five year return leaves enough earnings upside on the table, compare its valuation against 177 high quality undervalued stocks
Is China Nonferrous Mining Getting Expensive on Earnings?
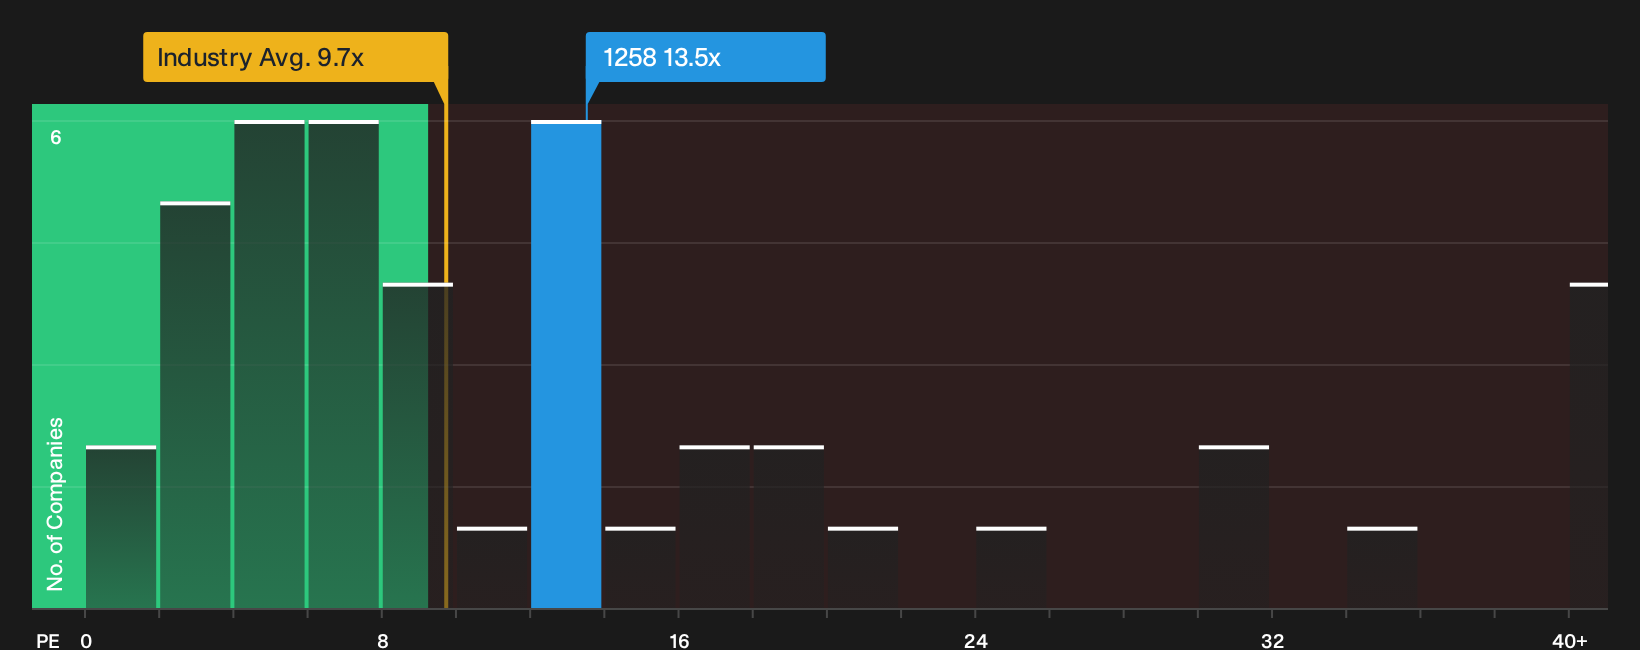
The P/E ratio works well for China Nonferrous Mining because earnings are a central part of how investors frame a mature mining business. Right now the stock trades around 13.5x earnings, which sits above the Metals and Mining industry average of about 9.7x but well below the wider peer group near 30.7x. That mix suggests the market is giving the company a richer tag than the typical miner, while still not pricing it like the more expensive stocks in the sector.
The fair multiple implied by Simply Wall St’s model, which blends China Nonferrous Mining’s growth profile, margins, scale and risk, is lower than the current P/E. On this framework the shares screen as overvalued on earnings, so anyone buying at today’s price is paying a premium and needs to be comfortable that the profit stream can support it. You can see how that premium compares in more detail in. Explore the numbers behind China Nonferrous Mining's P/E valuation.
The China Nonferrous Mining Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where the valuation question for China Nonferrous Mining leaves off, by spelling out what paths for growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each narrative ties a specific mix of potential catalysts and risks to its own fair value estimate, which lets you track over time which storyline lines up most closely with how China Nonferrous Mining’s business actually develops.
A clear, number-driven narrative on China Nonferrous Mining helps pin down what you are really assuming about its growth, margins and execution. Those expectations can then be checked against future results. Putting that view in writing gives you a concrete roadmap to test whether the current valuation still fits the business that actually shows up over time.
Share your own Narrative for China Nonferrous Mining and set out the assumptions behind your valuation.
An unresolved piece of the China Nonferrous Mining puzzle
All the current numbers for China Nonferrous Mining tell one story, but the projections from professional analysts offer a separate lens on where earnings and cash flows might head next. Explore where analysts expect China Nonferrous Mining to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com