
Will Electric Truck Launch Change Volvo Stock Narrative
- AB Volvo and Westport’s joint venture Cespira released technical details for the HPDI 3.0 fuel system, and Volvo Trucks announced a long range heavy electric truck, while Volvo Group advanced plans for a large scale Mariestad energy park with battery storage and an energy solutions test bed.
- Taken together, these steps show AB Volvo pushing deeper into low and zero carbon heavy transport, expanding its addressable market across LNG, bioLNG and battery electric segments, while investing in supporting energy infrastructure.
- We will look at how AB Volvo's investment narrative is influenced by HPDI 3.0 and the push into high capacity electric trucks.
Scan beyond AB Volvo to compare its low and zero carbon freight push with other heavy transport players by reviewing the 39 power grid technology and infrastructure stocks in one place.
AB Volvo Investment Narrative Recap
To own AB Volvo, you need to believe that heavy transport customers will gradually adopt lower carbon trucks and that the group can translate its product pipeline into stable earnings, despite cyclical end markets. The immediate story is still about order trends in core Trucks and Construction Equipment and how volumes absorb fixed costs through the next demand swing.
The latest HPDI 3.0 and long range electric launch do not instantly change that near term catalyst. They mainly sharpen the product offering for when fleets commit more capital to LNG, bioLNG and battery electric platforms. The bigger near term risk remains weaker demand in key regions, tariff pressure and any further execution hiccups in electrification that drag on margins or cash generation.
Among the announcements, the long range Volvo Trucks FH Electric rigid combination up to 80 tonnes looks most relevant for AB Volvo’s nearer catalysts. It directly addresses heavier long haul and regional assignments where adoption has been slower, and it gives fleet buyers a clearer option where range and payload are non negotiable.
This product sits alongside existing electric and combustion platforms and can support the narrative that AB Volvo is ready if zero emission uptake accelerates from here. It also raises the bar for execution risk. The group now has to industrialise high capacity battery trucks, support Megawatt Charging System infrastructure with partners and manage upfront costs while core diesel and gas volumes remain exposed to cycles and trade barriers.
AB Volvo's current earnings sit at SEK 35.8b with a consensus outlook of SEK 56.9b by 2029, which implies an increase of about SEK 21b in profit, based on 6.9% yearly revenue growth and projected 2029 revenues of SEK 576.0b.
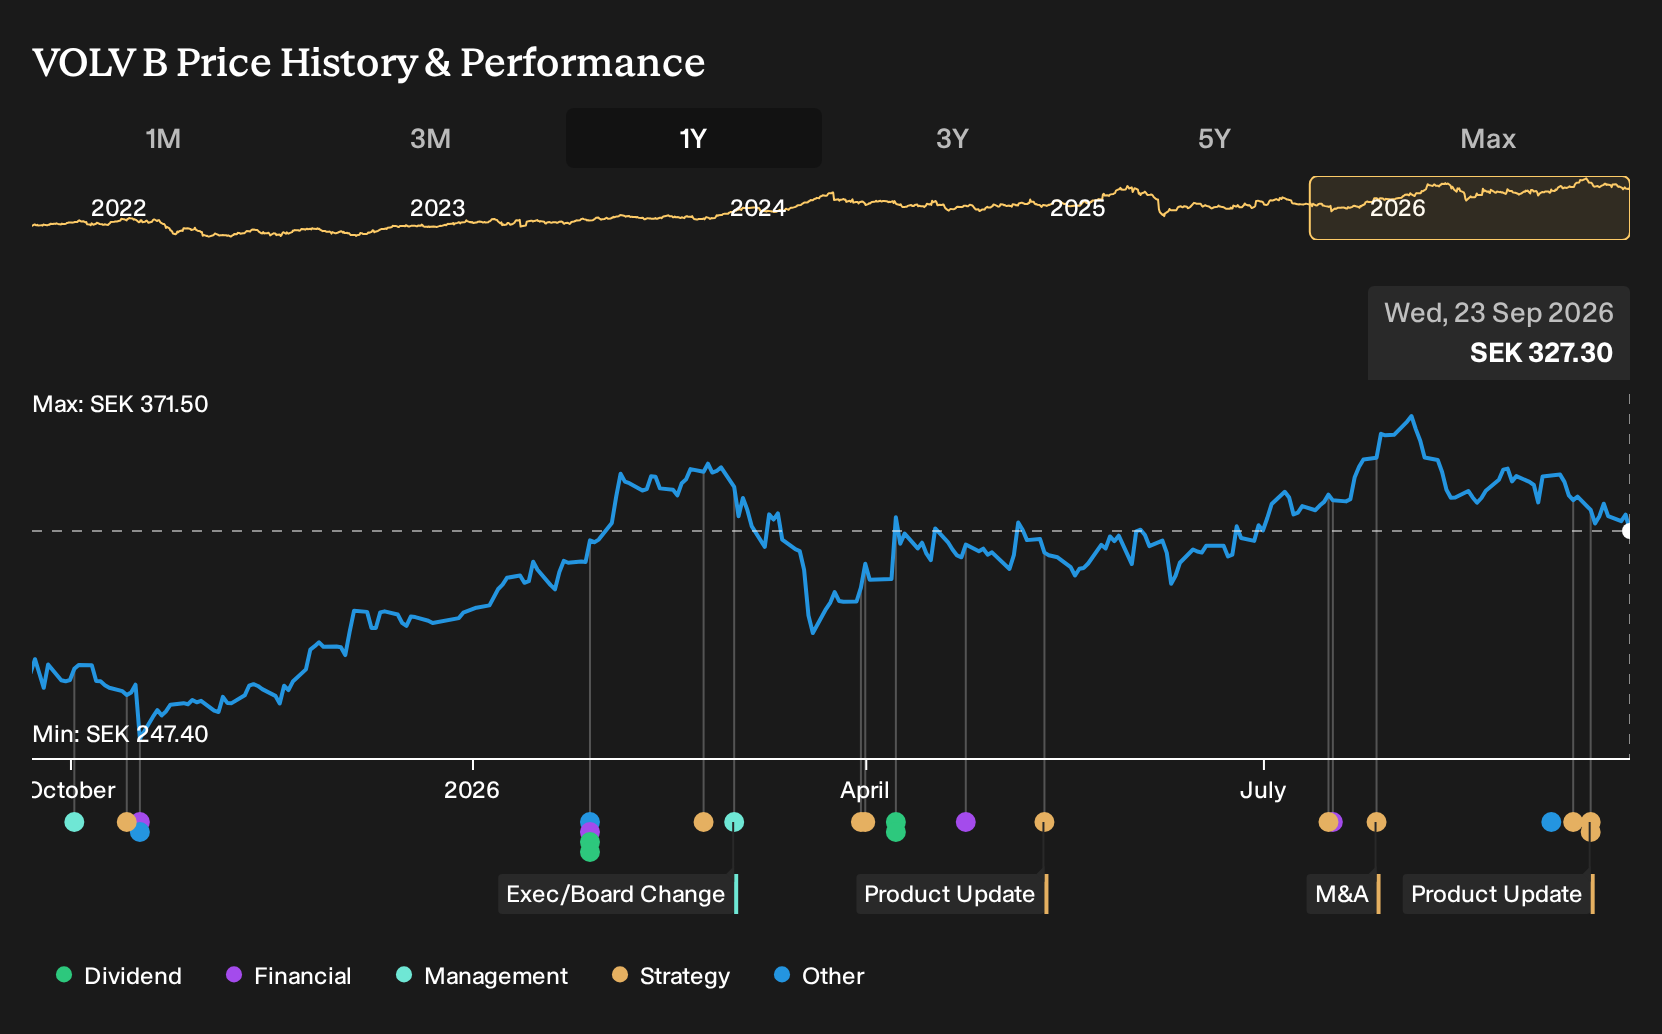
Uncover why AB Volvo's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate read on AB Volvo focuses on regulatory and carbon cost risk rather than new products. The most cautious analysts were only pencilling in revenue of about SEK 528.8b and earnings of roughly SEK 47.8b by 2029 before this news. That is a meaningfully lower earnings path. These views could shift as HPDI 3.0 and the 80 tonne electric truck are fully factored in, so it is worth comparing several narratives before deciding how you see the story playing out.
Explore 3 other AB Volvo fair value estimates, including one that suggests it could be worth just SEK356.12.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your AB Volvo research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AB Volvo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AB Volvo's overall financial health at a glance.
Looking for more AB Volvo sized ideas?
If the AB Volvo story has sharpened your thinking on low and zero carbon freight, it can help to widen the lens and see how other businesses stack up on valuation strength, balance sheet quality, and income potential.
- For investors hunting for mispriced opportunities with solid fundamentals, start with a focused set of 178 high quality undervalued stocks that may warrant a place on your watchlist.
- If capital preservation and financial resilience sit higher on your checklist, scan through a 229 resilient stocks with low risk scores that could help you avoid unnecessary shocks.
- For those who want stable income alongside solid financial footing, filter for a 158 dividend fortresses that already pass tough balance sheet and payout quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com