
Should Gold Reserve Buying Require Action From Agnico Eagle Stock Investors?
- Large investors have recently increased their use of gold as a reserve asset as US national debt moved above US$40b, drawing fresh attention to established, lower cost producers such as Agnico Eagle Mines.
- Agnico Eagle Mines is being grouped with other heavyweight gold miners that run relatively low cost operations, which may be relevant for how resilient cash generation is if more capital shifts toward the metal.
- This article will explore how Agnico Eagle Mines' investment narrative intersects with rising large investor interest in gold as a reserve asset.
Scan how large reserve buyers are repositioning around gold by comparing Agnico Eagle Mines with peers in the curated list of 36 elite gold producer stocks.
Agnico Eagle Mines Investment Narrative Recap
Owning Agnico Eagle Mines means believing the miner can keep turning a large, diversified asset base into steady cash, even as some projects hit friction. The company recently reported revenue of about US$14.5b and net income of roughly US$5.9b, with net profit margins around 40%, so the core engine is productive.
The key near term swing factor is how well operations absorb known setbacks such as the Barnat pit issues while keeping costs low. The biggest risk is further site specific disruptions or safety incidents that cut volumes, increase regulatory pressure and make already expected revenue and earnings declines harder to manage.
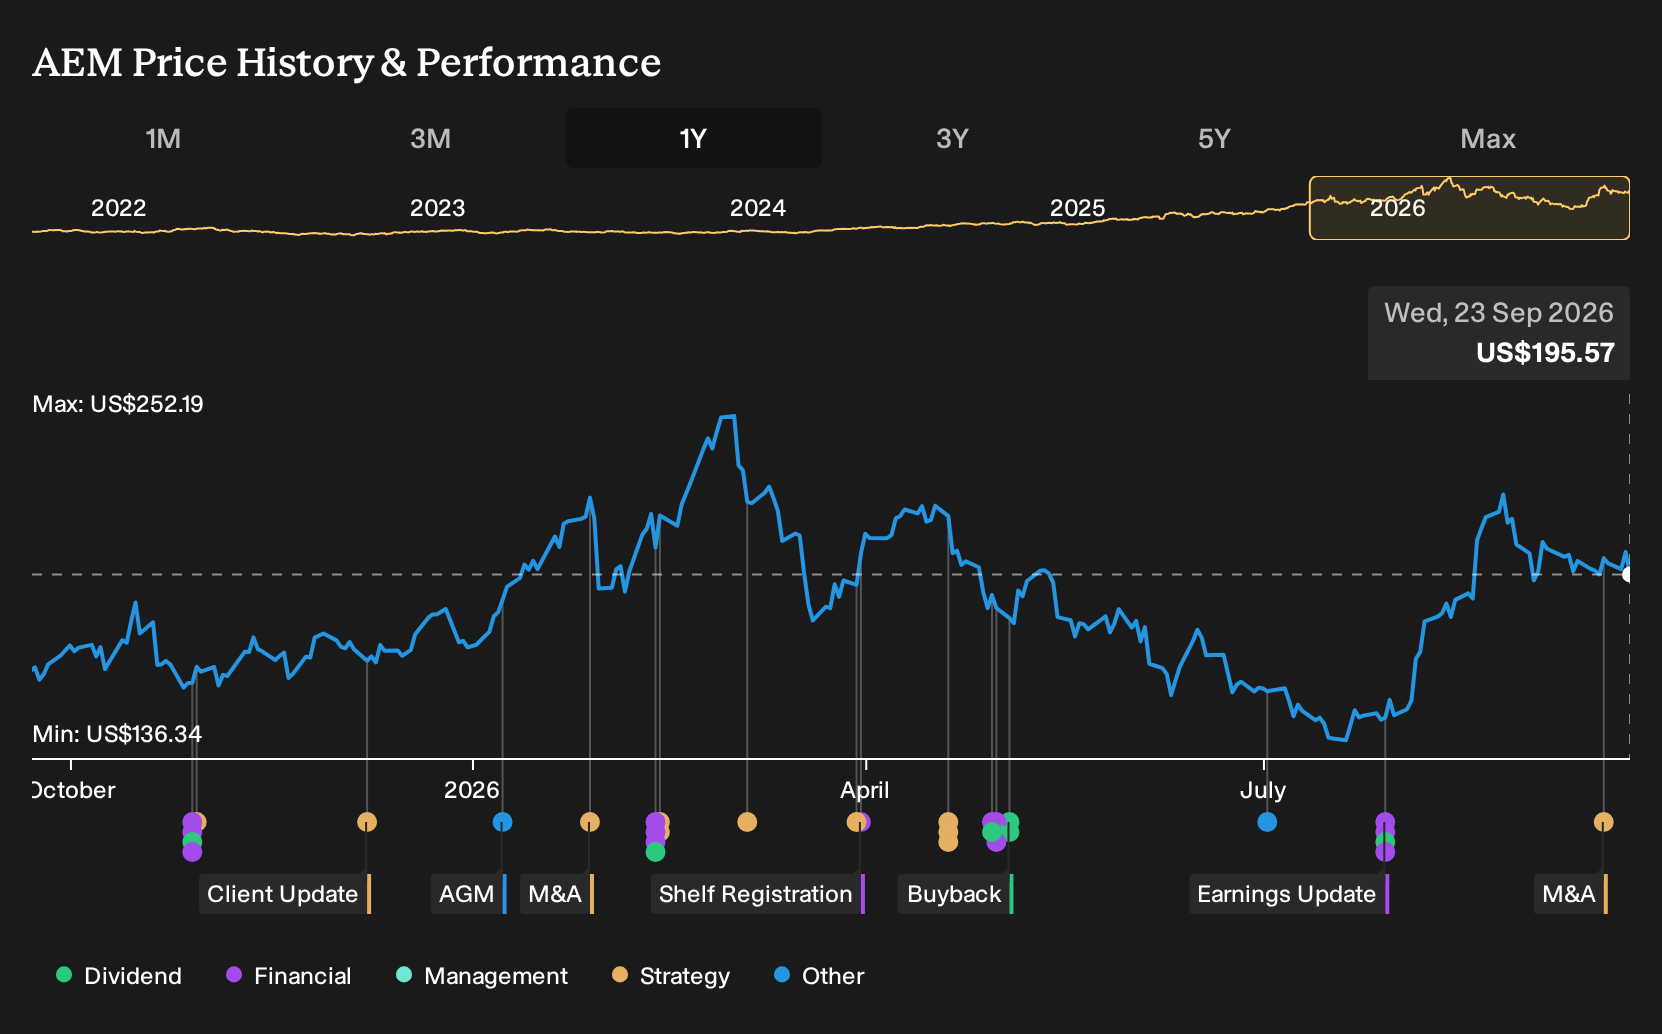
With no fresh operational announcements directly tied to the latest reserve buying interest in gold, the most relevant context remains Agnico Eagle Mines' focus on free cash flow and project execution. Management recently highlighted about US$1.3b of free cash flow in Q2 2026, and all in sustaining costs sitting hundreds of dollars per ounce below the industry average.
That cost profile matters if large investors continue to lean on gold as a reserve asset, because lower costs can give the business more room if prices soften or production at sites like Barnat is constrained. Progress on projects such as Detour underground, Canadian Malartic Shaft 2, Upper Beaver, Hope Bay and San Nicolas is central to offsetting expected declines in revenue and earnings over the next few years.
Agnico Eagle Mines' current analyst narrative points to revenue of about US$15.1b and earnings of roughly US$6.1b by 2029, based on expectations for 1.3% yearly revenue growth and an earnings increase of about US$0.2b from roughly US$5.9b today.
Uncover why Agnico Eagle Mines' fair value indicates a 10% potential upside to its current price, which could narrow quickly if sentiment shifts toward low cost gold producers.
Exploring Other Perspectives
Some of the most optimistic analysts frame US debt driven interest in gold as a potential accelerator for Agnico Eagle Mines. They were already pencilling in revenue of about US$19.1b and earnings of roughly US$8.3b by 2029. You can now ask whether those pre news estimates look too cautious or too aggressive.
Explore 6 other Agnico Eagle Mines fair value estimates, including one that suggests as much as 63260% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Agnico Eagle Mines research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agnico Eagle Mines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agnico Eagle Mines' overall financial health at a glance.
Looking For More Ideas Beyond Agnico Eagle Mines?
If the Agnico Eagle Mines story has you thinking more broadly about where to put fresh capital, it can help to scan a wider field of stocks that share some of the qualities you care about, whether that is value, resilience or future potential.
- For investors who want potential value on their side, start with companies that screen as attractively priced on both quality and fundamentals through the 30 high quality undervalued stocks.
- If capital protection and balance sheet strength matter most to you, focus on businesses that clear strict debt and liquidity checks using the list of solid balance sheet and fundamentals (23 results).
- Those looking for income ideas can filter for dependable payouts and higher yields by reviewing the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com