
How Value Focus Has Changed The Investment Story For ARMOUR Residential REIT Stock (ARR)
- Recent analyst coverage has focused on ARMOUR Residential REIT’s fundamentals, pointing to Agency MBS exposure, earnings outlook and current valuation metrics such as its Forward P/E and P/B ratios.
- An interesting twist is that analysts are framing these low valuation multiples as a reflection of perceived value, not just risk, given ARMOUR Residential REIT’s income focused Agency MBS portfolio.
- This article will examine how ARMOUR Residential REIT's investment narrative is influenced by analyst focus on its low Forward P/E and P/B ratios.
Scan beyond ARMOUR Residential REIT and compare its value profile with a curated set of income focused opportunities in our 30 high quality undervalued stocks.
ARMOUR Residential REIT Investment Narrative Recap
To hold ARMOUR Residential REIT, you need to believe its Agency MBS focus can keep generating attractive income even as earnings and revenue are forecast to decline over the next three years. The thesis leans heavily on funding costs staying manageable, hedging remaining effective and book value not being eroded by rate or spread shocks.
The most important near term swing factor is the interest rate path and its impact on repo costs, MBS spreads and prepayment speeds. The biggest operational risk is the combination of high leverage and funding that depends entirely on higher risk external borrowing, which can amplify any stress in funding markets.
Recent attention on ARMOUR Residential REIT has highlighted its low P/E and P/B ratios, its Value grade of A and a Zacks Rank #2 rating. That combination reinforces the current narrative that the stock screens as undervalued relative to peers and the broader US market, especially given it became profitable this year with what is described as high quality earnings.
For your thesis, that matters because valuation can act as a cushion if rate volatility, prepayments or spread moves pressure earnings. At the same time, you still need to weigh ongoing risks flagged around dividend coverage, insider selling, shareholder dilution and forecasts that earnings and revenue may decline, even if the present multiples look appealing on traditional value metrics.
ARMOUR Residential REIT’s narrative projects US$825.8 million in revenue and US$1.4b in earnings by 2028, based on analyst assumptions of 91.9% yearly revenue growth and an increase in earnings of about US$1.35b from US$52.5 million today.
Uncover why ARMOUR Residential REIT's fair value indicates a 16% potential upside to its current price before the discount closes.
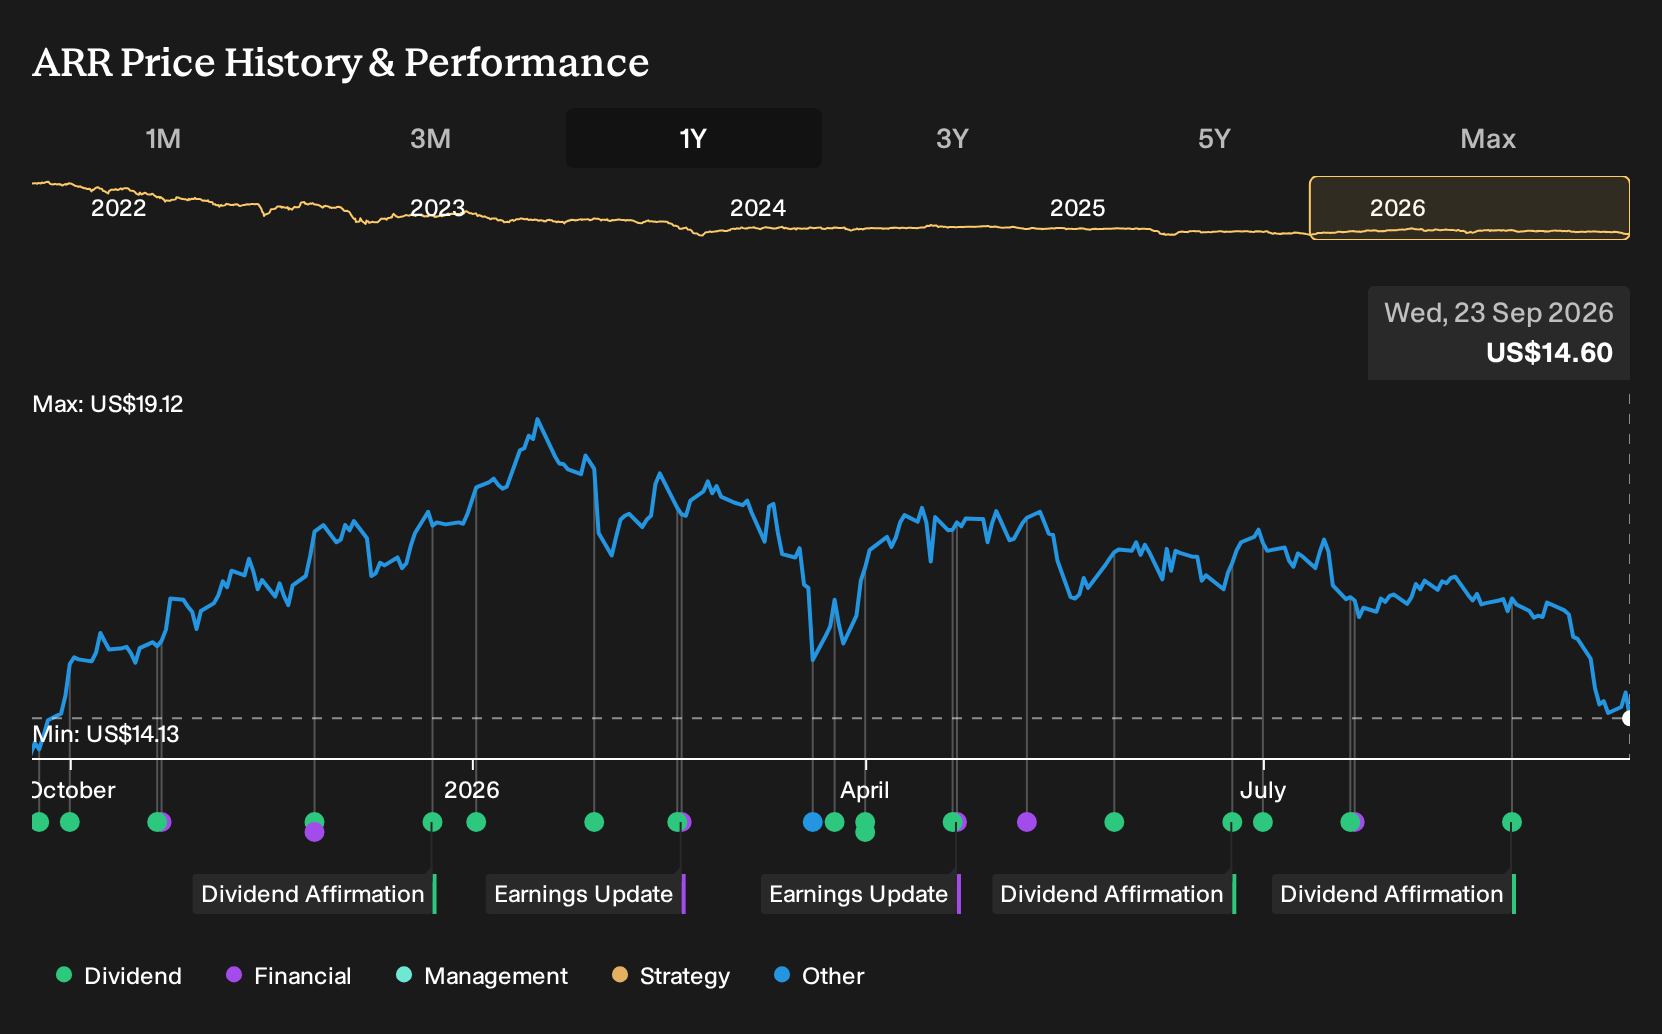
Exploring Other Perspectives
Simply Wall St Community members have only submitted 2 fair value estimates for ARMOUR Residential REIT so far, clustering tightly between US$17 and US$18.38. That narrow spread contrasts with the wide range of risks around rates, MBS spreads and leverage, so you should expect strong disagreement and explore multiple viewpoints.
Explore another ARMOUR Residential REIT fair value estimate, including one that suggests as much as 26% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ARMOUR Residential REIT research is our analysis highlighting 4 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for ARMOUR Residential REIT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ARMOUR Residential REIT's overall financial health at a glance.
Looking For More Investment Ideas Beyond ARMOUR Residential REIT?
If ARMOUR Residential REIT has sharpened your focus on valuation, income and balance sheet strength, it can be useful to line it up against a broader watchlist built from different angles on quality and risk.
- For investors who want potential upside without ignoring balance sheets, start with a curated 16 high quality undiscovered gems that match strong fundamentals with quieter market attention.
- If capital preservation and a smoother ride matter most to you, filter candidates using a 31 resilient stocks with low risk scores that screens for resilience first and returns second.
- When you care about financial resilience backing every dividend or buyback decision, benchmark ARMOUR Residential REIT against a list of solid balance sheet and fundamentals (23 results) that prioritises sturdy fundamentals and clean leverage profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com