
Is Active Group Shake Up Altering The Investment Case For Wolverine World Wide (WWW)?
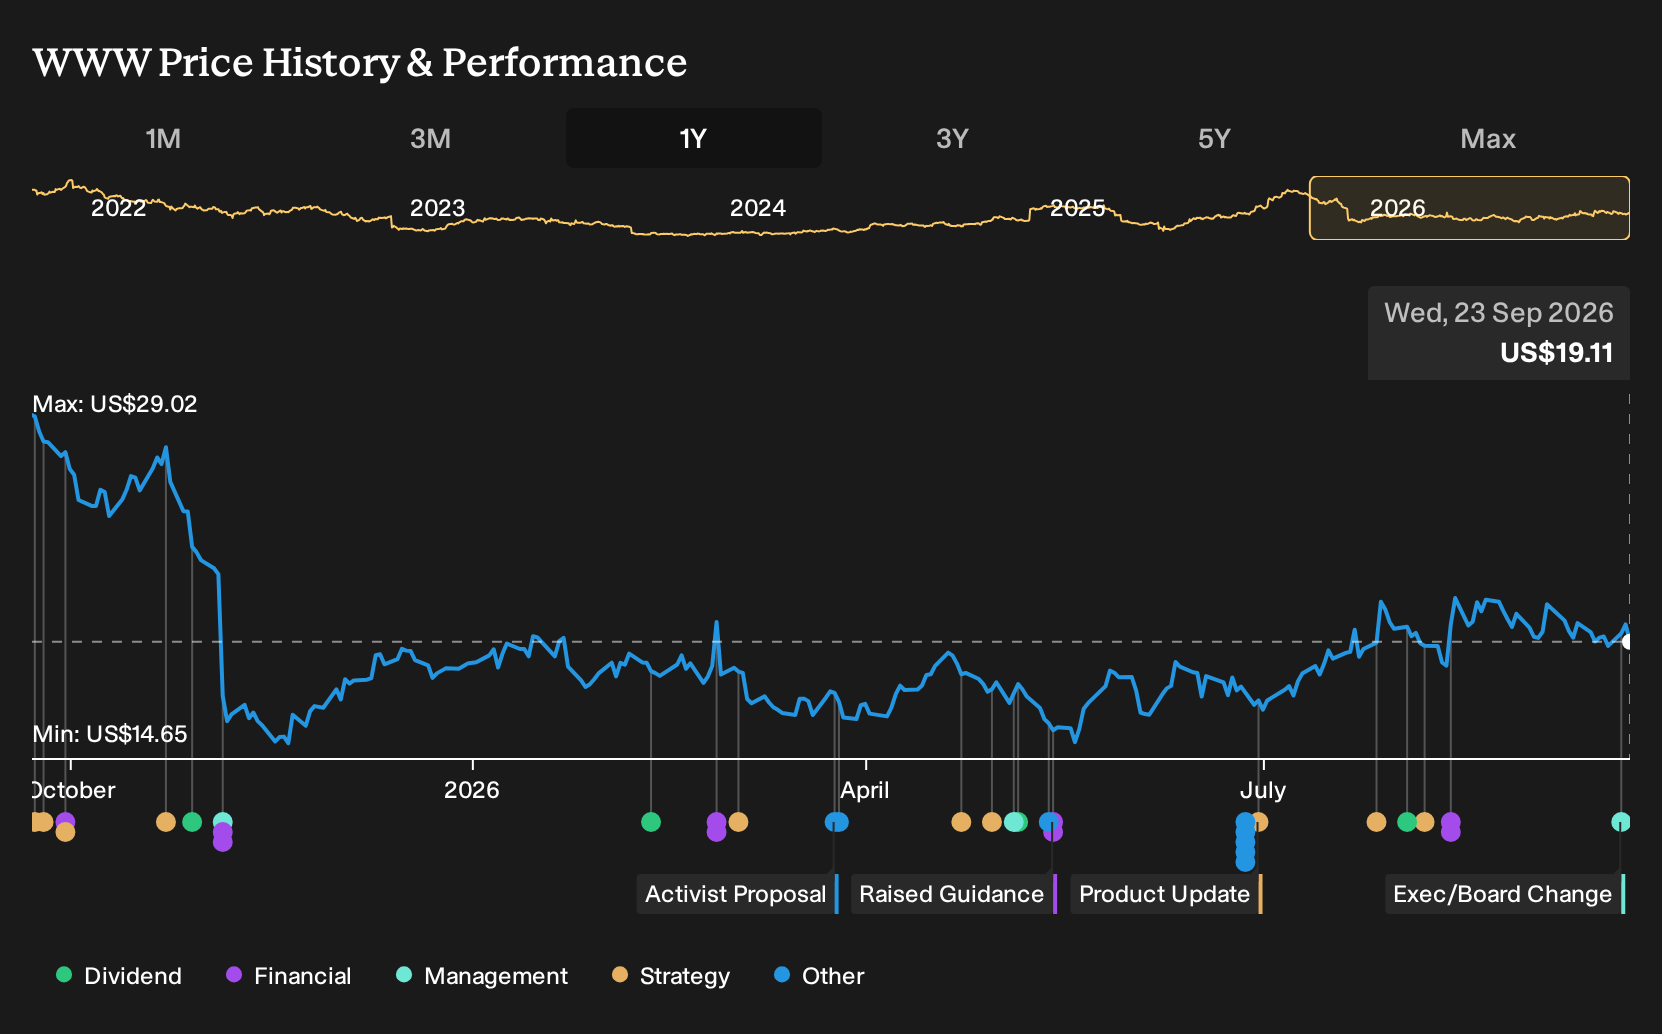
- Wolverine World Wide has removed the President, Active Group role, with Susie Kuhn exiting on 21 September 2026 and her responsibilities reassigned across the wider business.
- The leadership reshuffle pushes Active Group brand heads to report directly to CEO Chris Hufnagel, tightening oversight of a division tied to the company’s recent sales turnaround efforts.
- We will examine how Wolverine World Wide’s investment narrative is influenced by this consolidation of Active Group leadership under the CEO.
Scan how other footwear and apparel players are reshaping leadership and pursuing turnarounds with our curated 16 high quality undiscovered gems alongside Wolverine World Wide.
Wolverine World Wide Investment Narrative Recap
To own Wolverine World Wide, you need to be comfortable with a footwear group still heavily tied to wholesale, while leaning on Active Group brands like Merrell and Saucony for growth, and carrying a meaningful debt load. The key near term focus is whether recent sales improvement can hold as distribution expansion normalises and marketing spend stays elevated.
The exit of the President, Active Group, with brand leaders now reporting directly to CEO Chris Hufnagel, does not obviously change those near term drivers. Execution risk around coordination and speed of decision making could tick up, although the most important swing factors still appear to be rooted in demand trends, wholesale partner health and cost discipline.
Recent commentary around Wolverine World Wide has highlighted international expansion, digital growth and supply chain work as the main levers for earnings and margin quality. That context matters here. The leadership reshuffle lands on top of a business already trying to balance higher marketing spend and a pivot to more direct channels against a still dominant wholesale base.
Because no new operational guidance accompanied this leadership change, the most relevant lens is whether Active Group brands can maintain product momentum while reporting lines tighten around the CEO. If execution stays smooth, investors are likely to keep watching the same core catalysts, such as progress in DTC, inventory management and any improvement from lagging legacy brands.
What The New Leadership Setup Means For The Wolverine World Wide Forecasts
The analyst playbook around Wolverine World Wide is fairly clear. Forecasts lean on Active Group brands to support revenue and margin assumptions that already bake in meaningful improvement, while the leadership reshuffle simply concentrates more of that pressure on the CEO seat.
On the top line, the consensus view points to revenue expanding at 5.5% per year over the next 3 years. That growth rate underpins a longer range projection that by 2029, Wolverine World Wide could be generating about US$2.3b in sales, with profit margins rising from 5.4% today to 8.0% in the same time frame.
Earnings expectations indicate how much performance is already priced into the story. Analysts currently model profit of US$105.6m stepping up to US$183.1m by 2029, with earnings per share moving to US$2.25. That is an increase of about US$77.5m in earnings, and it assumes only a modest 0.12% yearly increase in the share count over the next 3 years.
Valuation work in the consensus research links those forecasts to a P/E reset rather than multiple expansion. To line up with the current analyst price targets, investors would need to be comfortable with Wolverine World Wide trading on a P/E of 14.4x those 2029 earnings, compared with 15.0x today and the US Luxury sector at 15.6x. At a recent share price of US$19.29, the average target of US$24.30 implies pricing that is 20.6% higher. The spread between US$19.00 and US$31.00 highlights a wide range of opinion on how cleanly this turnaround can be executed.
Leadership consolidation inside the Active Group now sits alongside these numbers rather than replacing them. For you as an investor, the practical question is whether bringing Merrell, Saucony and the other performance brands directly under Chris Hufnagel increases the odds that Wolverine World Wide can reach those margin and earnings targets without overreliance on wholesale or a sustained step up in discounting.
Wolverine World Wide's narrative projects US$2.3b revenue and US$183.1m earnings by 2029. This rests on 5.5% yearly revenue growth and an earnings increase of about US$77.5m from US$105.6m today.
Uncover why Wolverine World Wide's fair value indicates a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on margin risk rather than growth. The most bearish analysts already saw higher supply chain and tariff costs as a headwind and were projecting revenue of about US$2.3b and earnings of roughly US$181.1m by 2029. With Wolverine World Wide reshaping leadership, those pre news assumptions may shift. Consider the spread in expectations as a prompt to explore both optimistic and cautious views before evaluating how this development aligns with your own portfolio goals.
Explore 3 other Wolverine World Wide fair value estimates, including one that suggests it could be worth just $22.75.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Wolverine World Wide research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wolverine World Wide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wolverine World Wide's overall financial health at a glance.
Looking For More Investment Ideas Beyond Wolverine World Wide?
If this Wolverine World Wide update has sharpened your thinking but you are not ready to stop at a single ticker, it can help to scan a broader watchlist built around clear financial traits instead of headlines.
- For investors who care most about quality at a reasonable price, you can review a carefully filtered group of companies through the 30 high quality undervalued stocks and see which ones line up with your own expectations.
- If resilience and balance sheet strength are higher on your checklist, take a closer look at the list of solid balance sheet and fundamentals (23 results) to compare businesses with healthier financial footing.
- For readers who want to cast a wider net across underfollowed opportunities, you can scan the 16 high quality undiscovered gems and build a list to research next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com