
Minerals 260 (ASX:MI6), What Is Behind The Fresh Attention?
Minerals 260 (ASX:MI6) moved into focus after filing follow on equity offerings worth more than A$200 million, with fresh ordinary shares issued at A$0.88. This could potentially reshape supply and funding capacity.
Minerals 260 has already seen brisk trading interest this year, with the share price up 116.28% year to date and a 1 year total shareholder return of 332.56%. The recent 1 day share price decline of 1.59% and modest 1 month gain of 1.09% suggest some near term consolidation as the capital raises and project updates are absorbed.
Spot opportunities across the broader materials space by scanning our hand picked 36 best rare earth metal stocks alongside Minerals 260's latest capital raise and project updates.Minerals 260 now trades around A$0.93 while analyst estimates and intrinsic value models sit materially higher. Does that gap reflect mispricing, or a fair discount for the fresh A$0.88 equity overhang and project risk?
Preferred Price-to-Book of 10.6x for Minerals 260: Is it justified?
Minerals 260 is being valued on a very rich footing, with a price-to-book multiple of 10.6x against a last close of A$0.93. That premium is hard to ignore when the wider Australian Metals and Mining group sits on an average P/B of 1.9x and close peers cluster around 8.5x.
The P/B ratio compares the market value of the equity to the accounting value of net assets. For a minerals explorer with no meaningful revenue and current losses, investors are effectively paying well above book value for future project potential at Bullabulling, Moora and other targets rather than for current cash generation.
That kind of mark up indicates that the market is baking in strong expectations for future progress, even though Minerals 260 is currently unprofitable, reports a return on equity that is in decline at 16.74%, and is forecast to have no revenue next year. Against that backdrop, a double digit P/B leaves limited room for disappointment if timelines, funding costs, or project outcomes vary from expectations.
Set against the sector, the gap is stark. The 10.6x P/B is more than 5x the broader Australian Metals and Mining average of 1.9x, and it also sits above the 8.5x peer group average. On this preferred multiple, the stock screens as expensive rather than cheap.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 10.6x (OVERVALUED).
Still, any delay or disappointment at Bullabulling or Moora, or further equity raisings at a discount, could quickly pressure the Minerals 260 premium story.
Find out about the key risks to this Minerals 260 narrative.
Another View on Minerals 260's Valuation
The high P/B ratio paints Minerals 260 as expensive, yet the SWS DCF model points the other way. At A$0.93, the stock trades against an estimated future cash flow value of A$1.60, which frames it as undervalued on that metric. Which signal is more informative?
Look into how the SWS DCF model arrives at its fair value.
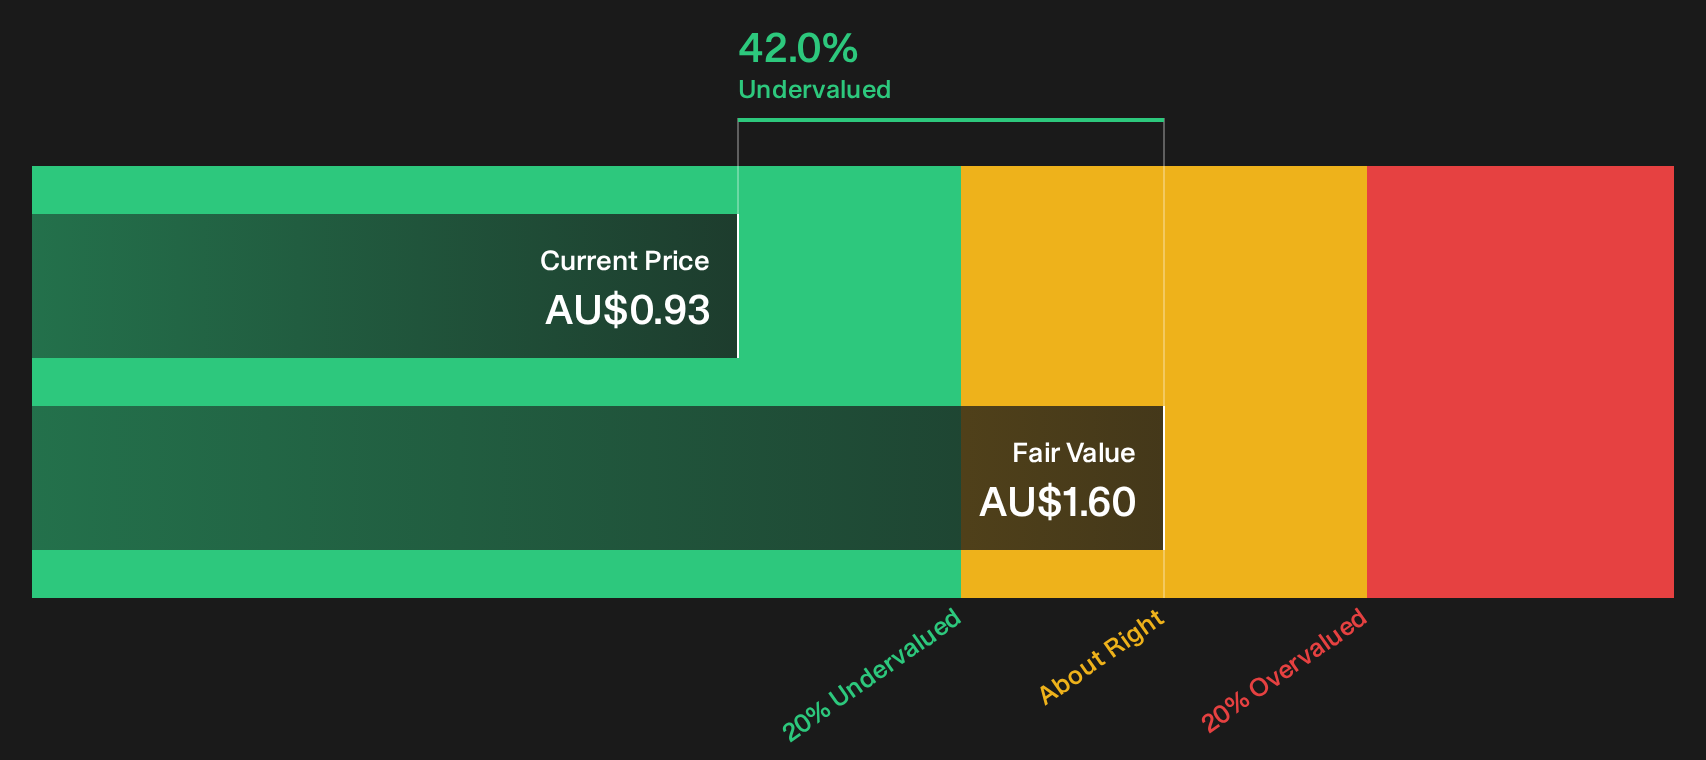
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Minerals 260 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big valuation swings around Minerals 260 can feel confusing, so move quickly, check the underlying risk and reward data, and then decide what story you believe by reviewing the 3 key rewards and 1 important warning sign
Looking for more Minerals 260 style investment ideas?
If Minerals 260 has sharpened your focus on valuation and risk, do not stop here. Broader opportunities are only one smart screen away.
- Zero in on quality potential bargains before the crowd by running the 6 high quality undervalued stocks and lining them up against your own return and risk expectations.
- Strengthen your downside protection by scanning a 7 resilient stocks with low risk scores and checking which businesses better match your comfort with volatility.
- Hunt for future market leaders early by working through a 16 high quality undiscovered gems and shortlisting ideas for your next round of research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com