
How Strong Quarterly Results Will Impact CTS (CTS) Stock
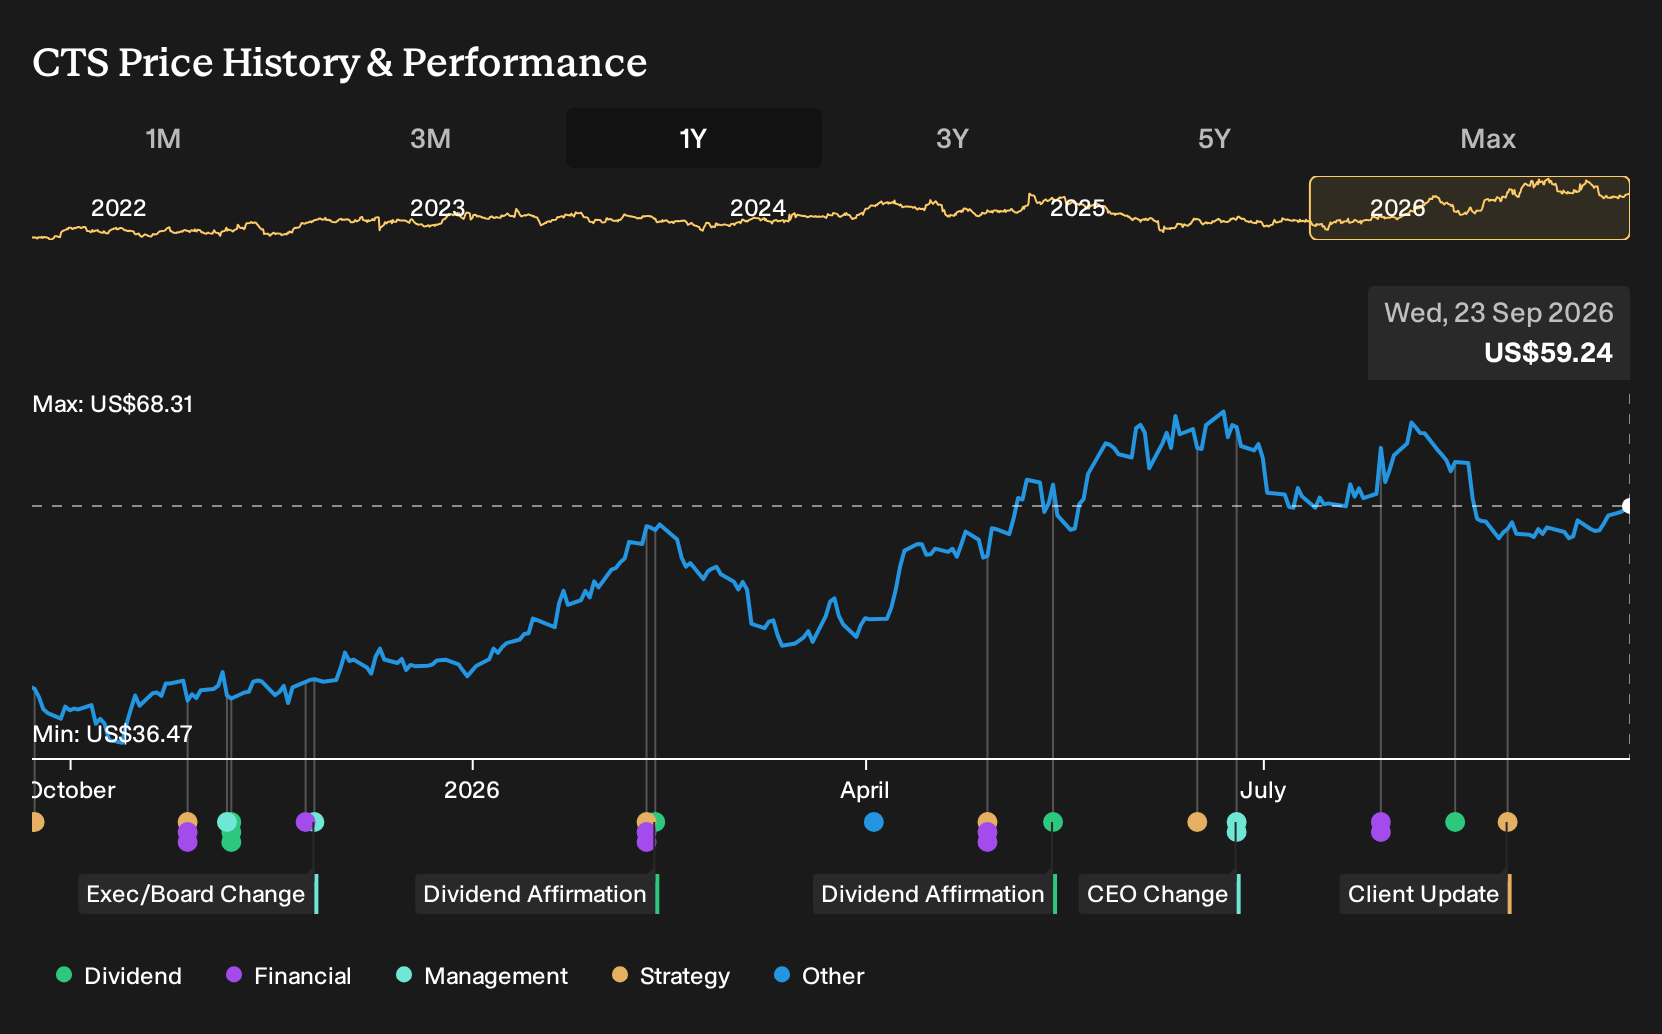
- CTS Corporation recently reported strong quarterly results, with improving demand across its industrial and transportation markets and continued focus on operational execution.
- The business is emphasizing disciplined capital allocation and margin improvement, which suggests management is treating CTS as a long-term compounding platform rather than a short-cycle supplier.
- We will now assess how CTS's stronger quarterly execution may influence the existing investment narrative around diversification and margin expansion.
Scan other industrial compounders that are moving on execution and margin potential with the hand picked 16 high quality undiscovered gems that echo the CTS playbook of diversification and disciplined capital allocation.
CTS Investment Narrative Recap
An investor in CTS needs to believe the business can keep shifting mix toward higher margin industrial, medical, aerospace, and defense work while managing lingering softness in transportation. The recent quarter supports that idea by pairing better demand with solid cost control. The most immediate catalyst remains continued margin progress as product mix and operational execution improve.
The biggest near term risk still sits in transportation exposure and broader trade and tariff pressure. Recent strength does not remove the possibility of weaker orders from China related auto customers or production cuts. Uneven medical demand and lumpier U.S. government funding could also cap how smooth that margin story feels.
Recent quarterly results are the key operational update for CTS. Stronger earnings, supported by improving demand across industrial and transportation markets, directly link to the margin expansion and capital allocation narrative many investors already track. The report provides more evidence that management can execute on cost and mix, at least in the current backdrop.
That same update also highlights where things can still break. Transportation remains sensitive to tariffs and production volumes. Medical and government related work can be choppy. For investors watching catalysts, future quarters will likely be judged on the repeatability of current margins, the pace of diversification wins, and how consistently CTS converts its backlog into high quality earnings.
CTS' current analyst narrative points to forecast revenue of US$653.5 million and earnings of US$98.3 million by 2029. That framework assumes revenue growth of 5.0% per year and an earnings increase of roughly US$28.5 million from current earnings of US$69.8 million.
Uncover why CTS' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$66 and about US$82.5, which already shows how far opinions on CTS can spread. Those views sit alongside real execution risks in transportation and tariffs, as well as potential catalysts from automation, electrification, and higher margin sensing and connectivity work. Expect disagreement and explore the full set of community viewpoints before forming a stance.
Explore another CTS fair value estimate, including one that suggests it could be worth just $66.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CTS research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for CTS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CTS' overall financial health at a glance.
Looking For More Ideas Beyond CTS?
If CTS has sharpened your focus on quality, earnings power, and disciplined capital allocation, it can be useful to widen the lens and scan other businesses with similar traits using the Simply Wall St Screener.
- For investors who want potential mispricing combined with robust fundamentals, consider a curated set of 30 high quality undervalued stocks that may offer stronger quality than their current share prices imply.
- If balance sheet strength and durability come first in your process, filter for a list of solid balance sheet and fundamentals (23 results) that can help you focus on financial resilience before anything else.
- For income focused portfolios that still care about fundamentals, zero in on 7 dividend fortresses that pair higher yields with a framework for assessing sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com