
What Is Drawing Attention To Chevron (CVX) Now?
Chevron (CVX) just told investors it plans to lift exploration spending by more than 50% next year, aiming for about 20 new exploration wells and wider frontier basin exposure.
Chevron shares have had a strong run, with a 90 day share price return of 19.32% and a year to date share price gain of 31.82%. The 5 year total shareholder return of 143.03% shows how much long term holders have benefited, as recent exploration and capital allocation headlines keep attention on the stock.
Scan beyond Chevron and compare its exploration push with other integrated energy groups by reviewing the hand picked 39 power grid technology and infrastructure stocks in this part of the sector.
After a near 32% year to date climb and a last close of US$205.51, Chevron now trades only about 8% below the average analyst target, while one intrinsic estimate implies a roughly 41% gap. Which reference point really anchors fair value next?
Most Popular Narrative: 8% Undervalued
Chevron's most followed valuation storyline pegs fair value at about $223 a share, which sits above the recent $205.51 close and leans on long term production targets and cost programs to justify that gap.
Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel, which supports future revenue and free cash flow.
See why 442 investors see Chevron as 8% undervalued.
Result: Fair Value of $222.67 (UNDERVALUED)
Still, Chevron’s story could look very different if long term energy demand tilts away from hydrocarbons faster than expected or if investors stop paying a premium P/E multiple.
Find out about the key risks to this Chevron narrative.
Another View: Chevron Through The Earnings Lens
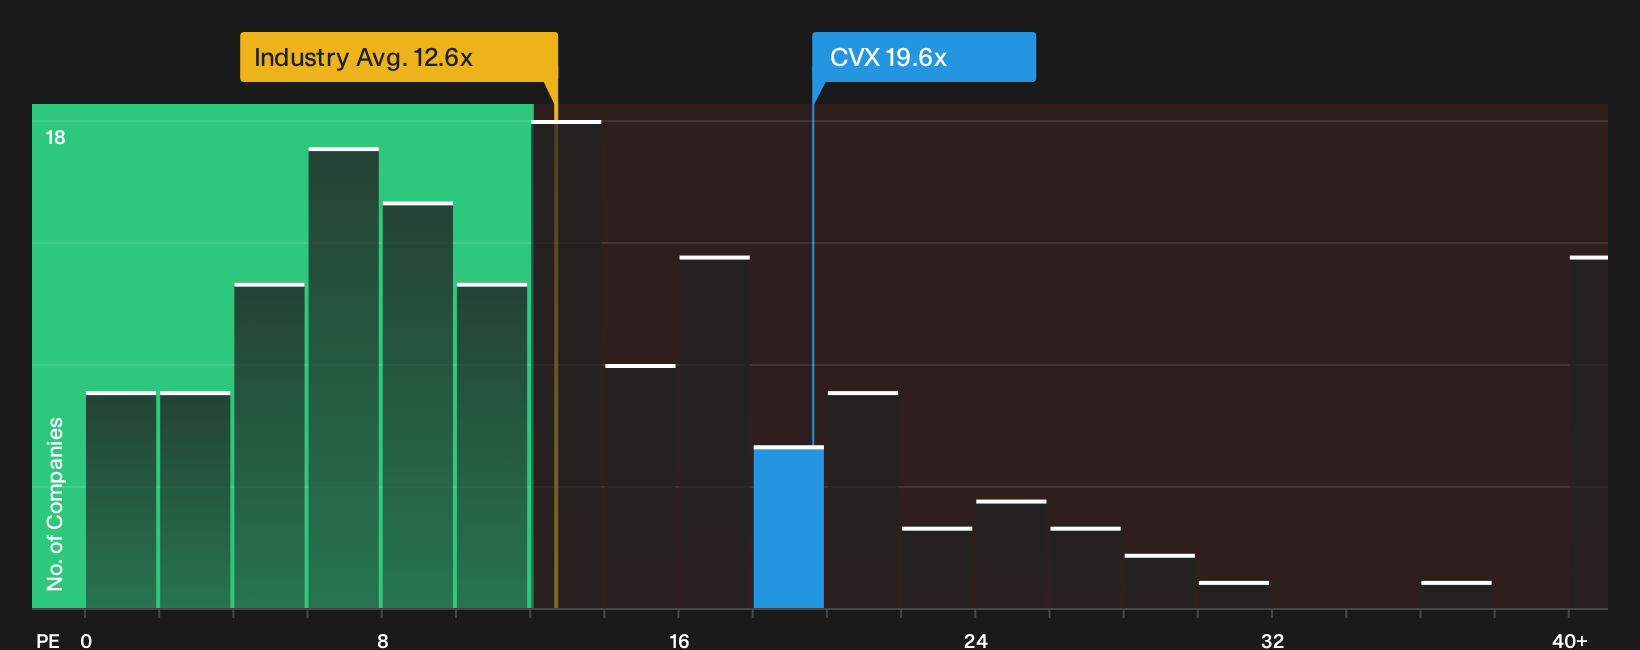
There is a very different message if you focus on what Chevron costs today on earnings. The stock trades on a P/E of 19.6x, which is richer than the US Oil and Gas industry at 12.6x and above peers at 16.6x, yet still below an estimated fair ratio of 24.6x. That mix of premium pricing and headroom leaves investors weighing whether they see more valuation risk or a potential opportunity from here.
For a closer look at how this earnings based picture stacks up against other signals, see what the numbers say in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Chevron valuation and risk so far. Use the full data set, examine both sides carefully, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Chevron?
If Chevron has you thinking harder about where valuation and quality really intersect, do not stop here. Broaden your watchlist with other focused opportunities.
- Target potential mispricings by scanning a curated set of companies that screen as high quality and possibly undervalued through the 30 high quality undervalued stocks.
- Zero in on dependable income by reviewing a hand picked group of higher yielding payers using the 7 dividend fortresses.
- Prioritize resilience by checking a 31 resilient stocks with low risk scores that filters for businesses with lower risk scores before the crowd catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com