
Ultra Clean Holdings (UCTT), Why Is Its Latest Update Drawing Attention?
Ultra Clean Holdings (UCTT) is back in focus after recent discussions around new product qualifications and fresh business wins at its Czech facility, which are expected to start adding revenue from Q4.
Recent price action reflects that split view. Ultra Clean Holdings has a 7 day share price return of 14.44% and a 30 day share price return of 5.41%, but the 90 day share price return is down 34.95%, so momentum has swung sharply after an earlier surge.
Scan how Ultra Clean Holdings compares with other semiconductor suppliers benefiting from capex and fabrication spending shifts by reviewing the curated 85 AI infrastructure stocks in the same space.
Ultra Clean Holdings has run hard over the past year, yet the share price still sits well below the range of published estimates. Is the recent rebound already enough, or does the gap to fair value remain wide?
Most Popular Narrative: 44% Undervalued
Compared with the last close at $77.29, the most followed valuation narrative for Ultra Clean Holdings anchors on a fair value of $137, so the current price sits well below that reference point and puts the focus squarely on whether the long runway sketched out can actually play through.
New product qualifications and business wins, especially at the Czech facility, are expected to contribute incremental revenue starting in Q4, positioning Ultra Clean to benefit from continued accelerated investment in advanced fabs and the robust outlook for semiconductor capital equipment spending (impacts revenue growth).
See why 21 investors see Ultra Clean Holdings as 44% undervalued.
Result: Fair Value of $137 (UNDERVALUED)
Still, concentrated exposure to a handful of large customers and ongoing tariff related costs could quickly challenge the Ultra Clean Holdings upside story if conditions shift.
Find out about the key risks to this Ultra Clean Holdings narrative.
Another View: Ultra Clean Holdings And Cash Flow Value
Ultra Clean Holdings screens as good value on price targets, yet the SWS DCF model paints a very different picture. On that framework, shares around $77.29 sit well above an estimated future cash flow value of $12.62. This points to a wide gap between sentiment and cash generation assumptions.
For investors weighing which story to trust, the key question is whether analyst growth forecasts or the cash flow model better fit their own expectations for Ultra Clean Holdings.
Look into how the SWS DCF model arrives at its fair value.
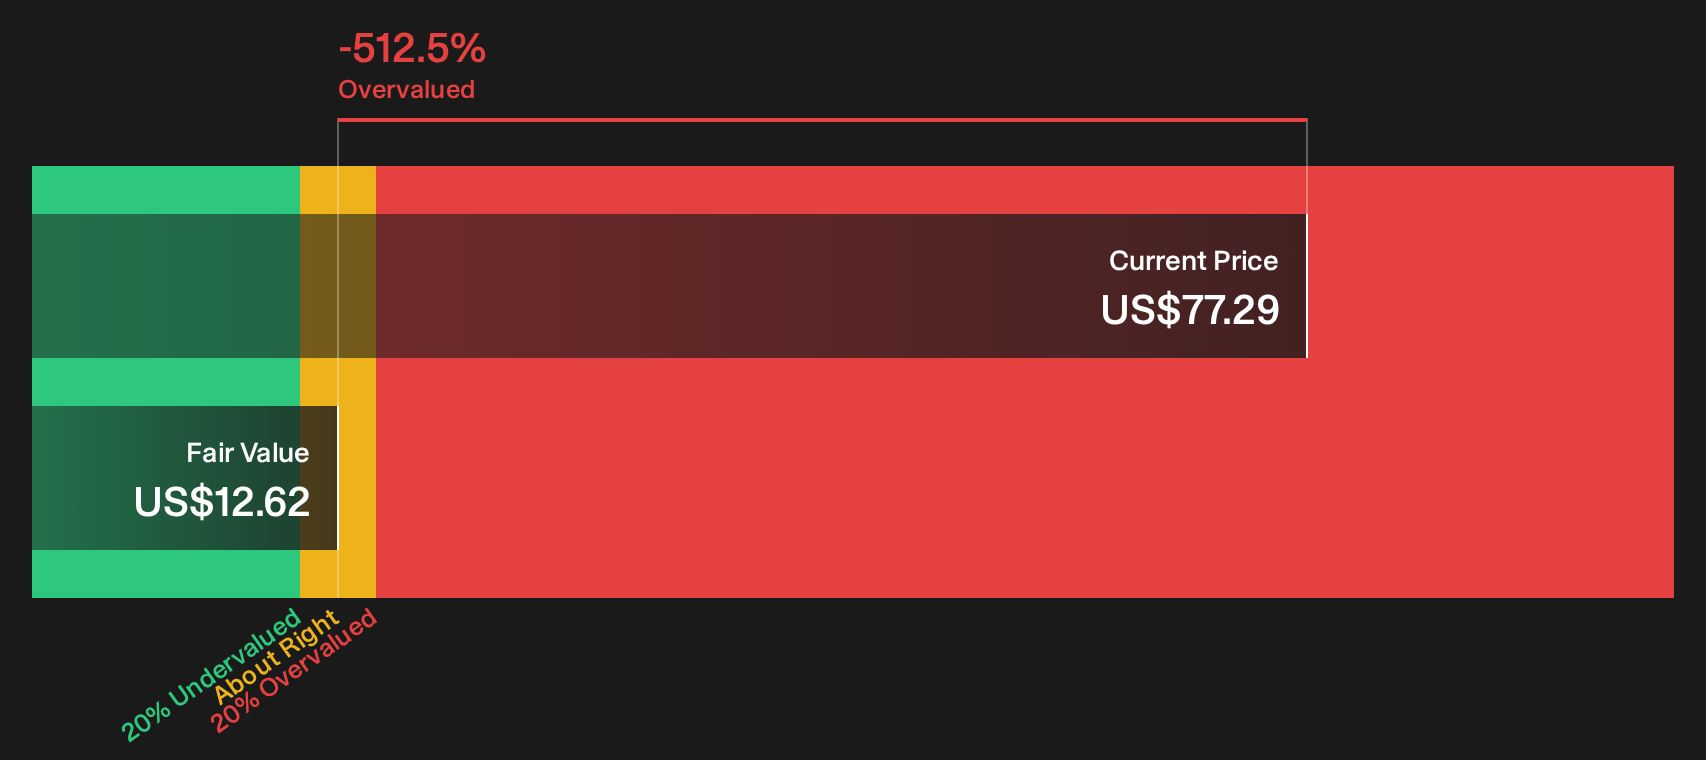
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ultra Clean Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by Ultra Clean Holdings being tagged as both opportunity and risk? Act quickly, test that tension against your own research, and ground your view in the 3 key rewards and 2 important warning signs.
Looking for more Ultra Clean Holdings sized ideas?
If Ultra Clean Holdings has sharpened your focus, do not stop there. Broaden your watchlist using targeted screeners that surface opportunities you might otherwise miss.
- Target reliable income streams by zeroing in on companies in the 7 dividend fortresses that combine higher yields with staying power.
- Hunt for mispriced quality by reviewing the 30 high quality undervalued stocks that filters for strong businesses trading below their assessed worth.
- Safeguard your portfolio by scanning the 31 resilient stocks with low risk scores that highlights resilient stocks with sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com