
Can Garmin (GRMN) Justify Its Valuation After New Wearables Updates And Motorsports Push?
Garmin (GRMN) is back in focus after rolling out free software upgrades for its flagship wearables and Edge cycling computers, alongside a new MYLAPS powered racing solution that extends the brand deeper into motorsports technology.
Garmin has been riding solid momentum, with a 90 day share price return of 22.16% and a year to date gain of 42.06%, even after a modest 1 month share price dip of 1.26% that came alongside a flurry of product launches, acquisitions in training platforms, and the rollout of its AI based Garmin Connect+ service. Over a longer stretch, the picture is even stronger. Total shareholder returns of 23.64% over one year and 193.22% over three years signal that investors who stayed in the stock have been rewarded as sentiment around Garmin's growth and risk profile has evolved.
Capitalize on Garmin’s recent momentum and focus on recurring revenue by scanning a hand picked list of peers with resilient cash flows and balance sheets using our 30 high quality undervalued stocks.Garmin now trades only slightly below the average analyst price target, even as some investors question whether recent gains already reflect its product pipeline and recurring revenue push. Is that caution mispriced or entirely reasonable?
Most Popular Narrative: 1% Undervalued
Garmin's most followed narrative anchors fair value at $290.29, only slightly above the last close of $287.58. This frames the recent rally as largely in line with modelled cash flows rather than speculative excess.
The launch of the Garmin Connect+ premium service, which offers AI based health and fitness insights, is likely to boost subscription based revenue growth and improve overall margins through higher margin services.
The acquisitions of TrainingPeaks and TrainHeroic, which add endurance and strength training platforms around Garmin wearables, are expected to deepen the service ecosystem and create more recurring revenue streams that can support gross margin and operating margin over time.
What is behind 47 investors see Garmin as 1% undervalued.
This narrative relies on a discount rate of 7.99% and assumes Garmin can turn device buyers into long term subscribers across fitness and training platforms, while still absorbing higher memory costs and mixed performance in Outdoor and Auto OEM. It also leans on the idea that services around wearables can help protect margins as hardware cycles mature.
Result: Fair Value of $290.29 (ABOUT RIGHT)
Still, the Garmin narrative could be tested if Outdoor weakness persists, or if higher memory costs bite harder into margins than analysts currently model.
Find out about the key risks to this Garmin narrative.
Another View On Garmin’s Valuation
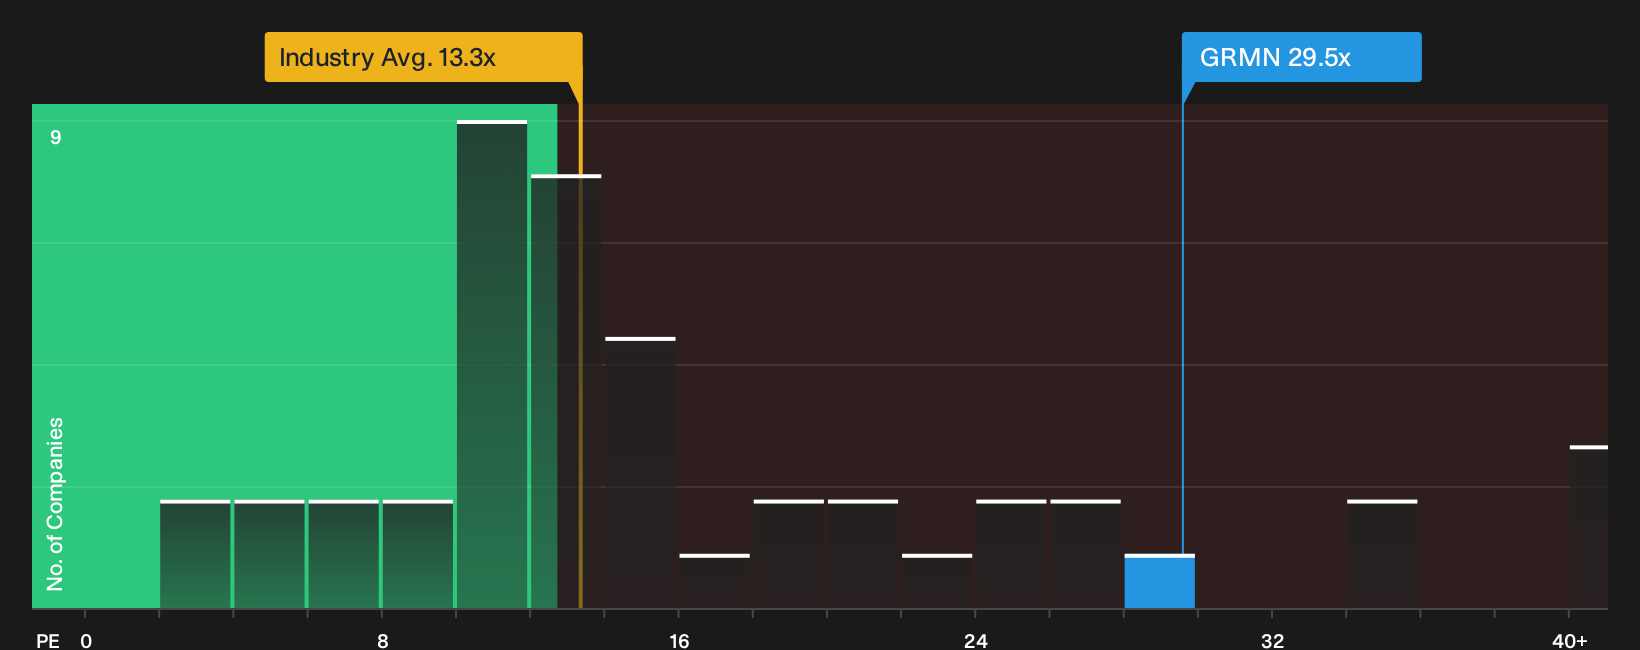
There is a different story when you look at Garmin through its P/E ratio. The shares trade at 29.5x earnings, compared with 23.5x for peers in its group and 13.3x for the broader US Consumer Durables industry. The fair ratio, by comparison, sits lower at 21.6x.
That gap suggests investors already pay a premium for Garmin relative to both peers and the fair ratio the market could move toward. This raises the question of how much execution risk you are willing to accept for that kind of valuation.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Garmin is clearly split, with optimism on recurring revenue set against concerns about execution risk and segment pressure. To move past headlines and react while the current set of numbers is still fresh, weigh both sides of the story with the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Garmin?
If Garmin has sharpened your focus on quality and pricing power, do not stop here. Broaden your watchlist now so you are not chasing the crowd later.
- Target durable value by reviewing companies that combine robust cash generation with appealing entry points using our 30 high quality undervalued stocks.
- Strengthen your income stream by assessing businesses that aim for 5%+ yields and steady payouts through the 7 dividend fortresses.
- Reduce portfolio stress by concentrating on firms with resilient financial footing through our 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com