
Royal Caribbean (RCL) Stock May Trade At A Discount On Resort Deal
Royal Caribbean Cruises has just come through a sharp pullback after a very strong multi year run, which puts fresh focus on whether the current share price still lines up with what its earnings can justify. With the stock now reacting to both market sentiment and big corporate moves, the question is how much of the story is already reflected in the numbers.
- Over the past 5 years, Royal Caribbean Cruises has delivered a gain of 162.7%, so a lot of past optimism about its profit power is now embedded in the track record investors are weighing.
- The planned US$3b purchase of a 50% stake in Sandals and Beaches Resorts may support future earnings by extending the vacation platform beyond ships, while also committing more capital that needs to be serviced by those profits.
- Your read on Royal Caribbean Cruises is one view; the desks covering it have another. See what analysts think Royal Caribbean Cruises's shares could be worth.
The issue now is whether Royal Caribbean Cruises' current valuation is adequately supported by its earnings profile after the recent share price swings and new investment commitments.
If you are weighing Royal Caribbean Cruises against other travel plays that are also being priced on earnings potential, it can help to compare it with companies in 30 high quality undervalued stocks
Does Royal Caribbean Cruises Look Undervalued on Earnings?
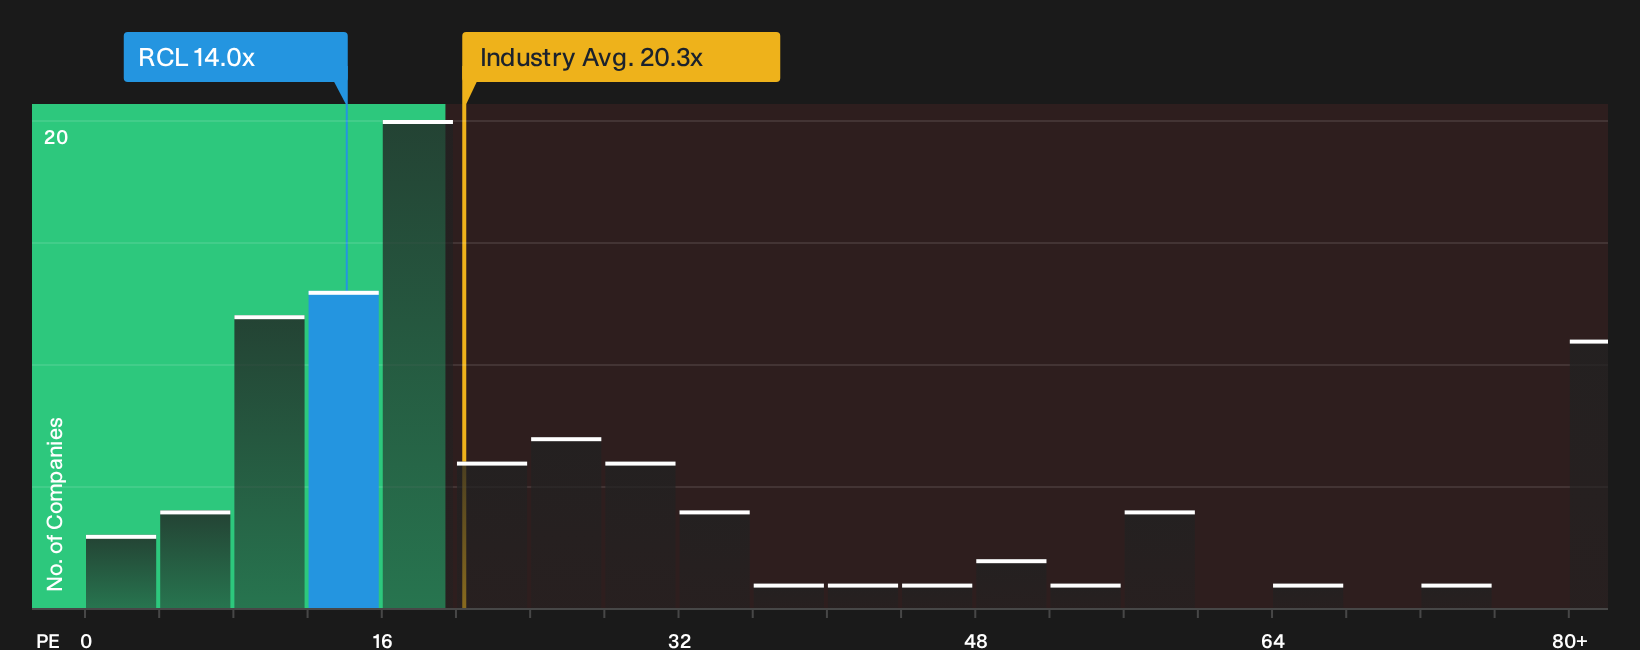
The P/E ratio is a useful lens for Royal Caribbean Cruises because investors are focused on how much they are paying today for each dollar of current earnings. On this metric, the stock trades at about 14.0x earnings, which is well below the wider hospitality sector on roughly 20.3x and also below the peer group average near 34.6x. Because the recently announced US$3b Sandals deal and the debt refinancing both sharpen attention on future profitability, the earnings multiple provides a clear way to see how much of that story is already embedded in the price.
On a tailored basis that blends Royal Caribbean Cruises' growth profile, margins, size and risk, the fair P/E implied by the model sits higher than where the shares currently trade. As a result, the stock screens as undervalued on this framework. Despite the Sandals acquisition agreement and the improved debt profile lifting interest in the story again, the current P/E still prices Royal Caribbean Cruises at a discount to both sector averages and direct peers. Explore the numbers behind Royal Caribbean Cruises's P/E valuation.
The Royal Caribbean Cruises Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle on Royal Caribbean Cruises' valuation leaves off. They spell out which paths for future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each one treats fair value as a thesis about how the business might perform that you can revisit over time on the Community page.
One of the top community narratives on Royal Caribbean Cruises: 34% undervalued
"New ships and enhanced experiences are boosting revenue through higher onboard spending and pre-cruise purchases, driving per-passenger spend growth..."
Discover why this Narrative puts Royal Caribbean Cruises at 34% undervalued.
One more Royal Caribbean Cruises clue worth checking before you move on
You have seen what current earnings and community narratives say about Royal Caribbean Cruises, but professional coverage adds another lens that lets you compare today’s pricing with where the business is projected to be. Explore where analysts expect Royal Caribbean Cruises to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com