
Oppenheimer Holdings (OPY) Could Be 40% Above Fair Value Following Its 59% YTD Run
Oppenheimer Holdings (OPY) has been drawing fresh attention after recent trading lifted the stock’s year-to-date return to about 59%. That move invites a closer look at how its diversified brokerage and investment banking model is being valued.
Recent trading has been choppy but still tilts positive, with a 1-day share price return of 2.13% and a 90-day share price return of 10.02% around the latest close at US$115.35. Over the longer term, the picture is dominated by a 3-year total shareholder return of 221.49%, which presents Oppenheimer Holdings as a stock where momentum has been building rather than fading.
Compare Oppenheimer Holdings' surge with a curated group of other financials that pair recent returns with fundamental metrics through our 30 high quality undervalued stocks.
After a run like this, the real tension is between a share price near US$115 and a wide band of fair value estimates. How far does that gap actually stretch on Oppenheimer Holdings today?
Price-to-Earnings of 12x: Is it justified?
On simple earnings math, Oppenheimer Holdings is being valued at a P/E of 12x, while the latest close sits at $115.35. Against both the wider US market and its own sector, that multiple points to investors paying less for each dollar of current profit than many peers.
The P/E ratio compares the share price to earnings per share and helps you see what investors are willing to pay for the company’s profits. For a middle market investment bank and broker dealer like Oppenheimer Holdings, where fee income and trading results can swing around, P/E often becomes a shorthand for how durable investors think those earnings are.
Two comparisons frame the current setup. The stock’s 12x P/E is below the US market level of 18.2x, and also below the US Capital Markets industry average of 39.6x. This is a very wide gap in both cases. Those spreads suggest the market is assigning Oppenheimer Holdings a lower valuation tag than both the broad market and sector peers for each dollar of earnings today.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 12x (UNDERVALUED).
Still, any reversal in trading activity or a sharp slowdown in advisory deals could challenge how comfortably Oppenheimer Holdings sits on a 12x P/E.
Find out about the key risks to this Oppenheimer Holdings narrative.
Another View on Oppenheimer Holdings: Cash Flows Point the Other Way
The P/E points to Oppenheimer Holdings looking cheap, but the SWS DCF model tells a different story. On that cash flow view, the shares around $115.35 sit above an estimated future cash flow value of about $69.52. That labels the stock as overvalued on this second yardstick and raises the question of which lens you trust more.
Look into how the SWS DCF model arrives at its fair value.
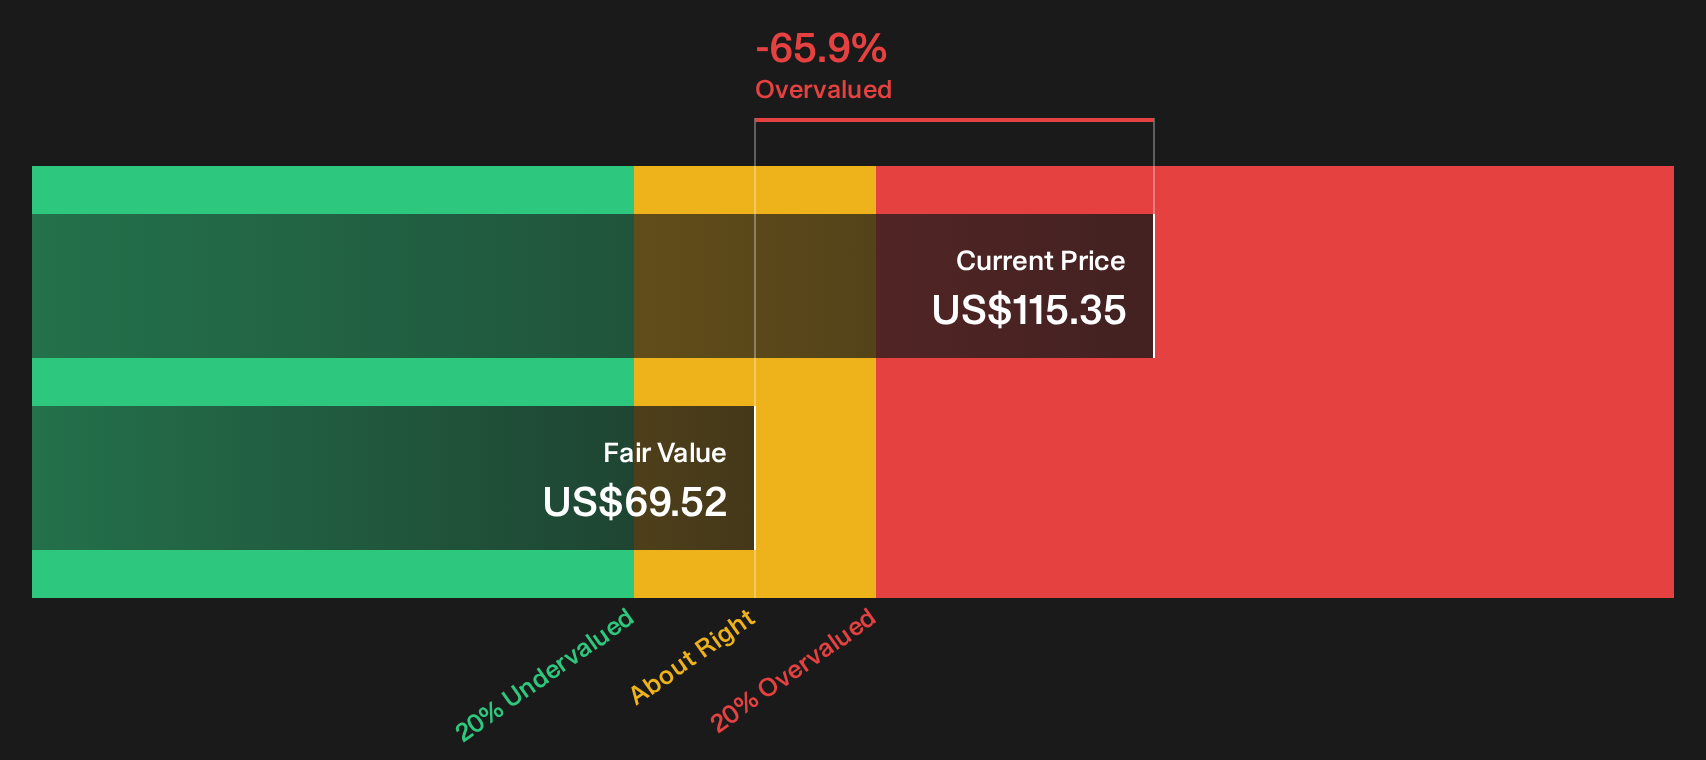
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oppenheimer Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Oppenheimer Holdings so far. If you want a clear view, check the numbers yourself and weigh both sides of the story. The fastest way to see that balance is to review the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Oppenheimer Holdings?
If Oppenheimer Holdings has your attention, do not stop here. Broaden your watchlist with other ideas that match your goals, risk tolerance, and income needs.
- Target potential mispricings by scanning a focused set of quality picks through the 30 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that feature the 7 dividend fortresses.
- Dial down portfolio risk by filtering for sturdier businesses using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com