
EQ Resources (ASX:EQR) Secures APT JV Stake, Is The Springer Upside Fully Priced?
EQ Resources enters US backed tungsten project
EQ Resources (ASX:EQR) is part of a new binding agreement with Blue Moon Metals and The Elmet Group centered on the Springer Tungsten Complex in Nevada, backed by US$150 million of targeted project funding.
The deal gives EQ Resources a 10% equity stake in a new joint venture that will own and run the ammonium paratungstate (APT) plant, plus a defined allocation of the facility’s input capacity through long term concentrate supply arrangements.
EQ Resources has already seen momentum build around the story, with the share price delivering a 90 day share price return of 81.82% and a year to date share price gain of just over 5x. The 1 year total shareholder return of around 15x suggests recent project updates and funding news are being priced as a material shift in future potential and risk profile.
Spot opportunities around EQ Resources by scanning a curated list of 36 best rare earth metal stocks that are plugged into the same critical minerals theme.EQ Resources now trades around A$0.50 after a sharp rerate on the US backed tungsten deal. Does that price already reflect the Springer upside, or is valuation still playing catch up?
Most Popular Narrative: 100% Overvalued
EQ Resources last closed at A$0.50, while the most followed narrative pegs fair value at A$0.25. This frames the current price as rich against that view and places a lot of weight on how the tungsten story plays out.
I think that with the global production being roughly 84,000 to 98,000 tonnes annually, the market faces a severe deficit in 2026, with Chinese export volumes of intermediate products like Ammonium Paratungstate (APT) falling significantly. And with China controlling the majority of supply, and new Western mining projects in Australia, Spain, and North America attempting to reduce reliance, supply still remains constrained.
See why 6 investors see EQ Resources as 100% overvalued.
Result: Fair Value of A$0.25 (OVERVALUED)
Still, the EQ Resources story can unravel quickly if tungsten prices retreat or if new non Chinese supply ramps up faster than current narrative assumptions.
Find out about the key risks to this EQ Resources narrative.
Another View on EQ Resources valuation
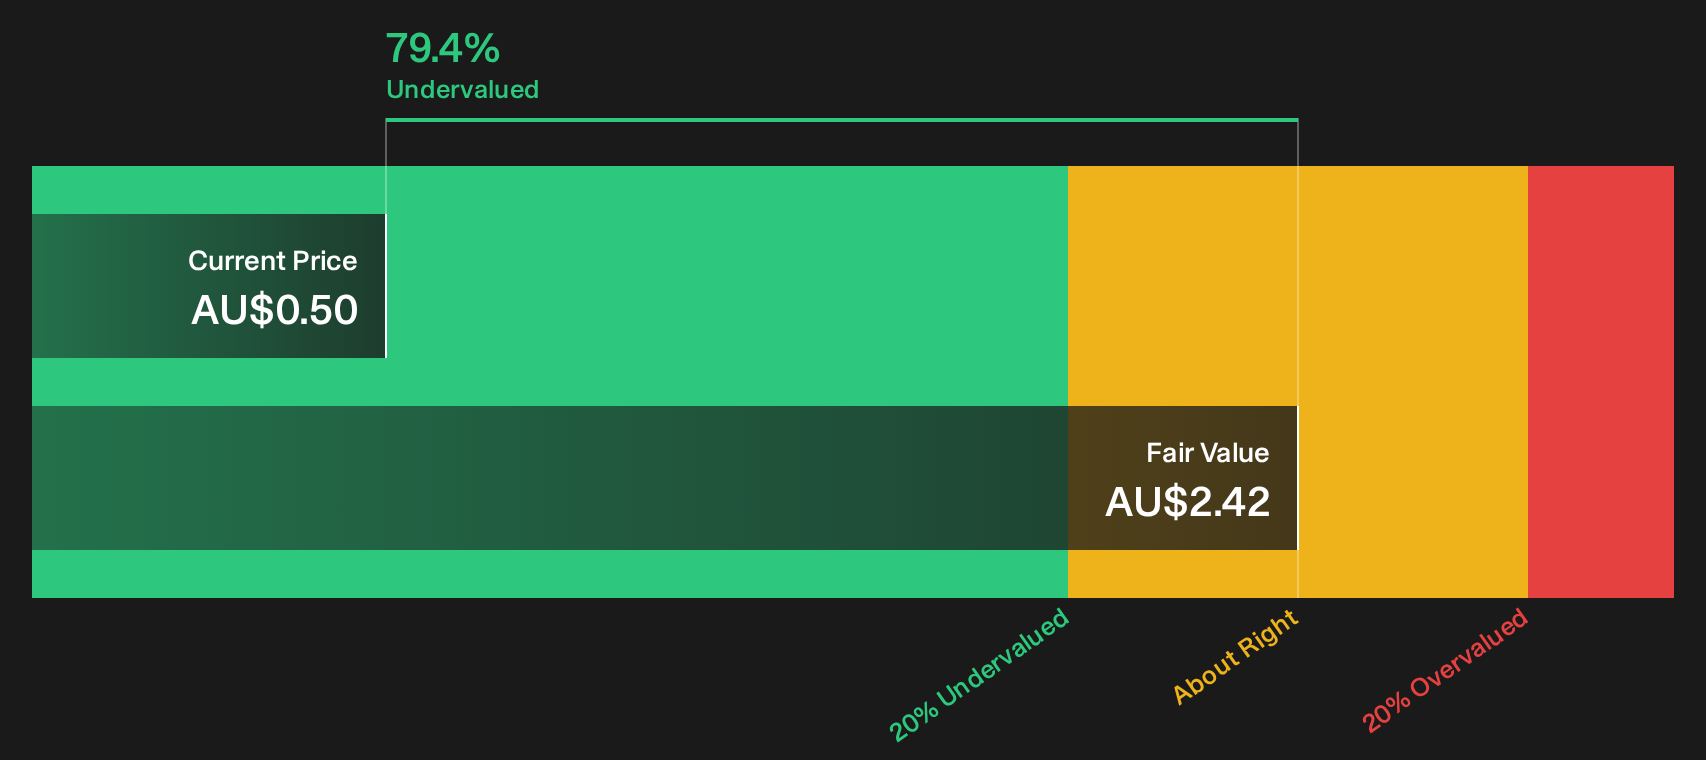
The first narrative pegs EQ Resources at a fair value of A$0.25, which frames the current A$0.50 price as expensive. Using a different lens, our DCF model estimates future cash flow value at A$2.42 per share, which points to deep undervaluation if those projections hold up.
These two methods produce very different answers, and both rely on bold assumptions about future production, tungsten pricing, and funding risk. Which one feels closer to how you think EQ Resources will actually execute over the next few years, and which assumptions would you challenge first?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on EQ Resources valuation and risk are already clear in the numbers, so move fast on your own homework and pressure test both sides of the story. To see a concise breakdown of both the concern and the upside case in one place, start with 2 key rewards and 2 important warning signs.
Looking for more EQ Resources style ideas?
If EQ Resources has sharpened your focus on where capital could work harder, do not stop here. Use the screeners below to pressure test fresh ideas.
- Chase mispriced opportunities by scanning a curated spread of companies that screen as undervalued on quality and fundamentals through 6 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with sturdy finances and clean balance sheets using the list of solid balance sheet and fundamentals (12 results).
- Hunt for off the radar potential by zeroing in on strong fundamentals hidden in plain sight with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com