
UWM Holdings (UWMC) Stock Dropped, So What Is Driving Attention Now?
UWM Holdings (UWMC) has put fresh capital raising at center stage, detailing a rights offering of 200 million new Class A shares that could bring in at least US$400 million in gross proceeds.
Recent trading tells a tough story for UWM Holdings, with the share price down 14.08% over the past month and 42.45% over 90 days, while the 1-year total shareholder return has fallen 79.21% as investors reassess risk around the business. This backdrop now frames this rights offering as a key attempt to reset confidence and shore up the capital base.
Scan beyond UWM Holdings and compare this rights issue story with other beaten down financials by checking the hand picked 31 resilient stocks with low risk scores that may offer sturdier footing.
For UWM Holdings, the steep share price slide and this large capital raise can signal either deeper pressure in the mortgage engine or simply washed out sentiment. Which of these possibilities does the current valuation reflect?
Most Popular Narrative: 45% Undervalued
UWM Holdings last closed at $1.22, while the most followed narrative anchors fair value closer to $2.22. This frames this rights issue against a market price that already reflects a heavy discount.
Continued investment and successful deployment of advanced AI tools (like BOLT, ChatUWM, LEO, and Mia) are materially increasing broker productivity, efficiency, and borrower retention, providing UWM with lower unit costs and the ability to handle significantly higher loan volumes without a proportional increase in costs, which should drive long-term revenue growth and operating margin expansion.
See why 11 investors see UWM Holdings as 45% undervalued.
Result: Fair Value of $2.22 (UNDERVALUED)
Still, the UWM Holdings story can break if heavy tech spending fails to translate into higher origination volumes or if wholesale brokers shift business toward competing platforms.
Find out about the key risks to this UWM Holdings narrative.
Another View On UWM Holdings: Cash Flows Paint A Tougher Picture
Analyst narratives frame UWM Holdings as 45% undervalued at a fair value of about $2.22 per share, yet the SWS DCF model points to a future cash flow value closer to $1.09. That implies the current $1.22 quote is above this cash based estimate. Which story do you trust when cash generation is still unproven?
Look into how the SWS DCF model arrives at its fair value.
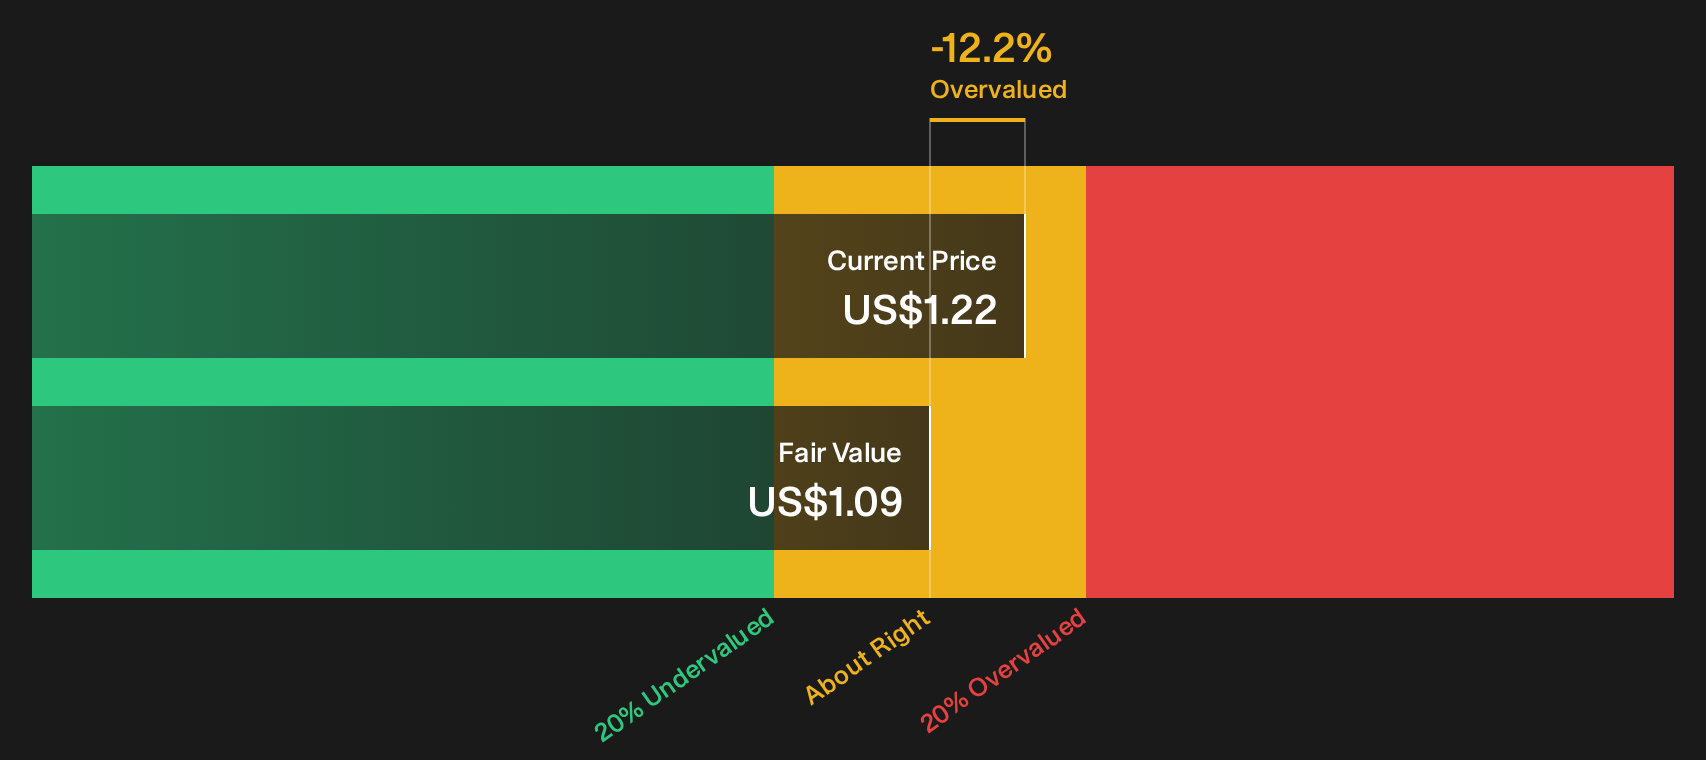
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UWM Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around UWM Holdings do not have to leave you guessing. Move quickly, review the full data set, and weigh both the upside and the concerns in the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond UWM Holdings?
If UWM Holdings has your attention but you want a wider watchlist, use the Simply Wall St Screener to uncover fresh angles and avoid relying on a single story.
- Target potential mispricings across the market by scanning a curated 30 high quality undervalued stocks that already filters for quality and financial strength.
- Prioritize resilience and balance sheet health by reviewing a focused list of solid balance sheet and fundamentals (23 results) that screens out weaker financial structures before you commit time or capital.
- Hunt for under-the-radar opportunities by working through a hand picked 16 high quality undiscovered gems that spotlights fundamentals the broader market may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com