
3 Dividend Stocks With Yield Over 3%
Rising global bond yields, with the 10 year US Treasury hitting levels last seen in 2007, have pushed income seeking investors to look harder at what they are paid to wait. Cash and government debt now compete more directly with equities. That raises the bar for dividends. Well covered payouts above 3% that show consistency and growth look especially valuable. This article highlights three such high yield stocks.
The three stocks covered below are just a starting sample, with the full screen surfacing 171 more companies with similar income profiles and equally compelling dividend stories that are not included here.
If you want to go deeper into this high yield universe, head straight to the Dividend Powerhouses (3%+ Yield) screener to identify, filter and analyze the dividend plays that best fit your income goals.
Accenture (ACN)
Overview: Accenture is a global consulting and outsourcing firm that uses long-term technology and operations contracts to generate steady cash flow that supports its 3%+ dividend yield.
Operations: Accenture earns about US$22.3b from Products clients, US$14.9b from Health & Public Service, US$13.8b from Financial Services, US$12.4b from Communications, Media & Technology, and US$9.8b from Resources, with further revenue from Asia Pacific.
Market Cap: US$112.4b
Accenture matters for this Dividend Powerhouses screen because its consulting and outsourcing engine converts large, recurring client work into the kind of cash flow that can underpin a well covered, higher yielding payout.
"AI could reduce the need for traditional consulting, coding, testing, documentation, support, and outsourcing roles, forcing Accenture to retrain and restructure its workforce."
Investor returns from Accenture’s dividend and buybacks could look very different depending on how one unseen pressure shapes future margins.
If that pressure point is on your radar, read the full narrative for Accenture to see how Accenture could turn AI disruption into an accelerating cash engine.

Kaspi.kz (KSPI)
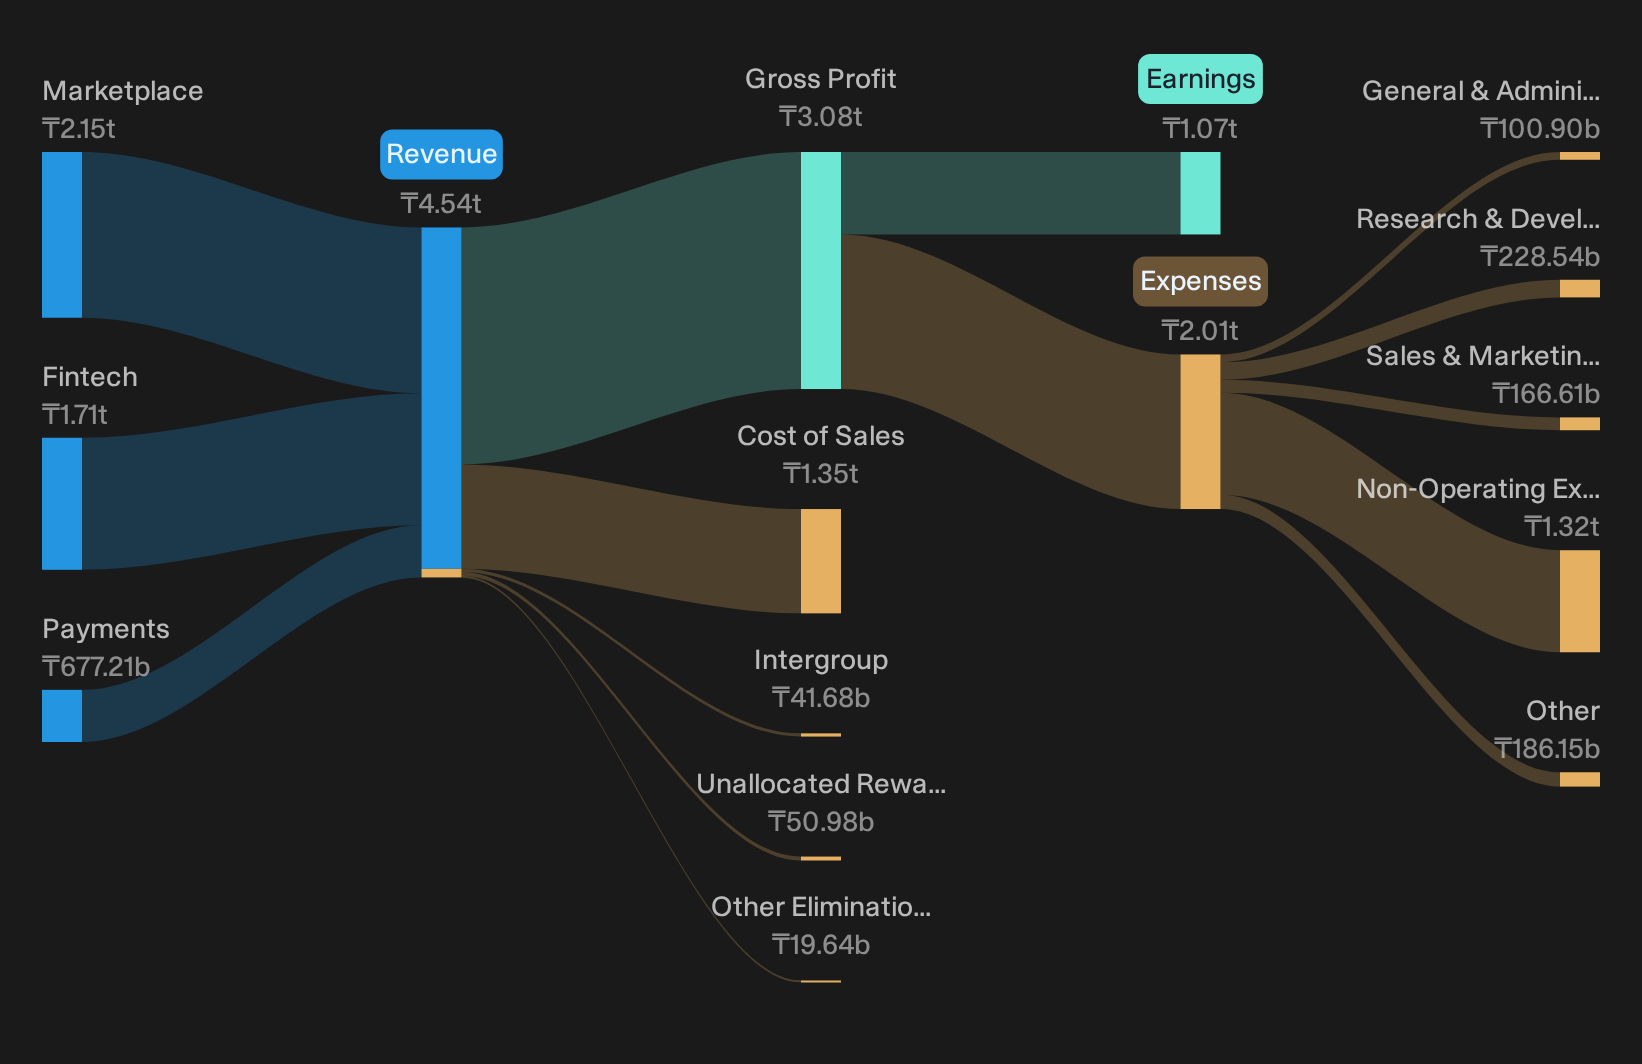
Overview: Kaspi.kz runs a super app that blends payments, marketplace shopping, and fintech services. It uses its high margin Payments arm to support recurring, well covered dividends.
Operations: Kaspi.kz generates about KZT 2,151b from Marketplace, KZT 1,714b from Fintech, and KZT 677b from Payments, mostly across Kazakhstan and Turkey.
Market Cap: US$18.3b
Kaspi.kz matters for a Dividend Powerhouses screen because its payments engine generates recurring transaction fees that help anchor a high yield, even as the wider ecosystem stretches into new geographies and products.
"Continued expansion and high engagement in payments, marketplace, and fintech super-app ecosystem are fueling cross-selling and deeper user integration, supporting higher take rates and sustained revenue expansion."
What investors need to watch is how one shift in profitability shapes the balance between rapid expansion and dependable cash returns.
That trade off between reinvestment and payouts is exactly what the full narrative for Kaspi.kz unpacks, highlighting where Kaspi.kz could still surprise on cash generation.
VICI Properties (VICI)
Overview: VICI Properties is a real estate investment trust that owns casino, hotel and leisure properties, collecting long-term rent that supports its dividend.
Operations: VICI Properties generates about US$4.1b from real estate investment activities, with all of that rental income coming from United States properties.
Market Cap: US$26.4b
For income investors, VICI Properties matters because those long leases on gaming and hospitality real estate convert into visible rent checks that underpin its yield.
"I believe the present uncertainty and unrest on the United States and its immigration and tourism policies will penalize the growth of VICI during the next couple of years, being more pronounced on the next year, and tapering a little above the economy growth rate after that."
Investor outcomes hinge on how one unresolved stress test of that rental stream influences both dividend confidence and future pricing power.
That stress test is exactly why it helps to read the full narrative for VICI Properties and see how VICI Properties could turn short term pressure into accelerating income resilience.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, building momentum and under the radar for now, often get caught late once prices start flying. Scan new angles and act promptly.
- Identify resilient businesses before sentiment shifts by running the 31 resilient stocks with low risk scores while the market is still pricing them as afterthoughts.
- Explore structural shifts in computing by using the 25 quantum computing stocks while these potential disruptors are still priced like niche experiments.
- Find durable miners with real cash generation by scanning the 36 elite gold producer stocks while these producers remain off most radar screens.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com