
How AI Workflow Wins At ServiceNow (NOW) Have Changed Its Investment Story
- In March 2026, INRY deployed ServiceNow EmployeeWorks as a conversational AI front door across its enterprise, integrating with tools like Microsoft Teams, Jira, and SharePoint, and reported a 60% reduction in median submission time for self-service allocation requests plus 97% request completion rates.
- The rollout shows how ServiceNow’s AI platform can replace fragmented portals with a single workflow layer that shortens routine tasks, removes app switching, and supports high internal satisfaction scores. Partners such as Xapien and the Blueprint Alliance extend use cases into due diligence and AI agent governance.
- We will now look at how ServiceNow's AI front door adoption by INRY could influence the broader investment narrative around the platform.
ServiceNow Investment Narrative Recap
Owning ServiceNow means believing its AI workflow platform can keep winning enterprise budgets as companies standardize on a single system of record. The INRY rollout, with 60% faster self service submissions and 97% completion rates, reinforces that operational thesis. In the short term, the key swing factor remains execution on AI led workflow expansion rather than any one client deployment.
The biggest immediate risk remains execution overload as ServiceNow stretches into CRM, industry workflows, public sector and deeper AI. Integration work around acquisitions and rapid product launches could weigh on margins if projects stall. The INRY case is helpful proof of delivery, but not a game changer for near term risk.
The most relevant nearby development is Xapien becoming a native app on the ServiceNow AI Platform. That integration places automated due diligence directly inside existing workflows for onboarding and third party risk, which aligns with the same thesis investors need to believe. ServiceNow is aiming to be the orchestration layer where many specialized AI tools plug in.
If that ecosystem approach scales, each successful partner application can deepen customer reliance on the platform and support cross selling. Execution risk sits on the other side of that opportunity. ServiceNow needs to coordinate partners like Xapien, Accenture and others without overcomplicating deployments or slowing time to value for clients that are watching costs and AI payback closely.
ServiceNow's current analyst story centers on revenue reaching US$23.6b and earnings of US$4.0b by 2029, based on an assumed 19.1% yearly revenue growth rate and an earnings increase of about 2.2x from US$1.8b today.
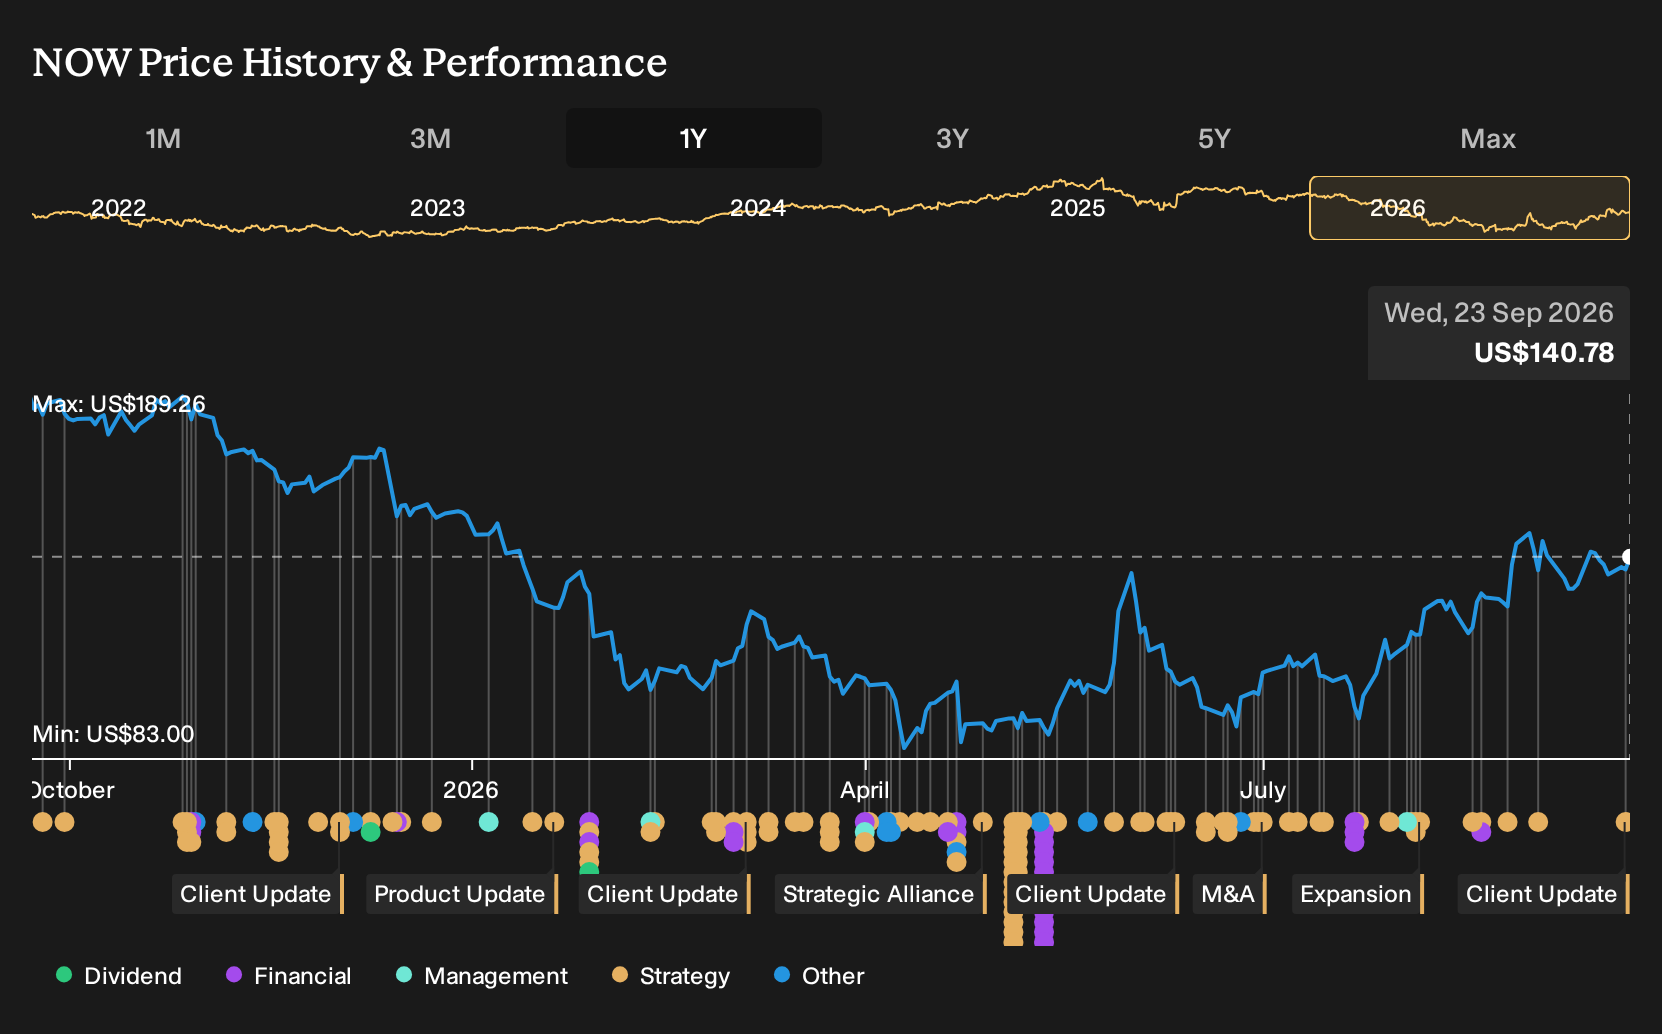
Uncover why ServiceNow's fair value indicates a gap that aligns with its current price.
Exploring Other Perspectives
The lowest analysts tell a very different ServiceNow story. They worry that hybrid AI pricing slows the money, with revenue modeled at 18.3% a year and earnings at US$2.4b by 2029 instead of US$4.0b. Use the INRY news as a chance to test those cautious assumptions against your own view.
Explore 23 other ServiceNow fair value estimates, including one that suggests as much as 36% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ServiceNow research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ServiceNow. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ServiceNow's overall financial health at a glance.
Looking For More Ideas Beyond ServiceNow?
If the ServiceNow story has sharpened your view on workflow and AI platforms, use that same lens to scan the wider market. A focused screener can quickly surface other businesses that fit the risk, income, or balance sheet profile you want to research next.
- For investors who want potential upside with strict financial filters, start by reviewing a curated set of quality names through the 16 high quality undiscovered gems.
- If capital preservation and steadier profiles matter more to you than headline growth, narrow your search using a 31 resilient stocks with low risk scores that keeps an eye on resilience first.
- When you care most about financial strength before anything else, anchor your watchlist with a list of solid balance sheet and fundamentals (23 results) that screens for robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com