
TSX Growth Companies With High Insider Ownership September 2026
As the Federal Reserve's recent rate hike signals a modestly hawkish stance, Canadian markets are closely watching how these changes might influence their own economic landscape. In this environment, growth companies with high insider ownership can be particularly appealing, as they often demonstrate strong alignment between management and shareholder interests, potentially offering resilience in times of economic adjustment.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 39.7% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32% |
| Firan Technology Group (TSX:FTG) | 12.6% | 22% |
| Electrovaya (TSX:ELVA) | 34.9% | 47.9% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.9% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Aritzia (TSX:ATZ) | 16.2% | 20.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 39.4% |
Let's review some notable picks from our screened stocks.
Colliers International Group (TSX:CIGI)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Colliers International Group Inc. offers commercial real estate, engineering, and investment management solutions across various regions including the United States, Canada, Europe, and Asia with a market cap of CA$6.65 billion.
Operations: The company's revenue is derived from Commercial Real Estate ($3.49 billion), Engineering ($1.90 billion), and Investment Management ($562.38 million).
Insider Ownership: 14.7%
Earnings Growth Forecast: 17% p.a.
Colliers International Group is positioned for growth with revenue expected to increase at 8.7% annually, outpacing the Canadian market's 4.4%. Despite not achieving significant earnings growth, its forecasted annual profit growth of 17% surpasses the market average. The company trades at a substantial discount to its estimated fair value and anticipates mid-teens revenue growth for 2026. Recent leadership changes include Stephanie Marshall as Managing Director, enhancing strategic capabilities in investment strategy and asset management.
- Navigate through the intricacies of Colliers International Group with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Colliers International Group shares in the market.
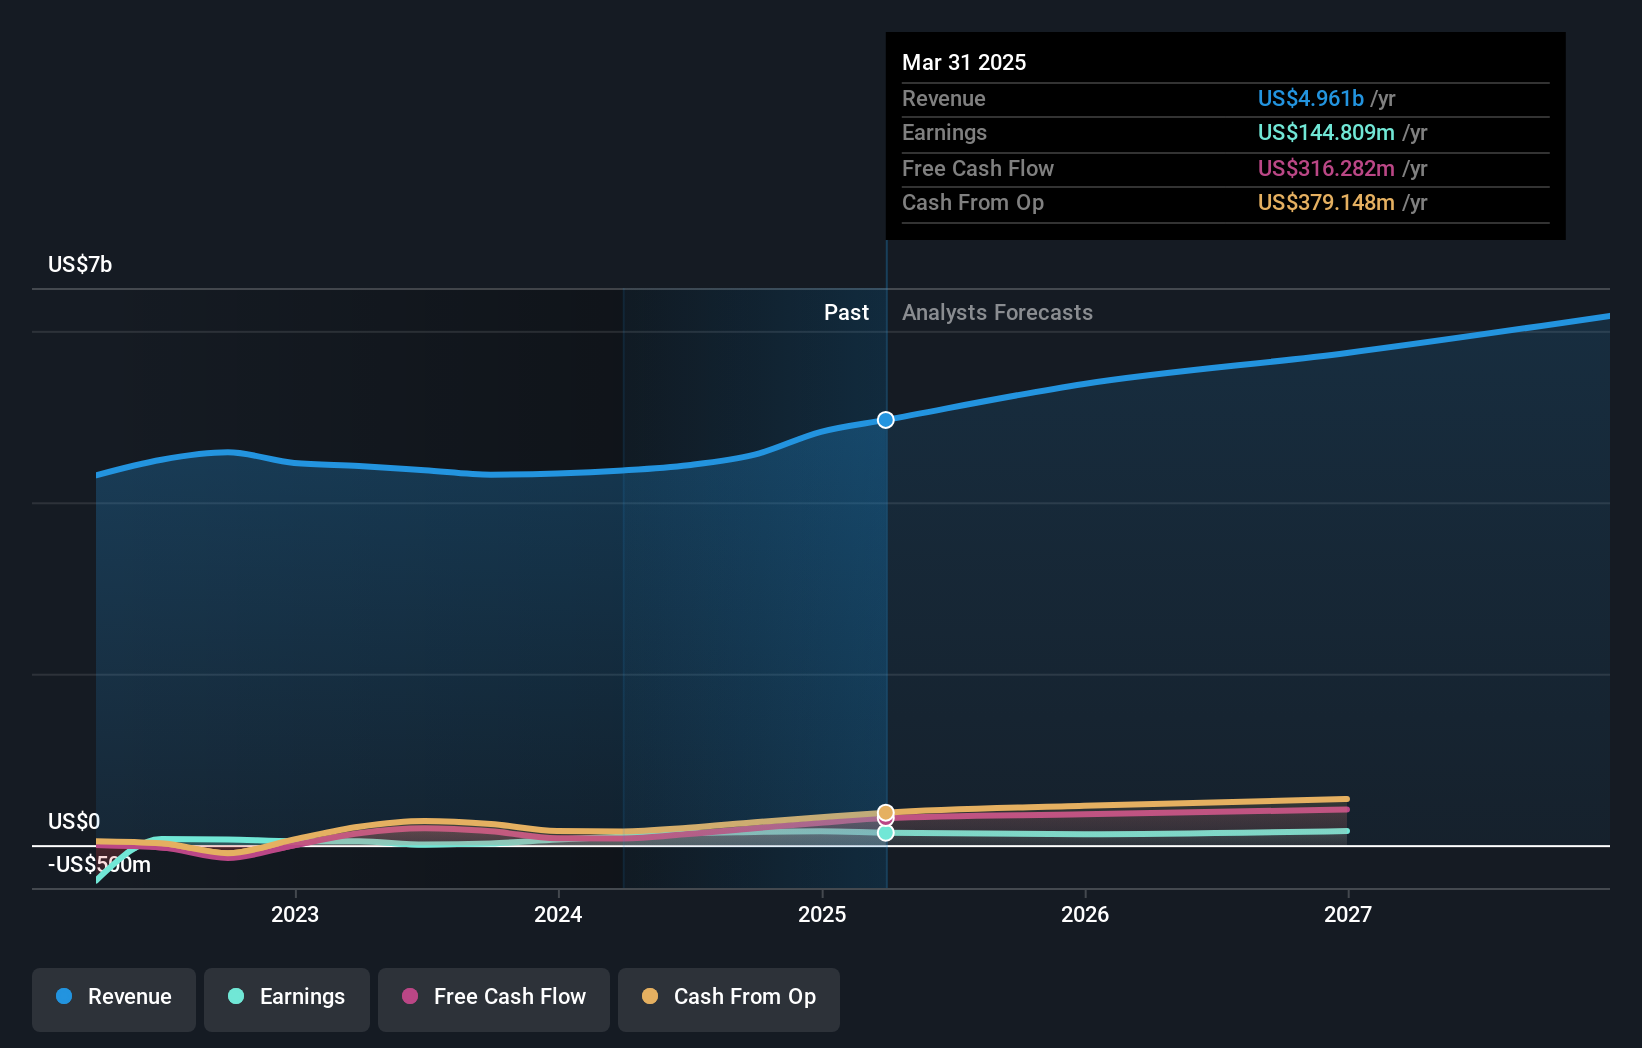
Firan Technology Group (TSX:FTG)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Firan Technology Group Corporation manufactures and sells aerospace and defense electronic products and subsystems internationally, with a market cap of CA$573.20 million.
Operations: The company's revenue segments include Circuits, generating CA$128.46 million, and Aerospace, contributing CA$74.58 million.
Insider Ownership: 12.6%
Earnings Growth Forecast: 22% p.a.
Firan Technology Group is poised for growth, with revenue projected to rise 10.3% annually, exceeding the Canadian market's 4.4%. Earnings are expected to grow significantly at 22% per year, outpacing the market average of 11.3%. Insider buying has occurred recently, albeit in modest volumes. The company trades below its fair value estimate and was added to the S&P Global BMI Index in September 2026, highlighting its expanding market presence.
- Click here to discover the nuances of Firan Technology Group with our detailed analytical future growth report.
- Insights from our recent valuation report point to the potential overvaluation of Firan Technology Group shares in the market.
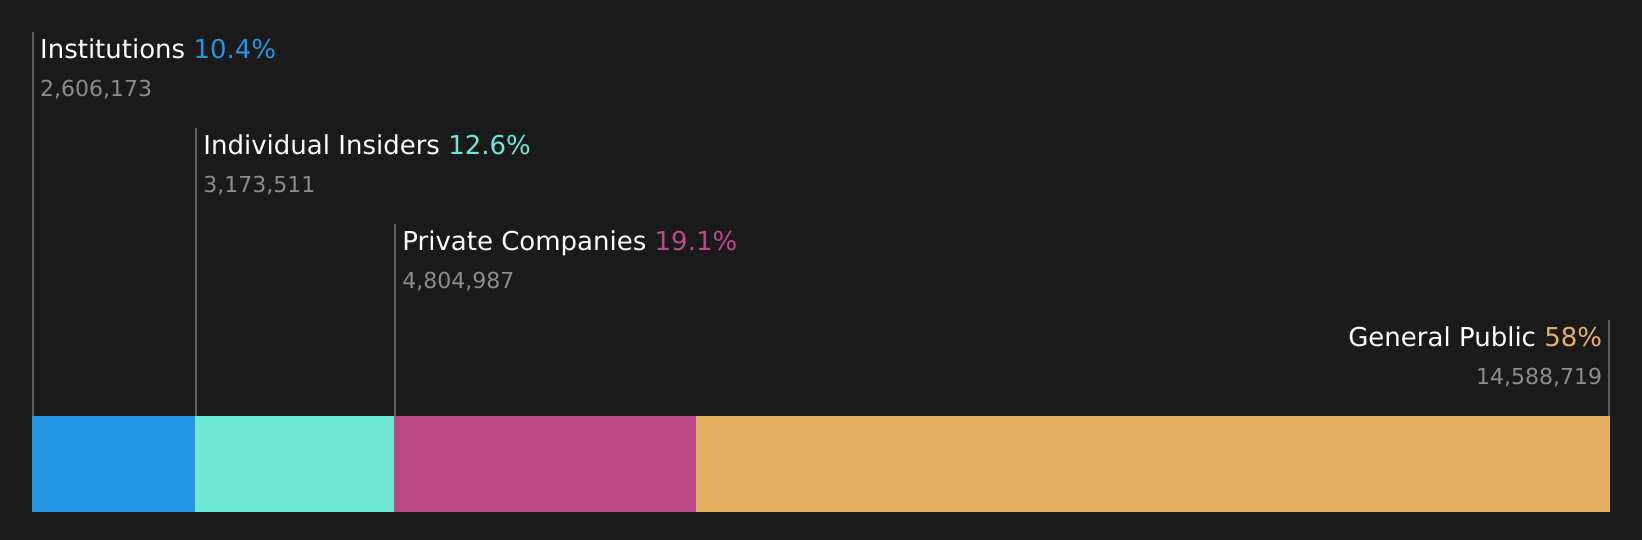
Stingray Group (TSX:RAY)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Stingray Group Inc. is a music, media, and technology company operating in Canada, the United States, and internationally with a market cap of CA$1.04 billion.
Operations: The company's revenue is derived from two main segments: CA$130.20 million from Radio and CA$389.95 million from Broadcasting and Commercial Music.
Insider Ownership: 24.6%
Earnings Growth Forecast: 75.1% p.a.
Stingray Group is set for growth, with revenue expected to grow 12.9% annually, surpassing the Canadian market's average. Earnings are forecast to rise significantly by 75.1% per year. The company trades at a substantial discount to its estimated fair value and was recently added to the S&P Global BMI Index, enhancing its visibility. A share repurchase program has been announced, potentially benefiting shareholders through reduced share count and increased ownership concentration.
- Click here and access our complete growth analysis report to understand the dynamics of Stingray Group.
- Our expertly prepared valuation report Stingray Group implies its share price may be lower than expected.

Seize The Opportunity
- Embark on your investment journey to our 48 Fast Growing TSX Companies With High Insider Ownership selection here.
- Curious About Other Options? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com