
Learn Why The Bull Case For Silicon Motion Technology Stock Could Change Following AI Data Center Push
- Silicon Motion Technology recently presented at the 5th Global Memory Innovation Forum, outlining how its MonTitan SSD Reference Design Kit targets enterprise AI data centers and tying this product push to management's guidance for sequential third quarter 2026 revenue and operating margin improvements.
- The focus on AI Factory, Edge AI, and embedded storage shows Silicon Motion Technology leaning into higher specification controller demand that can support more complex workloads. Revised earnings estimates highlight how investors are reassessing the durability and breadth of that product mix.
- We will now look at how Silicon Motion Technology's upbeat AI focused guidance could influence the existing investment narrative around margin durability.
Scan beyond Silicon Motion Technology and see which other AI infrastructure plays are pushing hard into data center controllers and storage with our hand picked 85 AI infrastructure stocks
Silicon Motion Technology Investment Narrative Recap
To own Silicon Motion Technology, you need to believe its controller portfolio can keep earning slots in AI data centers, PCs, and embedded devices while holding a reasonable line on pricing and costs. The short term swing factor now is whether the MonTitan enterprise push and related AI products actually translate into the sequential revenue and operating margin gains management has outlined for Q3 2026.
The biggest risk for you as a shareholder remains basic semiconductor math. Intense price competition, rising R&D tied to advanced nodes, and customer concentration can all eat into margins if orders or design ramps disappoint. The new guidance does not remove those issues. It signals where management thinks the product mix may help.
The recent presentation at the 5th Global Memory Innovation Forum is the clearest operational update linked to these themes. Silicon Motion Technology put MonTitan and its broader AI focused controller suite in front of enterprise buyers and partners, while explicitly tying that portfolio to expectations for sequential revenue and operating margin improvement in the current quarter.
For you, the relevance is practical rather than promotional. Execution on MonTitan and related AI Factory and Edge AI sockets could support the forecast earnings and return on equity profile that analysts model, if design wins translate into volume shipments without aggressive discounting. Failure to scale those deployments, or any need to cut pricing to protect share, would feed directly into the margin and earnings quality risks already on the table.
Silicon Motion Technology's current earnings of US$289.8 million are set against analyst projections that point to US$3.1b in revenue and US$636.9 million in earnings by 2029, based on an assumed 33.1% yearly revenue growth rate and an earnings increase of about US$347 million from earnings today.
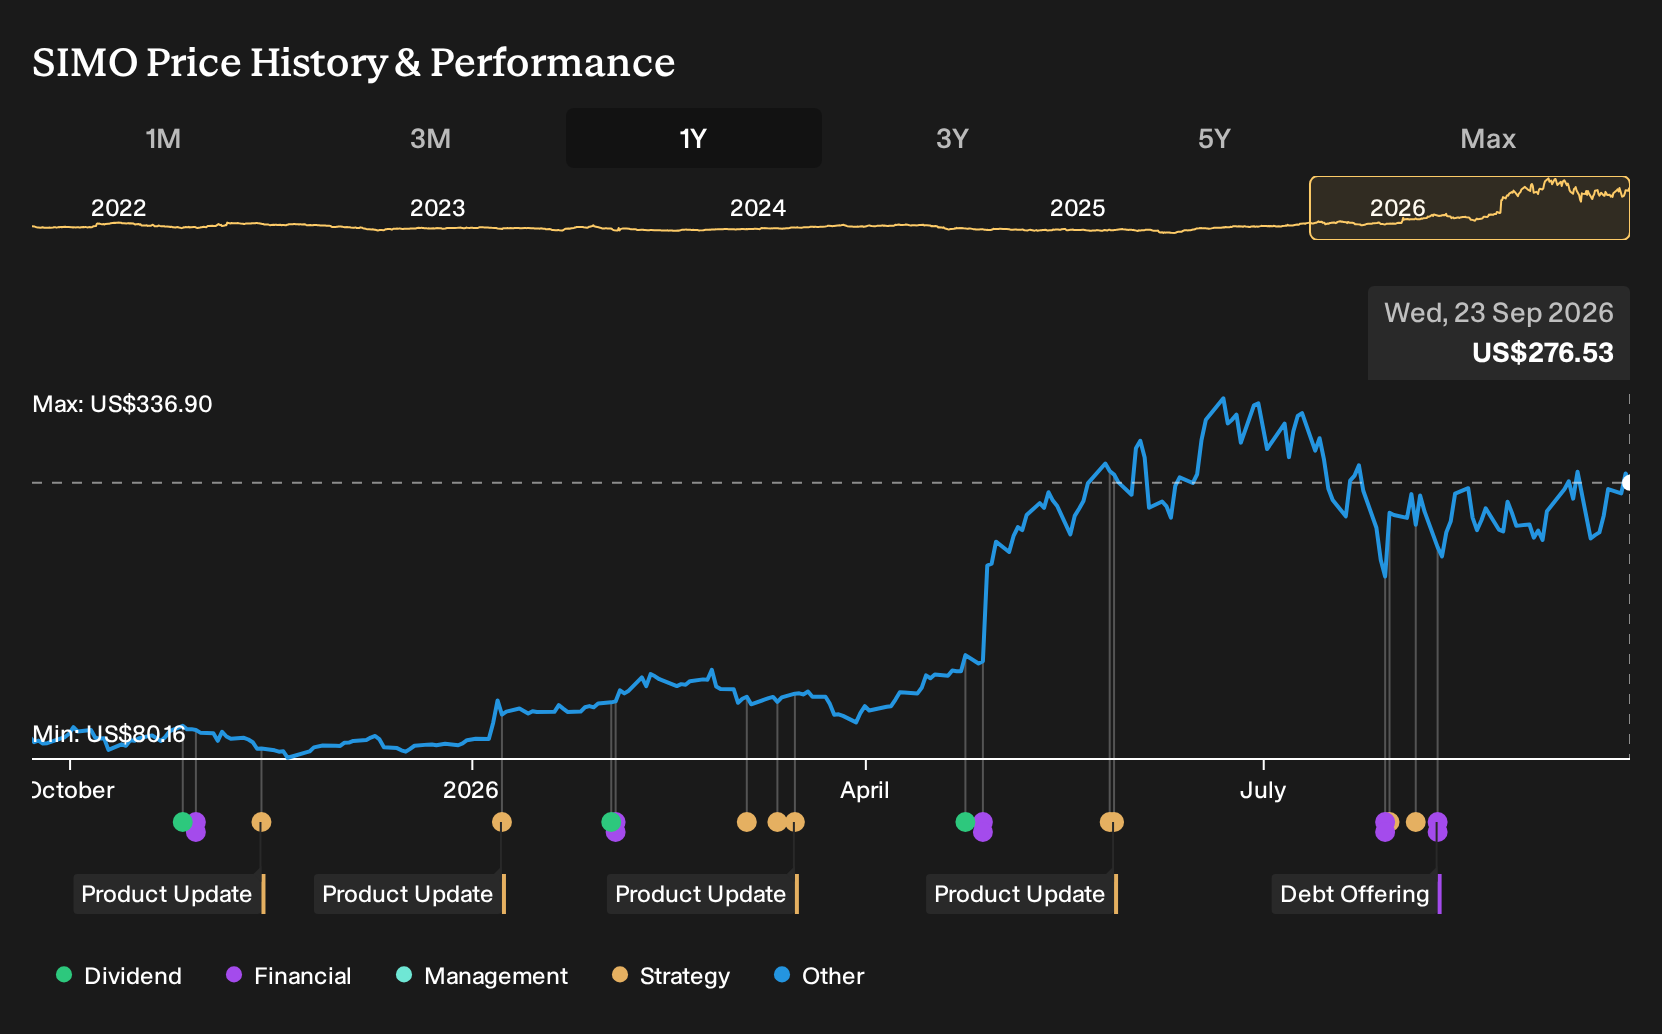
Uncover why Silicon Motion Technology's fair value indicates a 34% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Geopolitical risk is where the lowest Silicon Motion Technology forecasts really bite. That bearish group was only penciling in about US$2.6b of revenue and US$609.8 million of earnings by 2029, compared with higher consensus figures. Those estimates came before this AI focused forum update, so treat them as one side of a debate and explore both narratives.
Explore 5 other Silicon Motion Technology fair value estimates, including one that suggests as much as 43% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Silicon Motion Technology research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Silicon Motion Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Silicon Motion Technology's overall financial health at a glance.
Looking for more investment ideas beyond Silicon Motion Technology?
Once you have a view on Silicon Motion Technology, it helps to compare it with other opportunities that fit different risk, income, and balance sheet profiles. The Simply Wall St Screener can quickly surface stocks that match the kind of portfolio role you want a position to play.
- If you are hunting for early stage opportunities with strong fundamentals, consider casting a wide net across 9 elite penny stocks with strong financials that have already passed basic quality filters.
- For readers who care most about price versus business quality, you can focus on companies that combine cash generation with balance sheet strength by reviewing our curated 30 high quality undervalued stocks.
- If capital preservation and smoother return profiles matter more to you than aiming for the highest potential gains, focus your research on a 31 resilient stocks with low risk scores that screens for resilient financial traits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com