
Griffon (GFF) Stock May Trade At A 28% Discount To Cash Flow
Griffon has delivered a powerful multi year run, so the live question now is whether the current US$96.59 share price lines up with the cash the business is expected to generate. With the focus on its cash flows, the stock invites a closer look at how much future money the company may realistically return to shareholders.
- Over the past 5 years Griffon has returned about 375.7%, which puts a lot of pressure on the underlying cash flows to justify how far the stock has come.
- The group’s ability to turn operating profit into reliable free cash flow, and to fund its own investment needs, can heavily influence how investors weigh that track record against what the business may produce next.
- Prefer to judge Griffon on earnings? See what Griffon's 19.9x P/E says about the price.
The issue now is whether Griffon’s current share price is well supported by the cash flows implied in its intrinsic value estimate from the Discounted Cash Flow (DCF) approach.
If you are weighing Griffon through the lens of its cash generation, it can help to compare it with other businesses screened for 30 high quality undervalued stocks.
Does Griffon Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on how much hard cash Griffon might produce for shareholders over time. On the latest twelve month numbers, the group generated roughly $245.9 million in free cash flow, which is the starting point for the valuation work.
Analysts feeding into this DCF expect Griffon’s free cash flow to grow from that base, with projections rising into the low to mid $300 million range within a few years, then tapering to slower growth in the next phase. That pattern assumes a business that keeps generating cash and does not rely on extreme expansion to support today’s US$96.59 share price. On these projections, the Discounted Cash Flow (DCF) model suggests the estimated intrinsic value sits meaningfully above where the stock trades now. Find out what Griffon could be worth using our Discounted Cash Flow (DCF) estimate.
The Griffon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Griffon pick up where the DCF puzzle leaves off by spelling out which paths for Griffon’s growth, profitability and earnings would need to hold for the shares to be worth materially more or materially less than today’s price, and linking each scenario to a specific mix of potential catalysts and risks so you can track over time which version of the story appears to be unfolding on the Community page.
One of the top community narratives on Griffon: 21% undervalued
"Disciplined capital allocation, demonstrated by aggressive share repurchases and consistent dividend growth, should lead to meaningful EPS growth and enhanced shareholder returns over time..."
Discover why this Narrative puts Griffon at 21% undervalued.
One more Griffon check that could change how you read the story
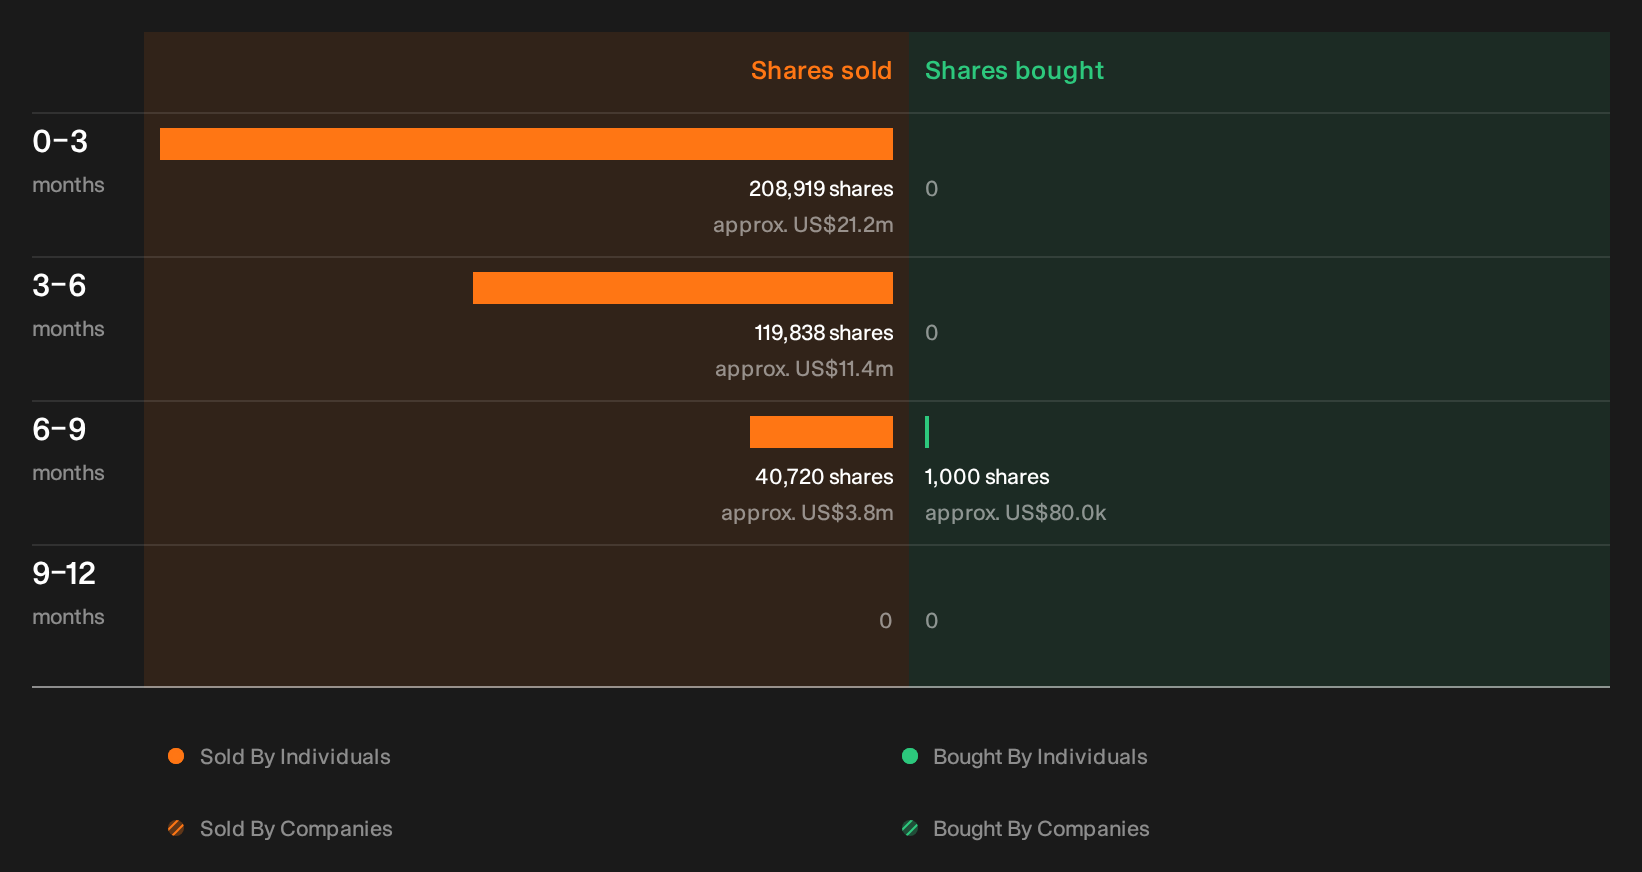
Griffon’s valuation work tells only part of the story, because recent share sales by people on the inside have been picked up by our checks and the who, how much and possible read throughs are still for you to review. See the recent insider selling flagged for Griffon.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com