
Can Fidelity National Information Services (FIS) Earnings Support Its Price After Record Wins?
Fidelity National Information Services has had a rough share price run in recent years, which puts fresh focus on one core issue for you as an investor. Are the earnings that underpin FIS today strong enough to support where the stock now trades?
- Over the past 5 years, the share price has fallen 67.9%, which raises the question of how closely the current valuation still lines up with the business earnings power.
- Recent wins in core banking contracts and recognition for FIS HORIZON and IBS platforms suggest the company may support its earnings profile with long term tech modernization projects at banks that can influence revenue visibility and profitability over time.
- Your read on Fidelity National Information Services is one view; the desks covering it have another. See what analysts think Fidelity National Information Services's shares could be worth.
The stock's next move may depend on whether the current price properly reflects what FIS earns today relative to that history and recent contract momentum.
If you are questioning whether Fidelity National Information Services’ earnings still justify its share price after a 5 year decline of 67.9%, it can help to compare that same earnings lens across 30 high quality undervalued stocks.
Does Fidelity National Information Services Look Undervalued on Earnings?
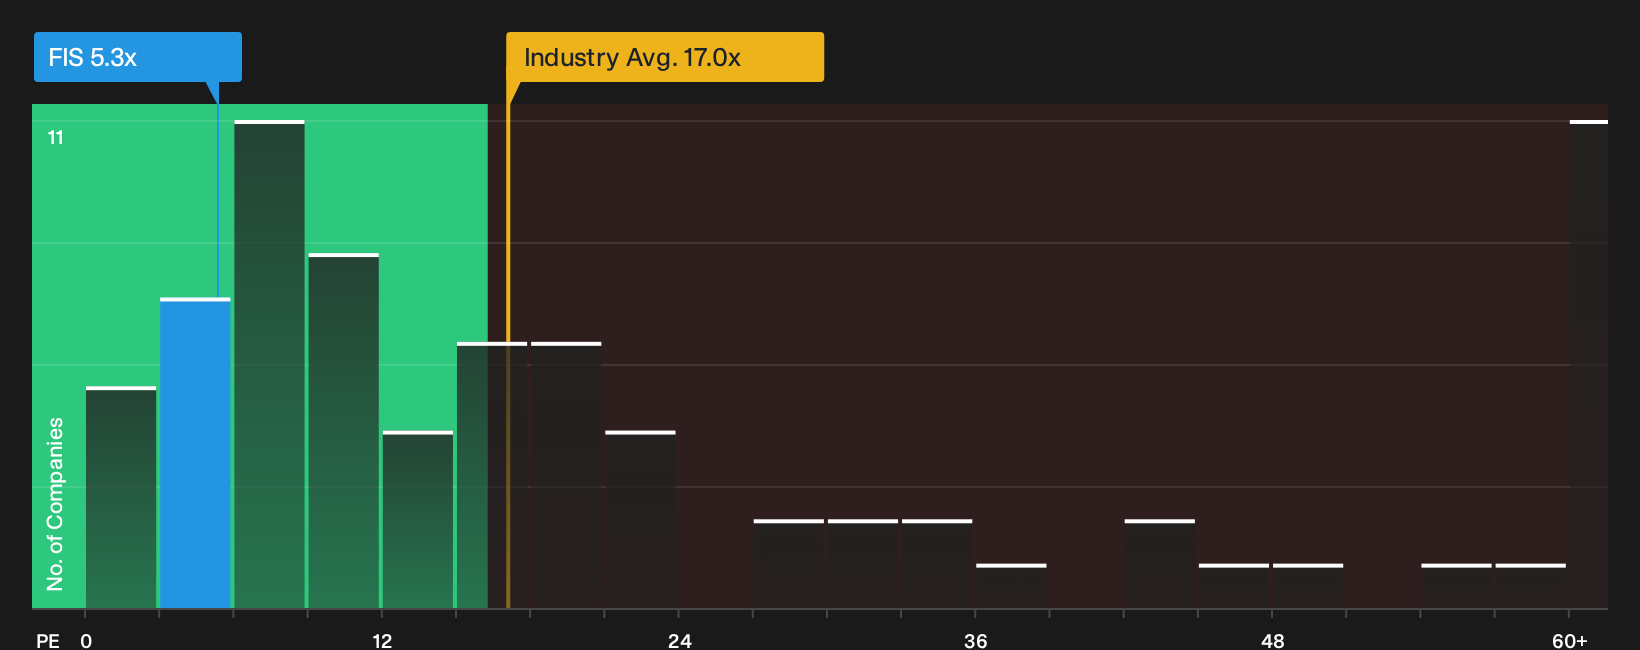
The P/E ratio works well for Fidelity National Information Services because earnings are a core focus for how this payments and banking technology group is valued. On that metric, the stock trades on about 5.3x earnings, which is well below both the Diversified Financial industry average of roughly 17.0x and a peer set closer to 28.0x. Based on the tailored fair multiple that factors in FIS’s growth profile, margins, size and risk, the current P/E sits below where you might normally expect it to trade, which points to the shares screening as undervalued on this framework.
Because recent contract wins in core banking and ongoing recognition for the HORIZON and IBS platforms have put more attention on the earnings base, this discount on a simple P/E view is especially important for anyone weighing how much of that pipeline is already reflected in the price. The gap between the present multiple and the fair benchmark is what the valuation tools are built to quantify in more detail. Explore the numbers behind Fidelity National Information Services's P/E valuation.
The Fidelity National Information Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Fidelity National Information Services pick up where the P/E puzzle leaves off, by mapping out what path for revenue, margins and earnings would need to play out for the share price to sit meaningfully above or below where it trades today on the NYSE. Instead of giving you a single valuation output, they describe the future that number relies on so you can track over time whether that story still matches how Fidelity National Information Services' business is actually developing. These Narratives are available on Simply Wall St's Community page.
One of the top community narratives on Fidelity National Information Services: 6% undervalued
"Fidelity National Information Services is a technology provider to banks and capital markets clients, focusing on core processing, digital banking and payments…"
Discover why this Narrative puts Fidelity National Information Services at 6% undervalued.
For Fidelity National Information Services, who is actually steering the ship?
Price ratios tell you what the market is willing to pay for Fidelity National Information Services today, but the real steering wheel sits with the people running it and how their pay is structured. See who runs Fidelity National Information Services and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com