
Pursuit Attractions And Hospitality (PRSU) Could Be 22% Undervalued On $50 Million Buyback
The fresh US$50 million share repurchase authorization at Pursuit Attractions and Hospitality (PRSU), combined with its recent rebrand from Viad Corp, has quickly reshaped how investors frame this travel experiences stock.
Recent trading has cooled after a strong run, with Pursuit Attractions and Hospitality’s share price giving up around 11% over the past 90 days. It still shows a 43.9% year to date share price return and a 3 year total shareholder return of 87.2%, which reflects building momentum rather than fading interest.
Position your Pursuit Attractions and Hospitality thesis alongside a curated group of potential value ideas by weighing its premium P/E and buyback against 30 high quality undervalued stocks in similar quality brackets.Pursuit Attractions and Hospitality now trades off its highs yet still carries a premium P/E and a fresh US$50 million buyback. Does that combination justify buying today, or is it better to wait for a cheaper entry point?
Most Popular Narrative: 22% Undervalued
On the prevailing narrative, Pursuit Attractions and Hospitality screens about 22% below an estimated fair value of $62, compared with the latest close at $48.08. This puts the recent buyback decision and premium P/E into a clearer context for anyone weighing upside against risk.
Significant long-term pipeline of organic reinvestment ("Refresh and Build" projects) and disciplined acquisition strategy (with financial flexibility for larger and smaller deals) provides opportunities to scale, drive operational leverage, and enhance earnings reliability and growth over multiple years.
See why 0 investors see Pursuit Attractions and Hospitality as 22% undervalued.
Result: Fair Value of $62 (UNDERVALUED)
Still, the Pursuit Attractions and Hospitality story rests on concentrated, experience-driven destinations where climate disruptions or higher capital needs could quickly challenge today’s upside narrative.
Find out about the key risks to this Pursuit Attractions and Hospitality narrative.
Another View: Pursuit Attractions and Hospitality On Richer Multiples
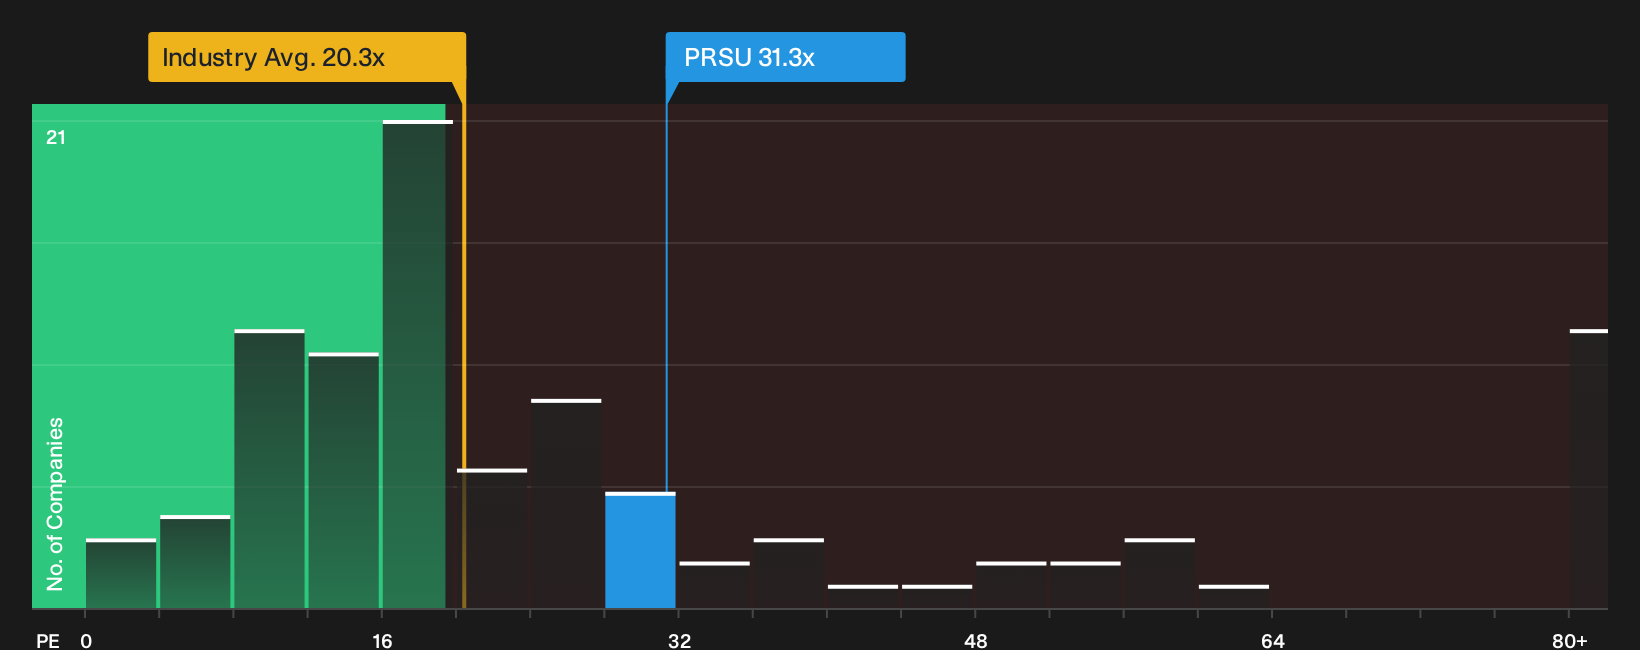
The story looks very different once you step away from that $62 fair value and focus on what investors currently pay for Pursuit Attractions and Hospitality’s earnings. The stock trades on a P/E of 31.3x versus 20.3x for the US Hospitality group and 19.3x for peers, while the fair ratio is 18x. That is a wide premium. It points to less margin for error if expectations slip, so how comfortable are you paying up for this experience-led model?
See what the numbers say about this price in our valuation breakdown, starting with the fair ratio comparison and relative P/E gap: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling optimistic about Pursuit Attractions and Hospitality, or leaning cautious after those rich multiples? Act quickly on your curiosity and weigh the potential yourself with 3 key rewards
Looking for more Pursuit Attractions and Hospitality style ideas?
Do not stop with Pursuit Attractions and Hospitality. Use the same energy you brought to this thesis to hunt for fresh opportunities before the crowd catches on.
- Chase underappreciated value stories and let the screener spotlight 30 high quality undervalued stocks hiding in plain sight.
- Prioritize resilience and protect your downside by zeroing in on a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions.
- Get ahead of the market by filtering for tomorrow's potential standouts using a focused 16 high quality undiscovered gems before interest builds.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com