
Saia (SAIA) Stock Still Carries An Earnings Premium After 44% Gain
Saia has delivered a 5 year return that many road freight operators would envy, and the stock now trades around US$343.85, which raises a simple question for investors who care about fundamentals. Is that price still in line with what the company is earning today.
- The share price is up 44.2% over 5 years, so anyone looking at Saia now is effectively being asked to pay a higher cumulative premium for its earnings than in the past.
- The business model leans on less than truckload operations and efficiency in its terminal network, which can influence how much profit it converts from every extra dollar of freight revenue and how dependable those earnings may be through a full cycle.
- Your read on Saia is one view; the desks covering it have another. See what analysts think Saia's shares could be worth.
For investors, the debate is whether Saia's current share price is adequately supported by what the company is earning today and what those earnings may reasonably deliver over time.
If you are weighing whether Saia's current earnings justify its valuation, it can help to compare that question across 30 high quality undervalued stocks.
Does Saia Look Pricey on Earnings?
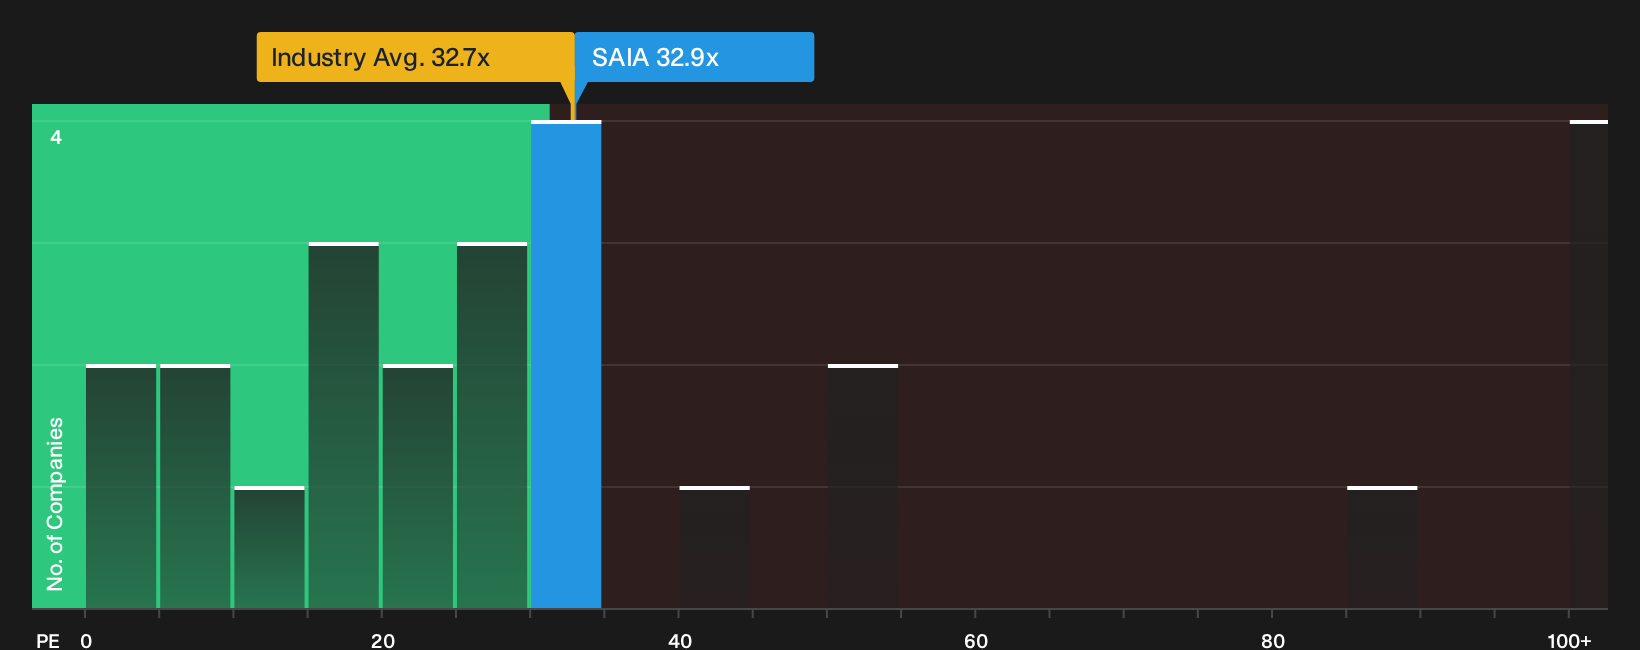
The P/E ratio is a useful lens for Saia because earnings sit at the center of how many investors frame transport stocks. On this measure, Saia trades at about 32.9x earnings, which is almost identical to the wider Transportation industry on roughly 32.7x. That puts the stock in the same broad valuation zone as the sector as a whole rather than at a steep discount or premium to typical listed freight operators.
The picture changes once you compare that multiple with what a tailored model suggests for Saia, which estimates a lower P/E would be more in line with its earnings power and risk profile. In other words, the current 32.9x sits above the level implied by those fundamentals, so the shares screen as overvalued on this framework rather than obviously cheap. For anyone considering Saia at today’s price, it is worth asking what earnings path or resilience would be needed to support paying that kind of earnings premium over time. Explore the numbers behind Saia's P/E valuation.
The Saia Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Saia valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the current share price to look meaningfully high or low relative to those scenarios, and they sit on the stock's Community page for investors who want to stress test their own thinking. Each narrative attaches a fair value to a particular path for Saia's potential catalysts and risks so you can see, over time, which story lines are actually playing out.
Community views on Saia pull in different directions, with one camp seeing more upside in the network build out and another more focused on the higher cost base.
Bull case: 22% undervalued
"The ongoing expansion and maturation of Saia's national terminal network, combined with network densification, is starting to unlock cost efficiencies and higher shipment volumes..."
Discover why this Narrative puts Saia at 22% undervalued.
Bear case: 10% overvalued
"The decision to lower the full year 2026 margin outlook to the bottom of the prior improvement range signals that start up costs and underabsorbed overhead from rapid build out may persist longer than expected..."
Explore why this Narrative puts Saia at 10% overvalued.
Saia's next chapter, what are professionals currently pencilling in
Valuation only tells you what Saia costs today, while the projections that analysts are building into their models offer a different lens on where this freight operator might be a few years from now. Explore where analysts expect Saia to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com