
How Campus Expansion At Huntington Ingalls Industries Has Changed Its Investment Story
- Huntington Ingalls Industries expanded its unmanned systems production campus in Pocasset, Massachusetts, adding 10,000 square feet to support higher output of REMUS underwater vehicles, ROMULUS surface vessels and Odyssey autonomy software for defense and commercial customers.
- The larger Pocasset facility deepens Huntington Ingalls Industries’ commitment to advanced maritime autonomy and to New England’s skilled workforce. It ties the company’s long-cycle shipbuilding activities to a growing portfolio of unmanned platforms used across defense, research and commercial applications.
- This article examines how Huntington Ingalls Industries’ expanded unmanned systems capacity in Pocasset may influence the broader investment narrative around autonomy.
Scan other defense and autonomy players moving on similar themes to Huntington Ingalls Industries by reviewing our hand picked 93 robotics and automation stocks.
Huntington Ingalls Industries Investment Narrative Recap
To own Huntington Ingalls Industries, you need to buy into a very long duration defense contractor that is slowly layering on higher tech work. The Pocasset expansion fits that story by giving Mission Technologies more room to produce REMUS and ROMULUS systems and integrate Odyssey software. This addition supports the idea that unmanned platforms can become a more meaningful part of the business mix over time.
In the shorter term, the key swing factor still sits with execution and timing on large ship and submarine programs, along with managing supply chain and labor pressures. The Pocasset news looks incremental relative to that main catalyst. It does not remove the existing risks around delays, cost control, or the balance sheet reliance on healthy operating cash flow.
The recent long lead material contract for aircraft carrier CVN 82 sits closest to the core Huntington Ingalls Industries story. It ties directly into the heavy capital base at Newport News and the need to keep that yard fully utilized. Early material procurement can help planning and scheduling, which matters for throughput and cost discipline on a multiyear build.
For you, that CVN 82 award connects to the same themes that run through the Pocasset expansion. The business is still anchored in large nuclear ships, while management adds unmanned and autonomy capabilities on top. Progress on big carrier and submarine milestones can influence confidence in future earnings, while any slippage would keep the focus on leverage, cash conversion and program execution risk.
Huntington Ingalls Industries' current analyst narrative points to US$15.3b in revenue and US$958.1m in earnings by 2029, based on an assumed 5.0% yearly revenue growth rate and an earnings increase of about US$297m from US$661.0m today.
Uncover why Huntington Ingalls Industries' fair value indicates a 36% potential upside to its current price, which could narrow quickly.
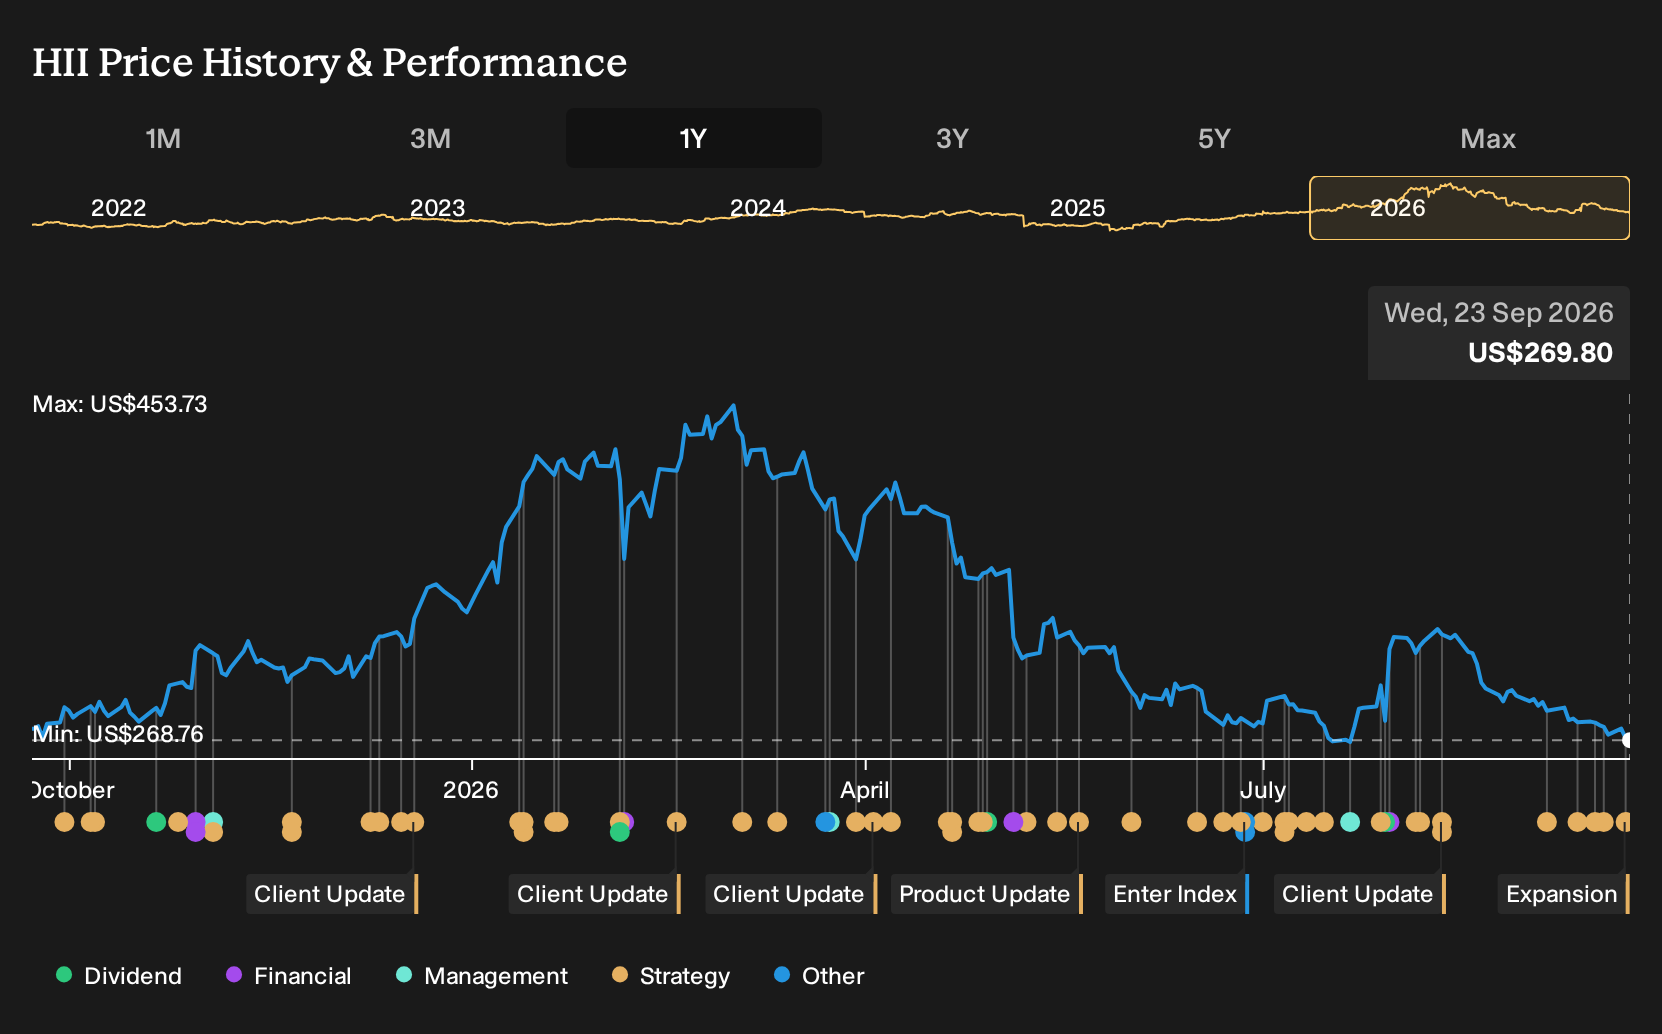
Exploring Other Perspectives
One alternate view puts far more weight on execution risk around unmanned systems. Those bearish analysts already had revenue expectations closer to US$15.2b and earnings around US$887.0m by 2029, compared with the higher consensus, even before this Pocasset expansion. You can treat today’s news as a live test of which narrative proves closer to reality.
Explore 4 other Huntington Ingalls Industries fair value estimates, including one that suggests it could be worth just $304.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Huntington Ingalls Industries research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Huntington Ingalls Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huntington Ingalls Industries' overall financial health at a glance.
Looking for more Huntington Ingalls Industries sized ideas?
If Huntington Ingalls Industries has you rethinking where autonomy and defense fit in your portfolio, it can help to line it up against a broader watchlist of potential opportunities. The Simply Wall St Screener lets you filter for traits that matter to you, then compare business quality, balance sheets and income streams in one place.
- For investors who put capital strength and resilience first, review a curated list of solid balance sheet and fundamentals (23 results) that can sit alongside Huntington Ingalls Industries as potential core holdings.
- If you prefer ideas where perceived risk is lower, scan a 31 resilient stocks with low risk scores that may better match a more defensive approach.
- Those hunting for lesser known prospects can review a 16 high quality undiscovered gems that might not yet be widely followed but still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com