
Agree Realty (ADC) Stock Looks About Right After New Debt Sale
Agree Realty has seen its stock lose some ground in recent weeks, even after a solid multi year run. This puts fresh focus on whether the current price still lines up with what the business earns. With investors also digesting a new debt financing, the key issue is how the earnings profile stacks up against what the market is now willing to pay.
- Over the past 3 years, Agree Realty has delivered a total return of about 38.8%, which makes it important to test whether that gain is fully supported by its earnings power today.
- The company recently priced US$400m of 5.650% senior unsecured notes due 2036, a move that can influence future interest costs and shape how much of its rental income ends up as earnings available to shareholders.
- The analysts covering Agree Realty have run their own numbers. See what analysts think Agree Realty's shares could be worth.
The issue now is whether Agree Realty's current share price near US$67.12 is justified by its earnings when set against the Fair Ratio benchmark.
If you want other reference points while you weigh Agree Realty against its earnings, a focused stock screen of 30 high quality undervalued stocks can give you more ideas to research.
Where Does Agree Realty Sit on Earnings?
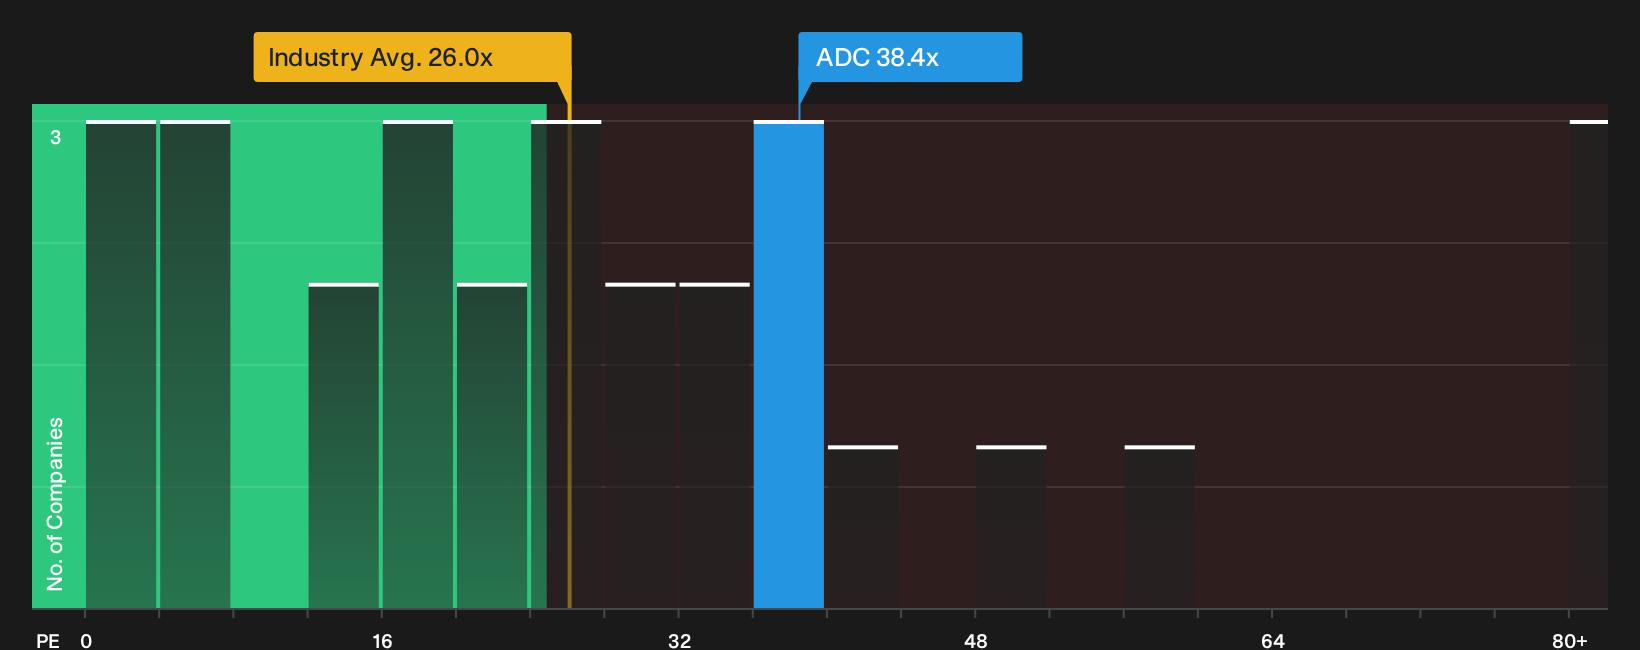
The P/E ratio is a useful way to think about Agree Realty because earnings stay front and center for a rental focused REIT. On this yardstick, the stock trades on roughly 38.4x earnings, compared with about 26.0x for the wider Retail REITs group and around 21.8x for its closer peer set. That puts Agree Realty at a clear premium to both its sector and its direct competitors.
Based on the Fair Ratio framework, which estimates the multiple you might expect given Agree Realty's size, margins and risk profile, the current P/E sits slightly above that benchmark yet not by a wide margin. On this measure, the valuation appears broadly in line rather than notably stretched or cheap. Because the business recently priced US$400m of 5.650% senior unsecured notes due 2036, investors also need to judge whether the earnings the market is capitalising at 38.4x can comfortably absorb the extra interest cost over time. Explore the numbers behind Agree Realty's P/E valuation.
The Agree Realty Narrative: What Would Justify Today's Price?
Agree Realty Narratives pick up where the valuation puzzle leaves off by explaining what kind of future for growth, margins and earnings would need to occur for the stock to be worth much more, or meaningfully less, than it is today. Each scenario on Simply Wall St's Community page treats Agree Realty's fair value as a specific thesis about the business that can be tracked over time rather than a one-off snapshot.
One of the top community narratives on Agree Realty: 20% undervalued
"Multiple dividend increases through 2026 to roughly US$3.20 per share on an annualised basis, alongside a 69 to 71% AFFO payout ratio..."
Discover why this Narrative puts Agree Realty at 20% undervalued.
One more Agree Realty check that belongs beside the numbers
Price multiples and debt terms only tell part of the story, because the people setting priorities and what they earn for doing it can tilt outcomes in ways the P/E alone never shows. See who runs Agree Realty and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com