
European Growth Stocks With Insider Ownership Up To 23%
The European markets have recently experienced volatility, driven by escalating tensions in the Middle East that have pushed energy prices higher, contributing to inflation concerns and influencing investor sentiment. Amid these fluctuations, investors often look for growth companies with high insider ownership as potential opportunities, believing that substantial insider stakes can align management's interests with shareholders and potentially indicate confidence in the company's future prospects.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| MilDef Group (OM:MILDEF) | 10.3% | 32.5% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 58.6% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 41.1% |
| CD Projekt Red (WSE:CDR) | 35.2% | 50.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 29.8% |
Here's a peek at a few of the choices from the screener.
Altri SGPS (ENXTLS:ALTR)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Altri SGPS is a company that produces and sells cellulosic fibers both in Portugal and internationally, with a market cap of €972.32 million.
Operations: The company's revenue primarily comes from the production and commercialization of cellulosic fibers, amounting to €663.69 million.
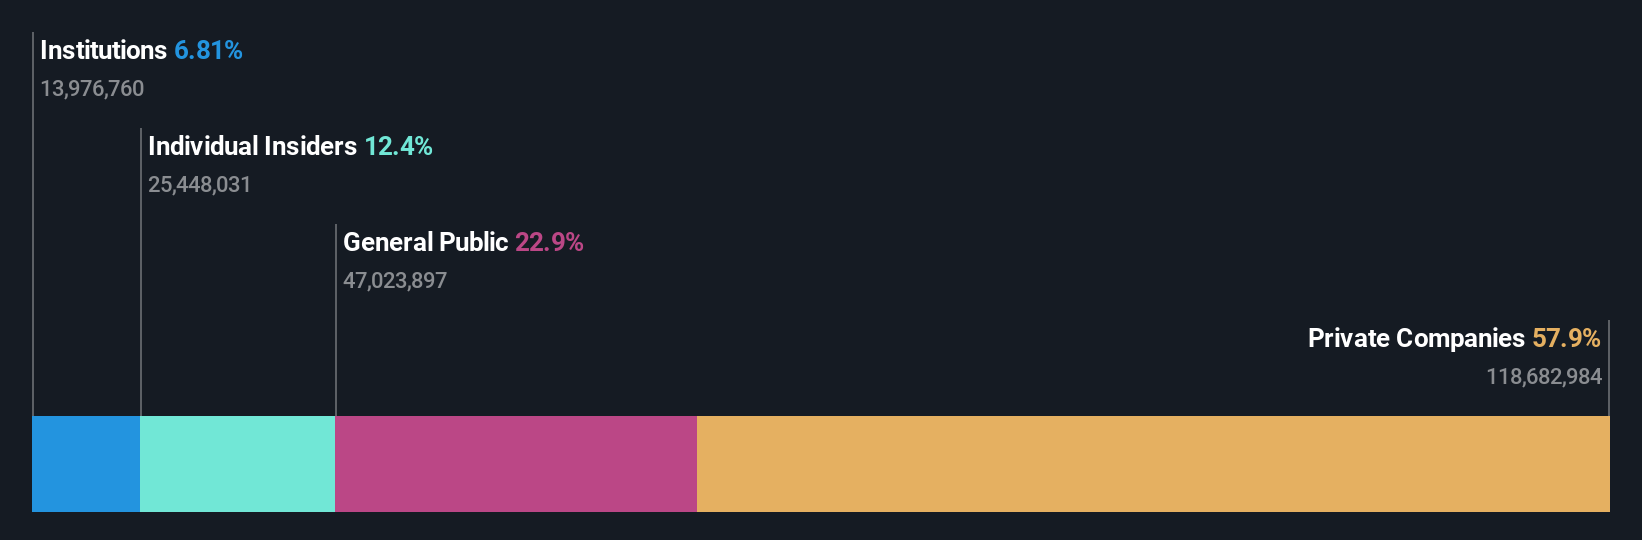
Insider Ownership: 12.4%
Altri SGPS shows strong growth potential with earnings expected to increase significantly at 36.1% annually, outpacing the Portuguese market. However, revenue growth is slower at 6.3% per year and profit margins have declined from last year. The company's stock trades well below its estimated fair value, offering potential upside despite financial challenges like insufficient operating cash flow coverage of debt and unsustainable dividends. Recent earnings reported mixed results with increased quarterly revenue but decreased six-month net income.
- Click to explore a detailed breakdown of our findings in Altri SGPS' earnings growth report.
- Our valuation report here indicates Altri SGPS may be overvalued.
P/F Bakkafrost (OB:BAKKA)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: P/F Bakkafrost, along with its subsidiaries, is involved in the production and sale of salmon products across North America, Western Europe, Eastern Europe, Asia, and other international markets; the company has a market cap of NOK26.60 billion.
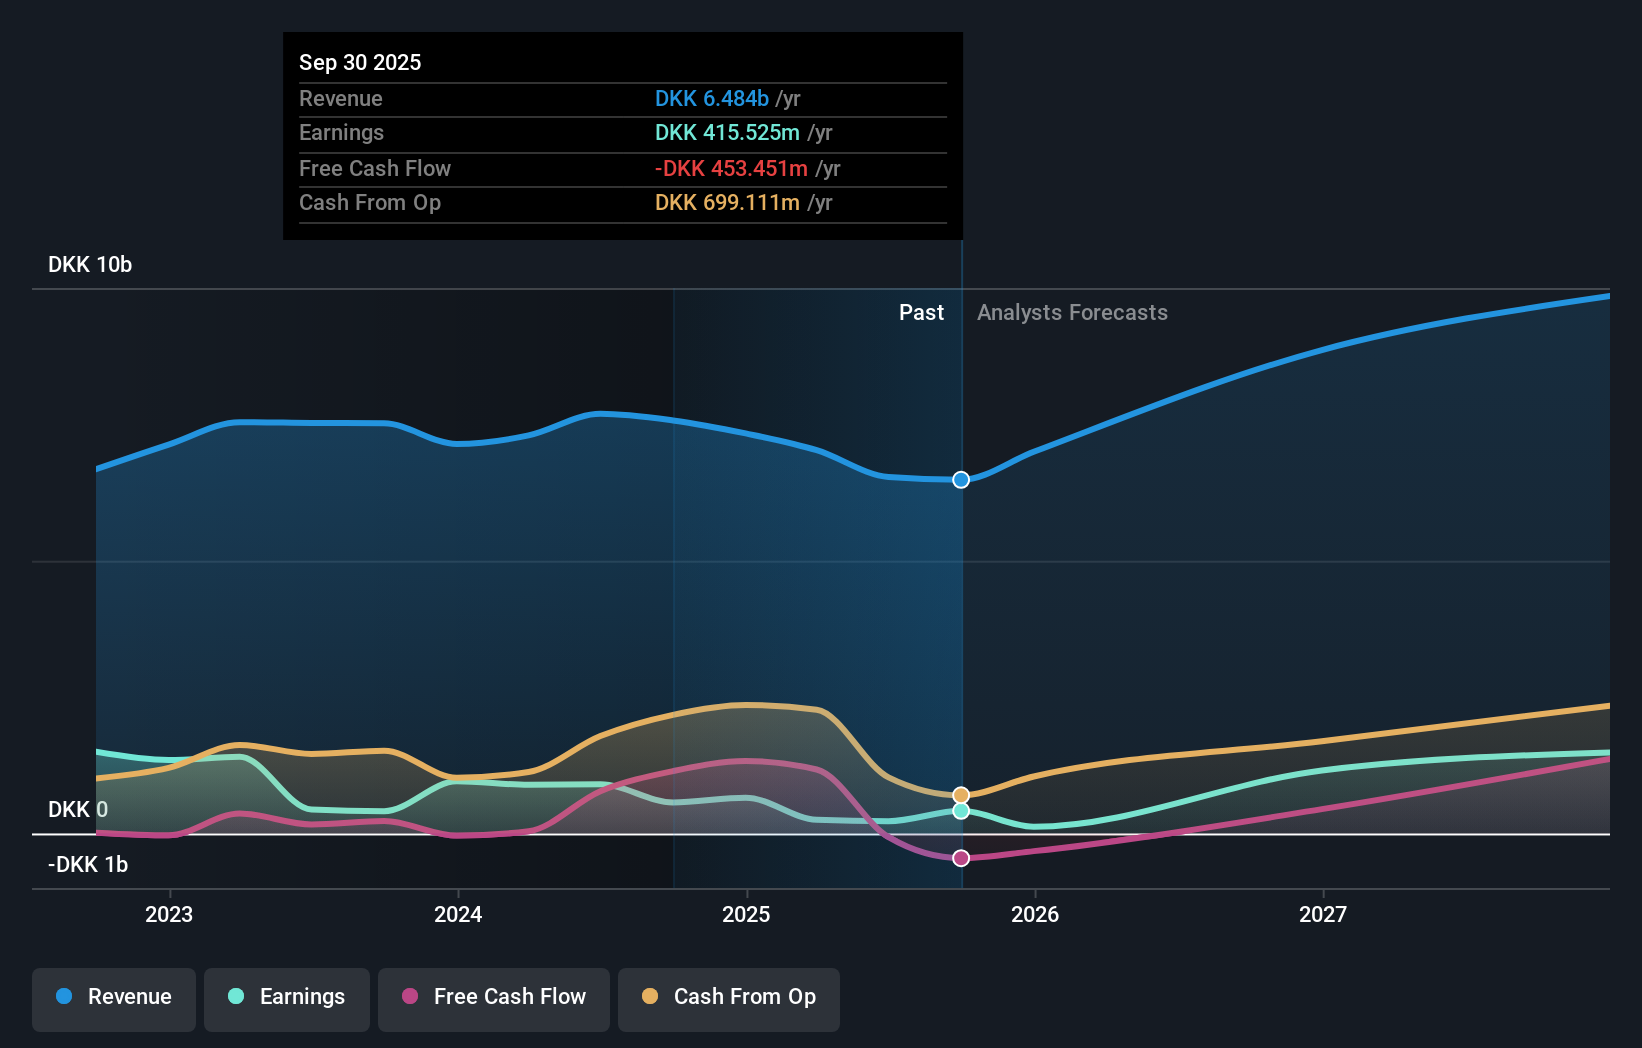
Operations: The company's revenue segments include Sales and Other (DKK11.54 billion), Farming Faroe Islands (DKK4.82 billion), Fishmeal, Oil and Feed (DKK2.58 billion), Services (DKK991.63 million), Freshwater Faroe Islands (DKK991.77 million), Farming Scotland (DKK902.43 million), and Freshwater Scotland (DKK245.80 million).
Insider Ownership: 23.9%
P/F Bakkafrost's earnings are expected to grow significantly at 36.3% annually, surpassing the Norwegian market average. Despite a slower revenue growth forecast of 13.2% per year, it remains above the market rate. The stock trades well below its estimated fair value, suggesting potential upside. Recent financials show increased sales but net losses for Q2 2026 compared to last year, and it was recently removed from the Oslo OBX Total Return Index.
- Take a closer look at P/F Bakkafrost's potential here in our earnings growth report.
- Insights from our recent valuation report point to the potential undervaluation of P/F Bakkafrost shares in the market.
Sdiptech (OM:SDIP B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Sdiptech AB (publ) offers technical services for infrastructures across various countries including Sweden, the United Kingdom, Germany, and the United States, with a market cap of SEK9.41 billion.
Operations: The company's revenue segments include Safety & Security (SEK456 million), Water & Bioeconomy (SEK907 million), Energy & Electrification (SEK1.16 billion), and Supply Chain & Transportation (SEK2.15 billion).
Insider Ownership: 12.2%
Sdiptech's earnings are forecast to grow 62.28% annually, with analysts agreeing on a potential 23.2% stock price rise, yet its Return on Equity is expected to be low at 12.5%. Trading at 53.6% below estimated fair value, recent insider activity shows more buying than selling without substantial volumes. Revenue growth is slower than desired but outpaces the Swedish market. Recent debt financing activities include issuing SEK 400 million in bonds and completing a tender offer for existing bonds.
- Navigate through the intricacies of Sdiptech with our comprehensive analyst estimates report here.
- In light of our recent valuation report, it seems possible that Sdiptech is trading behind its estimated value.

Where To Now?
- Investigate our full lineup of 213 Fast Growing European Companies With High Insider Ownership right here.
- Looking For Alternative Opportunities? AI is about to change healthcare. These 134 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com