
Tower Semiconductor (TSEM) Stock Looks Stretched On Its 8x Three Year Run
Tower Semiconductor has delivered a very strong share price run in recent years, which puts a spotlight on whether the current valuation still lines up with what its earnings can support. After such a move, the question for investors is how much of the story is already reflected in today's price.
- Over the past 3 years the stock has returned roughly 8x, so a lot of future profit expectations are now riding on the earnings picture.
- New high volume silicon photonics contracts linked to AI data center demand can shape how investors think about Tower Semiconductor's future earnings power and the stability of that profit stream.
- Your read on Tower Semiconductor is one view; the desks covering it have another. See what analysts think Tower Semiconductor's shares could be worth.
The issue now is whether the current share price is justified by Tower Semiconductor's earnings when set against the Fair Ratio benchmark.
If you want to stress test this same earnings versus price question beyond Tower Semiconductor, it is worth scanning 85 AI infrastructure stocks.
Does Tower Semiconductor Look Pricey on Earnings?
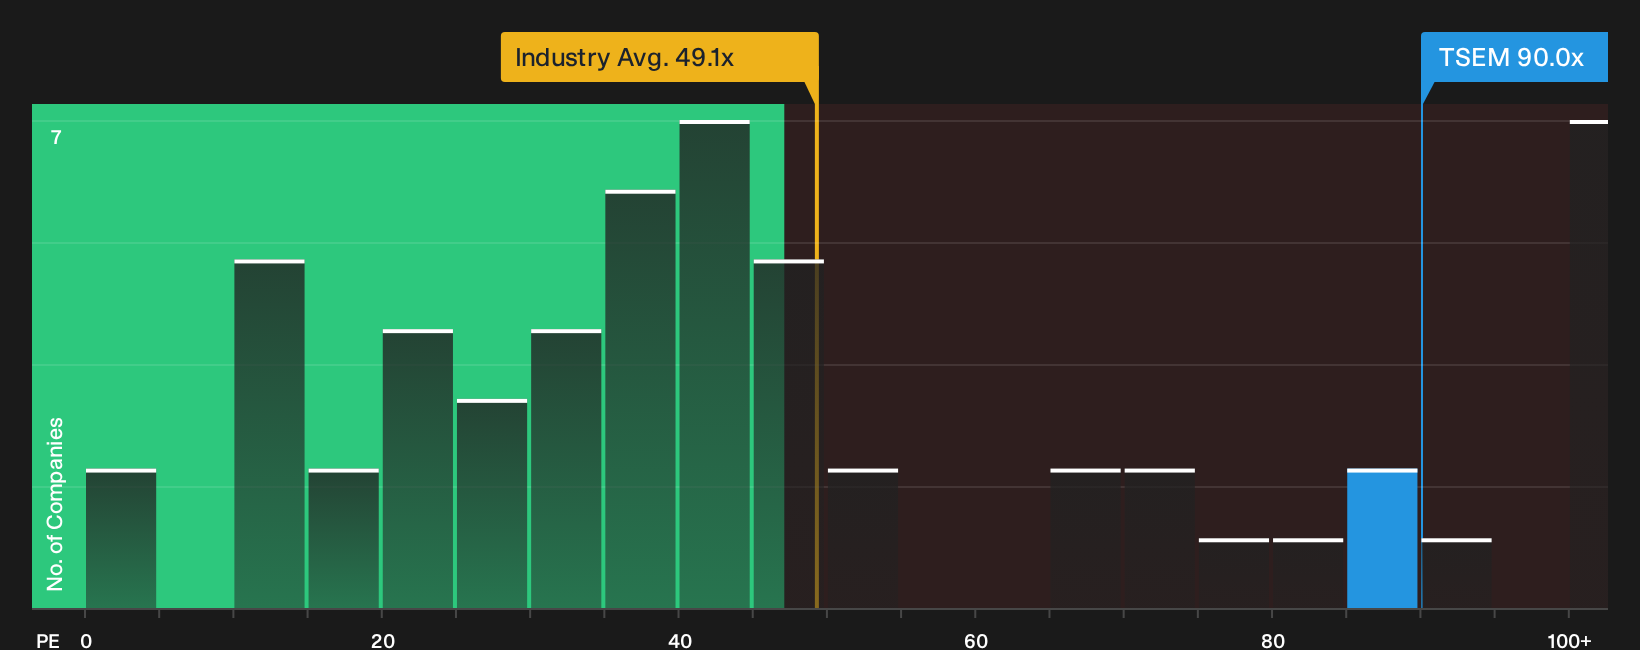
The P/E ratio is a useful lens for Tower Semiconductor because earnings are central to how investors frame its AI related silicon photonics contracts. Tower Semiconductor trades on a P/E of about 90.0x, which is materially higher than the Semiconductor sector average near 49.1x and above peers around 48.9x. That puts a heavy price tag on each dollar of current earnings compared with many other chip producers.
The Fair Ratio model, which blends factors like the firm's margins, expected cash flow path, size and risk profile, indicates that Tower Semiconductor's P/E sits above the level that framework would usually flag for this type of business. As a result, the stock screens as overvalued on earnings. Because the AI photonics contracts already total roughly US$1.3b of business, a lot of optimism around that pipeline is likely embedded in this premium multiple. Explore the numbers behind Tower Semiconductor's P/E valuation.
The Tower Semiconductor Narrative: What Would Justify Today's Price?
Narratives for Tower Semiconductor pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price, and they sit on Simply Wall St’s Community page as structured scenarios. Rather than rely on a single multiple or model, each one lays out the assumptions behind its fair value so you can compare those expectations with future results as they are reported.
One of the top community narratives on Tower Semiconductor: 27% undervalued
"Accelerating demand for data center, AI, and 5G infrastructure is driving increased adoption of Tower's Silicon Photonics and Silicon Germanium solutions..."
Discover why this Narrative puts Tower Semiconductor at 27% undervalued.
One more Tower Semiconductor check before you close the tab
Price tags and profit stories only go so far if you do not know who is steering Tower Semiconductor or how their incentives are structured, and that unanswered piece can meaningfully shape the risk you are taking. See who runs Tower Semiconductor and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com