
Is Automatic Data Processing (ADP) Undervalued As Hiring Data Stays Firm?
Automatic Data Processing (ADP) is back in focus after fresh figures from its NER Pulse showed U.S. private employers adding an average of 20,000 jobs per week in early September.
Despite the fresh NER Pulse data, Automatic Data Processing’s recent trading has cooled. The 30-day share price return is down 6.83% and the 7-day move is also lower, even after a stronger 21.90% 90-day share price return and a 5-year total shareholder return of 47.71% that points to longer term momentum now fading at the margin.
Capitalize on the hiring pulse that Automatic Data Processing tracks by scanning for other employment and HR service stocks showing resilient cash generation in our curated list of solid balance sheet and fundamentals (23 results).Automatic Data Processing still looks like a high quality payroll and HR platform, even after the recent share pullback. The question now is whether that strength is already fully reflected in the current price.
Most Popular Narrative: 8% Undervalued
On the most widely followed view, Automatic Data Processing carries a fair value of $287.60 against a last close of $263.68, which frames the latest pullback as a modest discount rather than a broken story.
Adoption of Next Gen products such as Lyric HCM and Workforce Now Next Gen, together with continued uptake of global payroll and WorkForce Suite, is now showing in Employer Services bookings of more than US$2.2b in fiscal 2026 and a 94% rise in live Lyric clients. This supports future revenue and earnings growth as these contracts are implemented and ramp into the income statement.
See why 109 investors see Automatic Data Processing as 8% undervalued.
Result: Fair Value of $287.60 (UNDERVALUED)
Still, the bullish Automatic Data Processing story could wobble if PEO margins stay pressured by higher medical and workers compensation costs, or if new AI driven HR platforms intensify price competition.
Find out about the key risks to this Automatic Data Processing narrative.
Another View: What ADP’s P/E Is Telling You
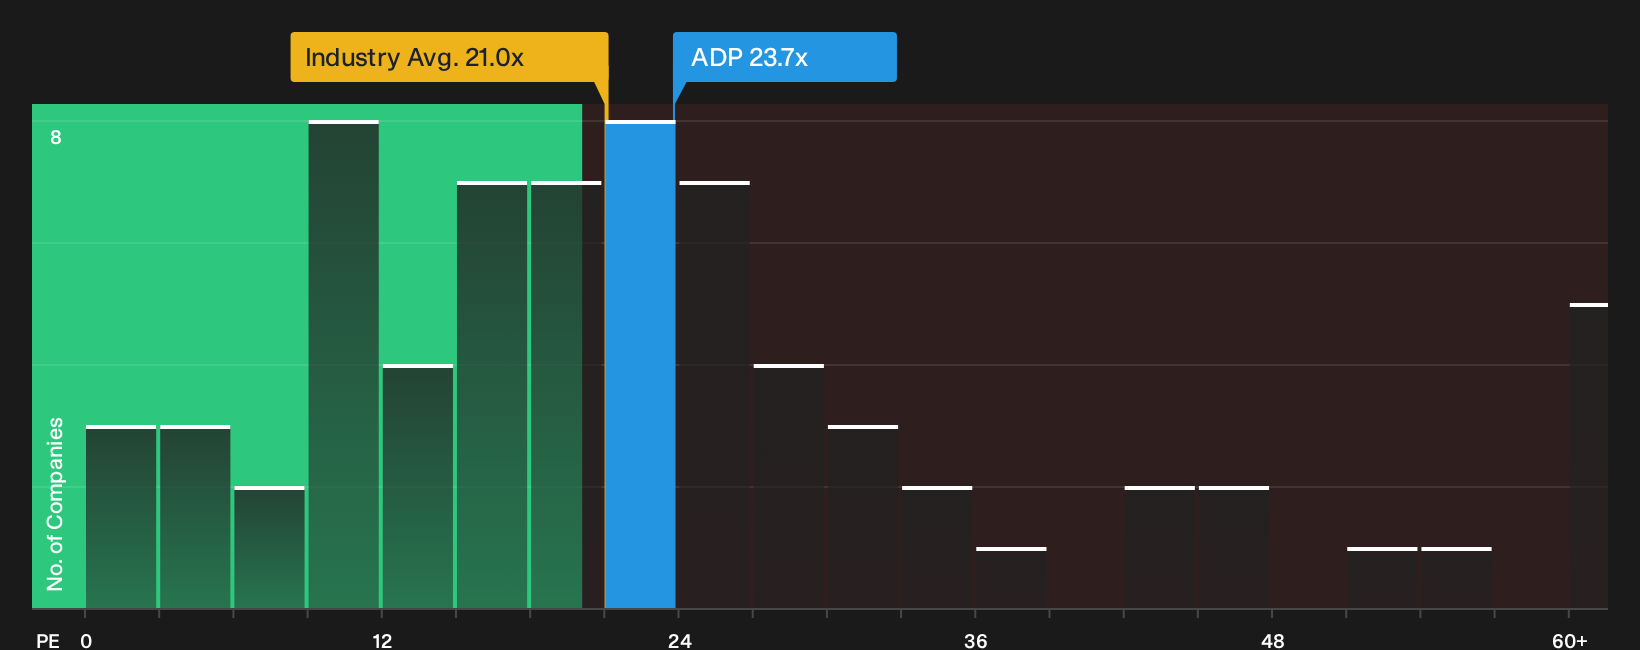
The analyst narrative frames Automatic Data Processing as modestly undervalued, yet the market multiple tells a tougher story. ADP trades on a P/E of 23.7x, above both the US Professional Services sector at 21x and its peer average of 19.6x, even though the fair ratio sits higher at 26.9x.
That gap means the stock already carries a premium price tag versus similar businesses, while still sitting below the fair ratio the market could move towards. For investors, the question is simple: Does that premium feel like a cushion or a margin of risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Automatic Data Processing is constructive but not unanimous, so take a moment to test the assumptions against the underlying data and decide quickly where you stand by reviewing the 3 key rewards
Looking for more investment ideas beyond Automatic Data Processing?
If you stop with Automatic Data Processing, you only see one angle. Broaden your watchlist now and you give yourself more options when the market shifts.
- Target stronger downside protection by checking out resilient companies in the 31 resilient stocks with low risk scores that may help steady your portfolio when volatility picks up.
- Hunt for mispriced quality by scanning the 30 high quality undervalued stocks, where solid fundamentals meet prices that the market has not fully caught up with yet.
- Spot future leaders early by reviewing the 16 high quality undiscovered gems and see which lesser known businesses already show robust financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com