
How PhotonLink Launch At Coherent Stock Has Changed Its Investment Story
- Coherent launched PhotonLink in September 2026, an integrated optics platform that combines lasers, silicon photonics, specialty fibers and optical modules for AI datacenters, spanning CPO, NPO and emerging chip to chip connectivity.
- The PhotonLink rollout, backed by more than ten CPO and more than ten NPO customer engagements plus expanded InP and fiber capacity, points to Coherent tying its internal manufacturing buildout directly to complex AI datacenter demand.
- This report examines how Coherent's AI datacenter investment narrative is shaped by the PhotonLink platform launch and customer traction.
Scan beyond Coherent and compare PhotonLink's AI datacenter angle with other potential beneficiaries across 85 AI infrastructure stocks in the same build out wave.
Coherent Investment Narrative Recap
To own Coherent, you need to believe its datacenter and communications engine can justify heavy investment and a rich P/E while industrial and materials remain choppier. The big short term swing factor is how quickly AI optics orders translate into higher capacity utilization and product mix that supports margins rather than just volume.
The main operational risk is that intense competition in high speed optics and customer concentration blunt that margin story just as Coherent ramps PhotonLink and 6 inch InP capacity. If PhotonLink adoption is slower or pricing more aggressive than hoped, the financial impact from these capital projects could be less attractive.
The PhotonLink launch is the clearest operational bridge between Coherent's AI datacenter story and its current manufacturing build out. Management is tying compound semiconductors, silicon photonics, specialty fiber and modules into one platform that can feed CPO, NPO and chip to chip projects, all from the same internal supply chain.
For investors watching catalysts, PhotonLink's more than ten CPO and more than ten NPO customer engagements, plus several chip to chip programs, matter because they give some visibility against the risk of underutilized InP and fiber capacity. Execution risk does not disappear, but the platform helps connect capital intensity to specific datacenter programs.
Coherent Forecasts Behind the PhotonLink Buildout
Coherent's narrative links PhotonLink, expanded InP capacity and AI datacenter demand directly to a set of aggressive consensus numbers. Analysts are assuming revenue will grow by 39.2% a year over the next 3 years, which is a steep climb for any hardware focused group tied to capex cycles. The story is not just about top line either, since projections also call for profit margins to move from 10.8% today to 18.3% over the same period as the mix tilts toward higher value optics and away from lower margin activities.
Coherent's narrative projects US$19.2b revenue and US$3.5b earnings by 2029. This implies 39.2% yearly revenue growth and an earnings increase of about 4.5x from US$769.9m today.
For investors tracking PhotonLink, those earnings today of US$769.9m and the US$3.5b target by 2029 frame how much financial uplift the AI datacenter cycle is expected to carry. The implied rise in margins from 10.8% to 18.3% assumes the integrated platform and internal manufacturing push do more than fill factories. They are expected to improve the economics of each unit sold. That ties the capital spend on 6 inch InP, silicon photonics and specialty fiber directly to a much richer earnings profile, not just higher shipment counts.
Valuation expectations sit on top of those operating forecasts. Consensus points to Coherent reaching US$19.2b in revenue and US$3.5b in earnings by 2029 while trading on a P/E of 36.8x, compared with 68.3x today and an industry P/E of 29.2x. At a current share price of US$268.64, the average analyst target of US$415.36 implies 35.3% upside, bracketed by a bullish US$500 and a cautious US$280. The gap between those end points shows how differently analysts weigh PhotonLink execution, capital intensity and AI optics pricing.
Uncover why Coherent's fair value indicates a 38% potential upside to its current price that could narrow quickly.
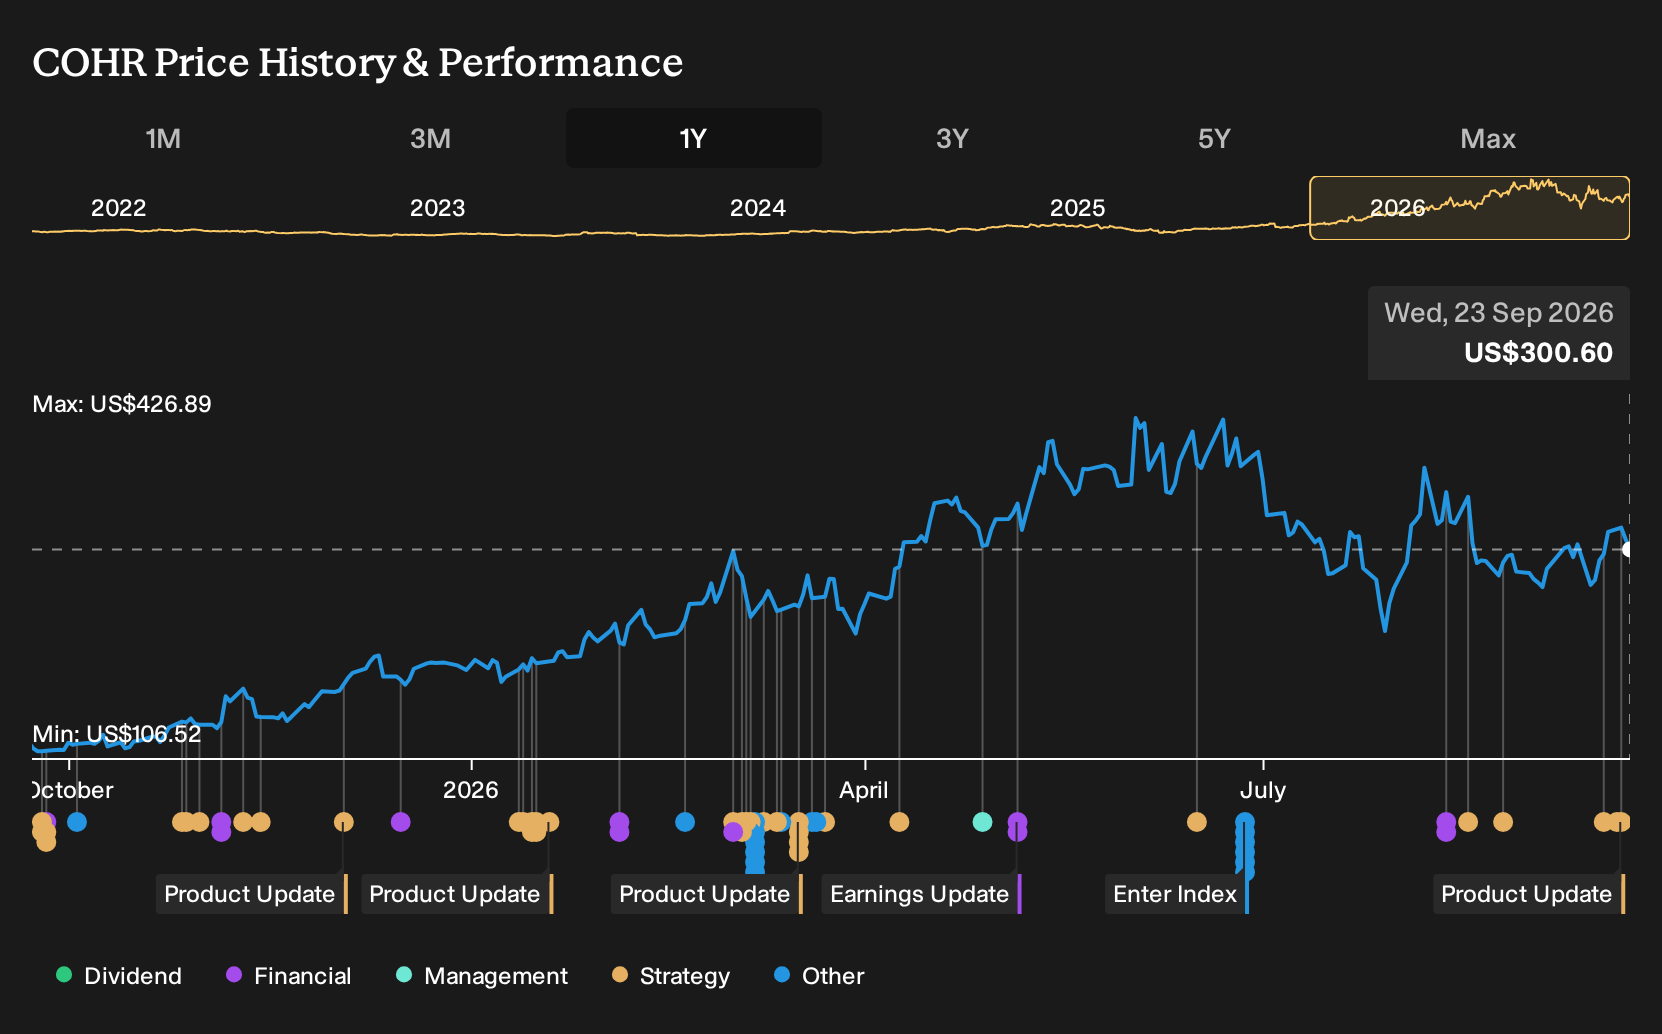
Exploring Other Perspectives
PhotonLink turns that debate up a notch. The most cautious Coherent watchers worry less about competition and more about a future capacity overbuild, which is why their price targets around US$320 rest on revenue of about US$18.5b and roughly US$3.6b in earnings by 2029. Those estimates, set before this launch, could shift meaningfully. It makes sense for you to weigh several viewpoints rather than lock onto one story.
Explore 4 other Coherent fair value estimates, including one that suggests it could be worth just $415.36!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Coherent research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Coherent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coherent's overall financial health at a glance.
Looking for more investment ideas beyond Coherent?
Once you have a view on Coherent and its PhotonLink story, it can help to cross check that thesis against other potential opportunities using the Simply Wall St Screener.
- For investors hunting for mispriced quality, compare Coherent's setup with a curated line up of 30 high quality undervalued stocks that pair solid fundamentals with more modest expectations.
- If income is a priority, balance Coherent's AI upside with a stream of potential cash returns from a focused group of 7 dividend fortresses that may better fit an income oriented plan.
- For those who care most about resilience, set Coherent alongside a 31 resilient stocks with low risk scores to see how it stacks up against businesses that score strongly on stability and risk controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com