
Global's Top Undervalued Small Caps With Insider Action In September 2026
As the global markets navigate a landscape marked by mixed performances in major U.S. stock indexes and evolving geopolitical tensions, small-cap stocks have been under particular pressure, with the Russell 2000 Index lagging behind its larger counterparts. Amidst this backdrop of interest rate hikes and fluctuating oil prices, investors are keenly observing how these dynamics impact smaller companies, which often present unique opportunities when coupled with insider activity. In such an environment, identifying promising small-cap stocks involves looking for those that demonstrate resilience and potential growth despite broader market volatility.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| China Aircraft Leasing Group Holdings | 7.2x | 1.0x | 36.29% | ★★★★★☆ |
| Transcontinental | 2.4x | 0.2x | -97.65% | ★★★★☆☆ |
| Franchise Brands | 27.5x | 2.0x | 47.05% | ★★★★☆☆ |
| Trifast | NA | 0.5x | 15.42% | ★★★★☆☆ |
| Saniona | 7.4x | 3.2x | 30.24% | ★★★★☆☆ |
| Diversified Royalty | 25.2x | 10.0x | 46.65% | ★★★☆☆☆ |
| Eurocell | 23.9x | 0.3x | 45.97% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 21.66% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -224.19% | ★★★☆☆☆ |
| Mattr | 41.8x | 1.0x | 43.82% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
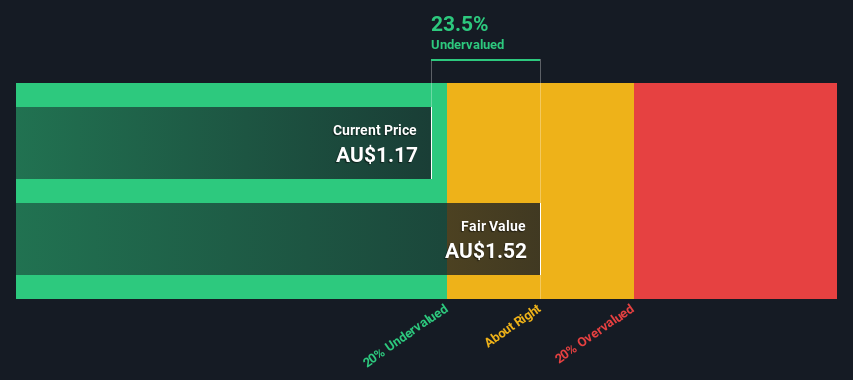
Storage King Group (ASX:SKG)
Simply Wall St Value Rating: ★★★★★☆
Overview: Storage King Group operates in the self-storage industry, providing rental and merchandising services, with a market capitalization of A$2.36 billion.
Operations: The company generates revenue primarily from rental and merchandising activities, with the latest reported revenue at A$247.53 million. Cost of goods sold (COGS) is a significant expense, amounting to A$54.44 million in the most recent period. Notably, the net income margin has experienced fluctuations, reaching 0.62% in the latest report after peaking at over 1% in earlier periods due to changes in non-operating expenses.
PE: 9.1x
Storage King Group, a small-cap company, recently reported full-year earnings with sales at A$224.67 million and revenue at A$247.42 million, showing stability compared to the previous year. However, net income fell significantly to A$154.32 million from A$289.05 million due to large one-off items impacting results. Despite insider confidence through recent share purchases, earnings are expected to decline by 5% annually over the next three years while revenue is forecasted for modest growth of 7.08%. The company faces challenges with high-risk external borrowing and interest payments not well covered by earnings but remains a player in its sector under new leadership with CEO Nikki Lawson since July 2026.
- Navigate through the intricacies of Storage King Group with our comprehensive valuation report here.
Altra Fastigheter (OM:ALTRA)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Altra Fastigheter is a real estate company engaged in property management and development across its segments Kielo, Bratsberg, and Altra Sweden with a focus on the Nordic region, and it has a market cap of approximately SEK 1.5 billion.
Operations: The primary revenue streams for Altra Fastigheter are derived from its segments: Kielo, Bratsberg, and Altra Sweden, with Altra Sweden contributing the largest share. The company experienced fluctuations in its financial performance over recent periods, notably in net income margin which varied significantly. Gross profit margin showed a trend of improvement reaching 69.44% by September 2024. Operating expenses have been relatively stable compared to significant variations in non-operating expenses impacting overall profitability.
PE: 16.1x
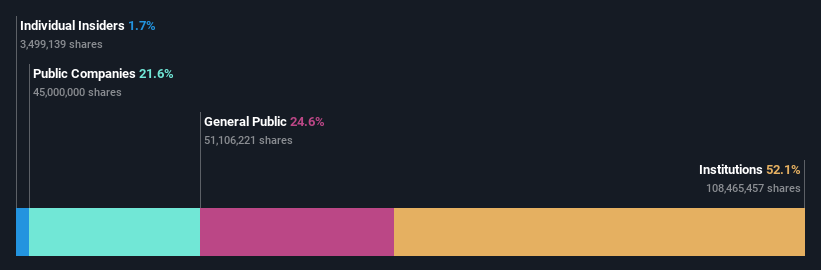
Altra Fastigheter, a smaller company in its sector, recently reported improved financial performance for the second quarter of 2026. With sales reaching SEK 813 million and net income climbing to SEK 122 million from a loss last year, the company's earnings per share also turned positive. Insider confidence is evident as they have increased their share purchases recently. Despite relying solely on external borrowing for funding, Altra's earnings are projected to grow annually by 17.76%, suggesting potential future growth opportunities.
- Delve into the full analysis valuation report here for a deeper understanding of Altra Fastigheter.
Understand Altra Fastigheter's track record by examining our Past report.
Allied Properties Real Estate Investment Trust (TSX:AP.UN)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Allied Properties Real Estate Investment Trust focuses on owning, managing, and developing urban office environments primarily in major Canadian cities, with a market capitalization of CA$2.94 billion.
Operations: The company's primary revenue streams are derived from its operations in Toronto & Kitchener, Montréal, Vancouver, and Calgary. Over recent periods, the gross profit margin has shown a notable decline from 57.11% to 10.45%. Operating expenses have fluctuated but remained a significant portion of costs alongside non-operating expenses, which have notably increased in recent periods.
PE: -0.7x
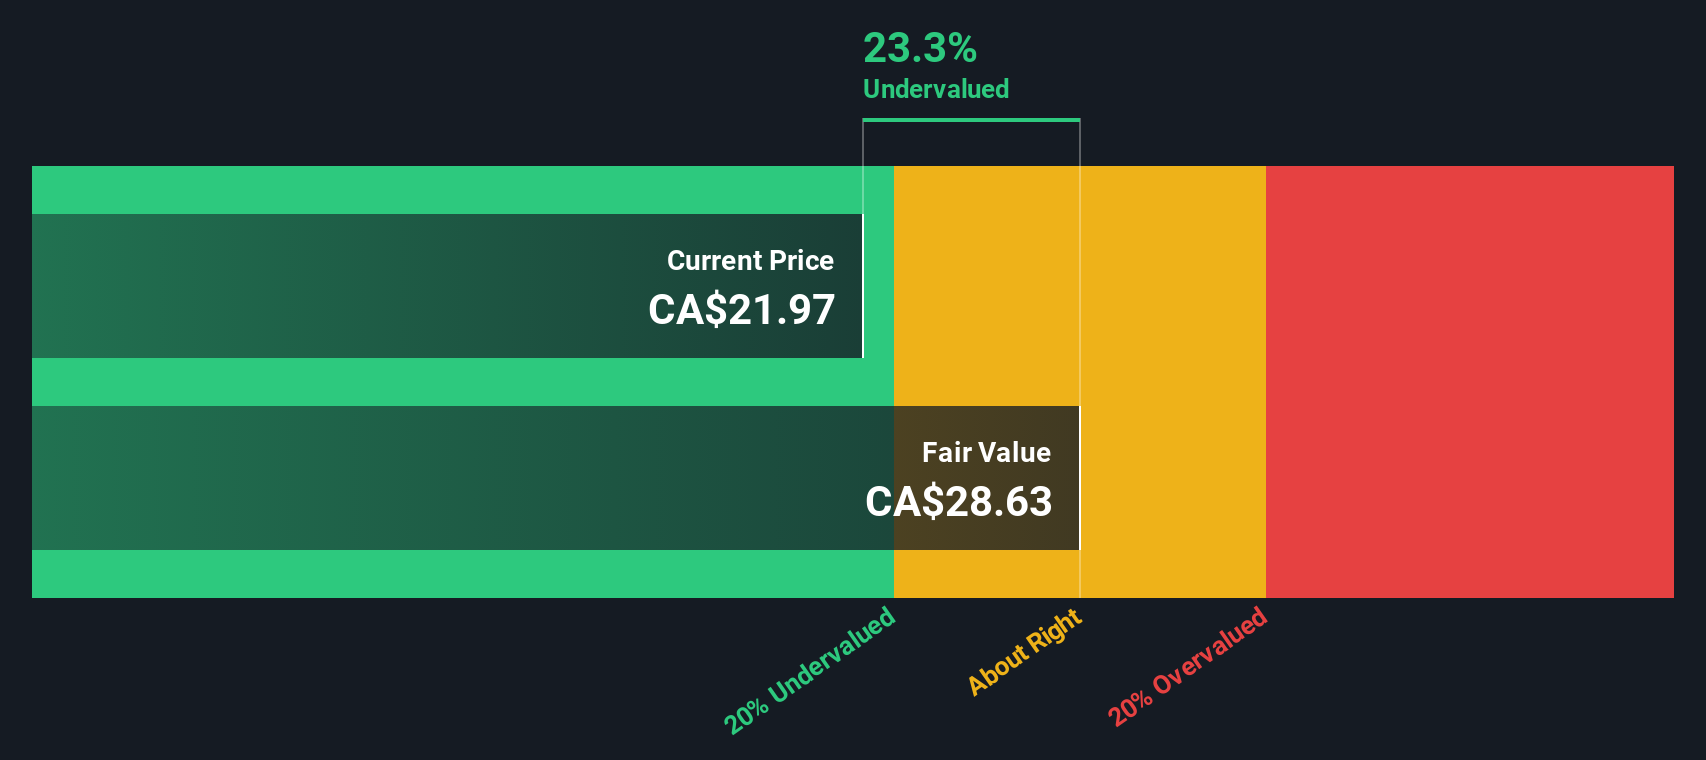
Allied Properties REIT, a smaller entity in the real estate sector, faces challenges with external borrowing as its primary funding source. Despite this, they maintain regular monthly distributions of C$0.06 per unit, totaling C$0.72 annually. Recent earnings show a notable net loss of C$744.7 million for Q2 2026, compared to the previous year’s loss of C$94.74 million. Insider confidence is evident from recent share purchases within the last few months, suggesting potential optimism about future growth prospects despite current financial hurdles.
Make It Happen
- Unlock more gems! Our Undervalued Global Small Caps With Insider Buying screener has unearthed 116 more companies for you to explore.Click here to unveil our expertly curated list of 119 Undervalued Global Small Caps With Insider Buying.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com