
Global Growth Stocks With Strong Insider Ownership
In recent weeks, global markets have experienced a mix of volatility and resilience, with growth stocks outpacing value in the U.S. amid fluctuating oil prices and interest rate hikes by central banks. As investors navigate these uncertain conditions, companies with strong insider ownership often stand out due to the confidence their leaders have in their long-term potential.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meitu (SEHK:1357) | 23% | 26.9% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's explore several standout options from the results in the screener.
Haci Ömer Sabanci Holding (IBSE:SAHOL)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Haci Ömer Sabanci Holding A.S. operates in the finance, manufacturing, and trade sectors both in Turkey and internationally through its subsidiaries, with a market cap of TRY191.34 billion.
Operations: The company's revenue is primarily derived from its banking segment at TRY806.04 billion, followed by energy at TRY343.84 billion, material technologies at TRY144.85 billion, financial services at TRY75.59 billion, and digital operations contributing TRY5.14 billion.
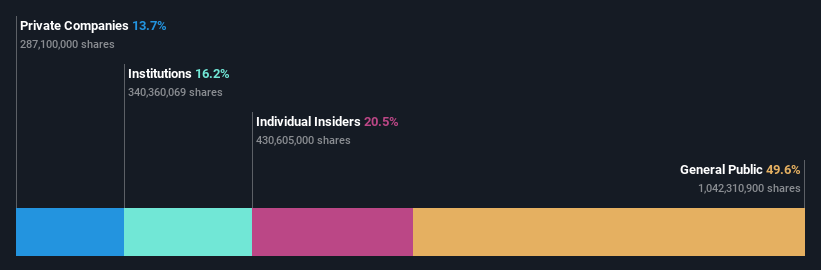
Insider Ownership: 20.7%
Revenue Growth Forecast: 50.5% p.a.
Haci Ömer Sabanci Holding demonstrates strong growth potential with expected annual earnings and revenue growth rates of 35.6% and 50.5%, respectively, surpassing the Turkish market averages. Recent earnings reports show a significant increase in net income to TRY 14,160.08 million for Q2 2026 from TRY 2,313.54 million a year ago, highlighting improved profitability. Despite these positive trends, its dividend yield of 3.29% may not be well covered by current or forecasted earnings.
- Navigate through the intricacies of Haci Ömer Sabanci Holding with our comprehensive analyst estimates report here.
- The analysis detailed in our Haci Ömer Sabanci Holding valuation report hints at an deflated share price compared to its estimated value.
Shanghai Aiko Solar EnergyLtd (SHSE:600732)
Simply Wall St Growth Rating: ★★★★★★
Overview: Shanghai Aiko Solar Energy Co., Ltd. focuses on the research, development, manufacture, and sale of photovoltaic products in China, with a market capitalization of CN¥22.74 billion.
Operations: Shanghai Aiko Solar Energy Co., Ltd. generates revenue primarily through its photovoltaic products, serving the Chinese market.
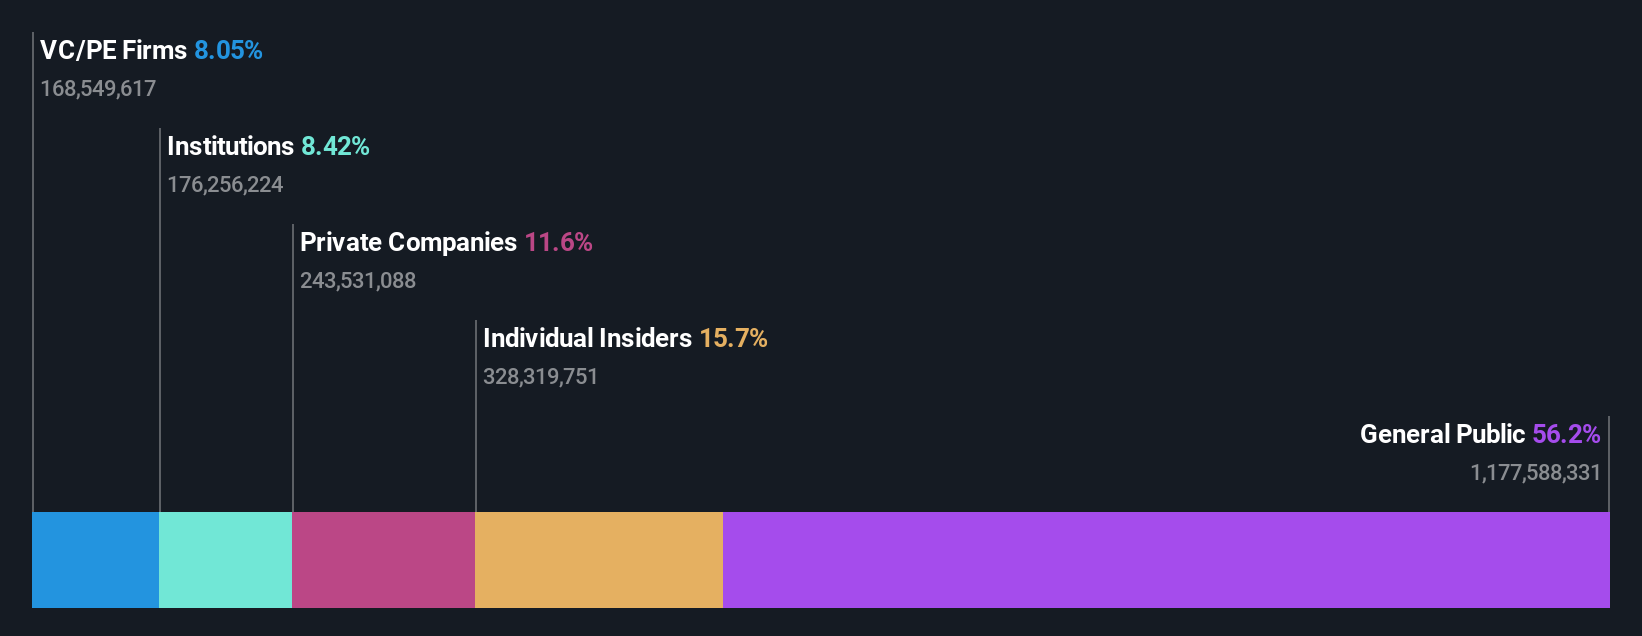
Insider Ownership: 15.8%
Revenue Growth Forecast: 26.4% p.a.
Shanghai Aiko Solar Energy Ltd. is poised for significant growth, with revenue projected to grow at 26.4% annually, outpacing the Chinese market average of 17.5%. Despite reporting a net loss of CNY 753.65 million for H1 2026, the company is forecasted to achieve profitability within three years and exhibit a high return on equity of 24.8%. The stock trades at a good value relative to peers, enhancing its appeal despite recent financial setbacks.
- Get an in-depth perspective on Shanghai Aiko Solar EnergyLtd's performance by reading our analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Shanghai Aiko Solar EnergyLtd shares in the market.
Hydsoft TechnologyLtd (SZSE:301316)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Hydsoft Technology Co., Ltd. provides professional information technology services both in China and internationally, with a market capitalization of CN¥16.06 billion.
Operations: Unfortunately, the revenue segments for Hydsoft Technology Ltd (ticker: SZSE:301316) were not provided in the text. Therefore, I am unable to summarize them for you.
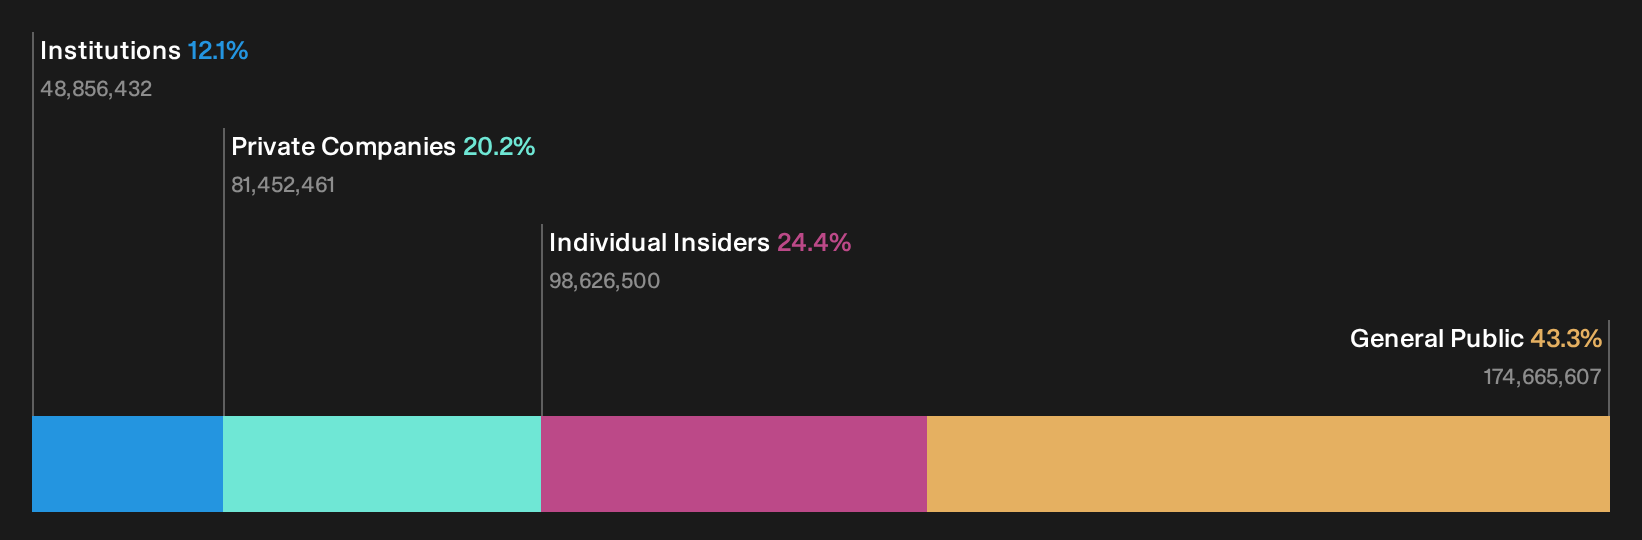
Insider Ownership: 24.4%
Revenue Growth Forecast: 23.7% p.a.
Hydsoft Technology Ltd. exhibits strong growth potential, with revenue expected to increase by 23.7% annually, surpassing the Chinese market average of 17.5%. Despite a highly volatile share price and earnings growth projected at 25.68% per year—slightly below the market's pace—the company's recent half-year results show significant improvement in net income from CNY 5.65 million to CNY 19.46 million, highlighting its capacity for substantial earnings expansion amidst insider ownership stability.
- Unlock comprehensive insights into our analysis of Hydsoft TechnologyLtd stock in this growth report.
- Upon reviewing our latest valuation report, Hydsoft TechnologyLtd's share price might be too optimistic.
Taking Advantage
- Take a closer look at our Fast Growing Global Companies With High Insider Ownership list of 721 companies by clicking here.
- Ready To Venture Into Other Investment Styles? The latest GPUs need a type of rare earth metal called Dysprosium and there are only 36 companies in the world exploring or producing it. Find the list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com