
How Investors Are Reacting To Arlo Technologies (ARLO) AI Security Service Launch
- Arlo Technologies recently launched Arlo Secure 7, adding AI-driven Threat Assessment, Arlo Summary recaps, and an optional 24/7 video recording plan across its Early Warning System tiers.
- The service refresh emphasizes security value in software and subscriptions, which is important for Arlo Technologies as it focuses more on recurring service revenue and higher-margin plans.
- We will now see how Arlo Technologies' investment narrative could evolve as Threat Assessment extends its security platform further into software.
Arlo Technologies Investment Narrative Recap
For a shareholder in Arlo Technologies, the core belief is that its connected hardware can keep feeding higher value software plans, so subscription and services revenue do more of the heavy lifting over time. The Arlo Secure 7 launch fits that story by expanding the feature set inside existing tiers, which may help keep users engaged in the ecosystem.
The key near term catalyst still sits in execution on subscriber additions and migration into richer AI powered plans. The biggest immediate risk is that hardware margins stay under pressure from commoditization while consumer appetite for recurring fees or upgrades slows. In that case, new features would have limited financial impact.
The Threat Assessment feature inside Arlo Secure 7 looks most relevant for the current thesis. It turns cameras and sensors from a passive alert system into one that can automatically trigger actions, including contacting a live Safety Agent and escalating to monitoring centers, while pushing through mute and do not disturb settings for urgent notifications.
For catalysts, that sort of always on response product may help Arlo Technologies keep differentiating its higher tier Secure plans, which links directly to average revenue per user and service margins. The operational risk is that rivals match or outdo this functionality or undercut pricing. In that scenario, the AI features would be less effective as a driver of upgrades.
Arlo Technologies Analyst Assumptions And Valuation Setup
Analysts framing Arlo Technologies around its software heavy future are tying the story to a slow and steady revenue path. Consensus expectations point to revenue rising at about 4.7% each year over the next three years, with profit margins modeled to move from 5.5% today toward 7.8% over that period. Earnings in these scenarios reach about US$50.3 million by 2029, compared with current earnings of roughly US$30.6 million, and that gap leaves plenty of room for disagreement across the analyst set.
The spread in forecasts matters for anyone treating Arlo Technologies as an AI and subscription platform rather than just a hardware vendor. The most optimistic view assumes earnings of US$78.2 million by 2029, while the most cautious forecast sits closer to US$41.0 million, so the range is wide even before factoring in execution risk on Secure 7 and Threat Assessment. Analysts also assume the share count grows by a little over 4% a year, which can dilute per share metrics if operating performance does not bridge the gap.
On top of those earnings and margin inputs, the analyst framework leans on a relatively high valuation multiple to make the numbers work. The current P/E is cited at about 47.0x. The implied 2029 P/E is lifted to 67.1x on the consensus earnings line, above the 33.1x multiple quoted for the broader US electronic peer group. That kind of step up in valuation expectations can be as important to the narrative as any Secure tier upgrade or AI feature rollout.
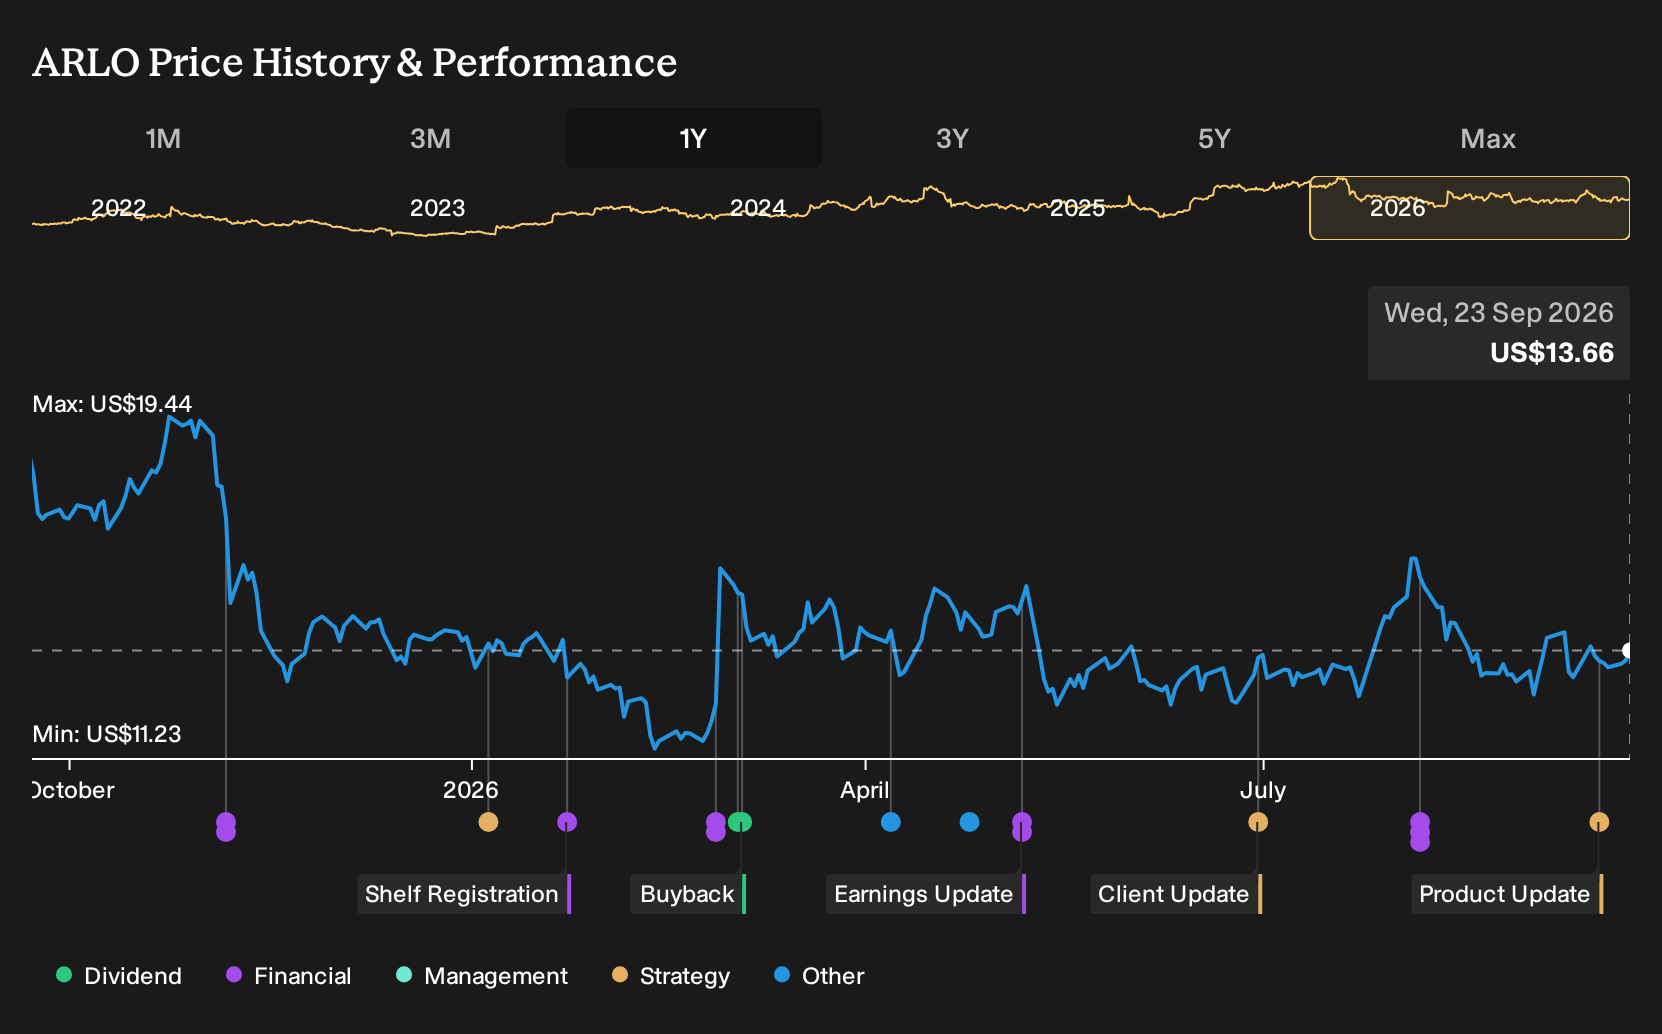
Those same assumptions feed into headline targets for Arlo Technologies over the next few years. The consensus price target sits at US$21.40 a share, versus a spot price of US$13.25, with the most bullish analyst at US$24.00 and the most cautious at US$19.00. To line up with that view you would need to be comfortable with revenues reaching about US$643.1 million and earnings landing at US$50.3 million in 2029, while also accepting that the stock could trade on a premium P/E and that an 8.8% to 8.84% discount rate is a fair way to bring those future cash flows back to today.
Arlo Technologies' narrative projects US$643.1 million revenue and US$50.3 million earnings by 2029. This is built on 4.7% yearly revenue growth and an earnings increase of about US$19.7 million from current earnings of US$30.6 million.
Uncover how Arlo Technologies' fair value indicates a 57% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community range from US$6 to about US$28.71, which spans deep discount territory through to valuations above current analyst targets. That spread sits against Arlo Technologies leaning harder into subscriptions and AI security features, so you can see how opinions may diverge sharply. Explore those alternatives before forming your own stance.
Explore 3 other Arlo Technologies fair value estimates, including one that indicates there could be as much as 110% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Arlo Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arlo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arlo Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Arlo Technologies?
If you want to balance your view on Arlo Technologies with a wider watchlist, the Simply Wall St Screener can help you sift for companies that match the kind of risk, quality, and income profile you prefer.
- For investors who want potential mispricings with solid fundamentals, review 30 high quality undervalued stocks that might warrant a closer look alongside Arlo Technologies.
- If capital preservation sits high on your priority list, consider using the screener to search through 31 resilient stocks with low risk scores that may offer a steadier ride.
- When income is the focus, balance your Arlo Technologies research by scanning 7 dividend fortresses that could complement a growth oriented portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com