
Should Delisting Notice Require Action From Hub Group (HUBG) Investors?
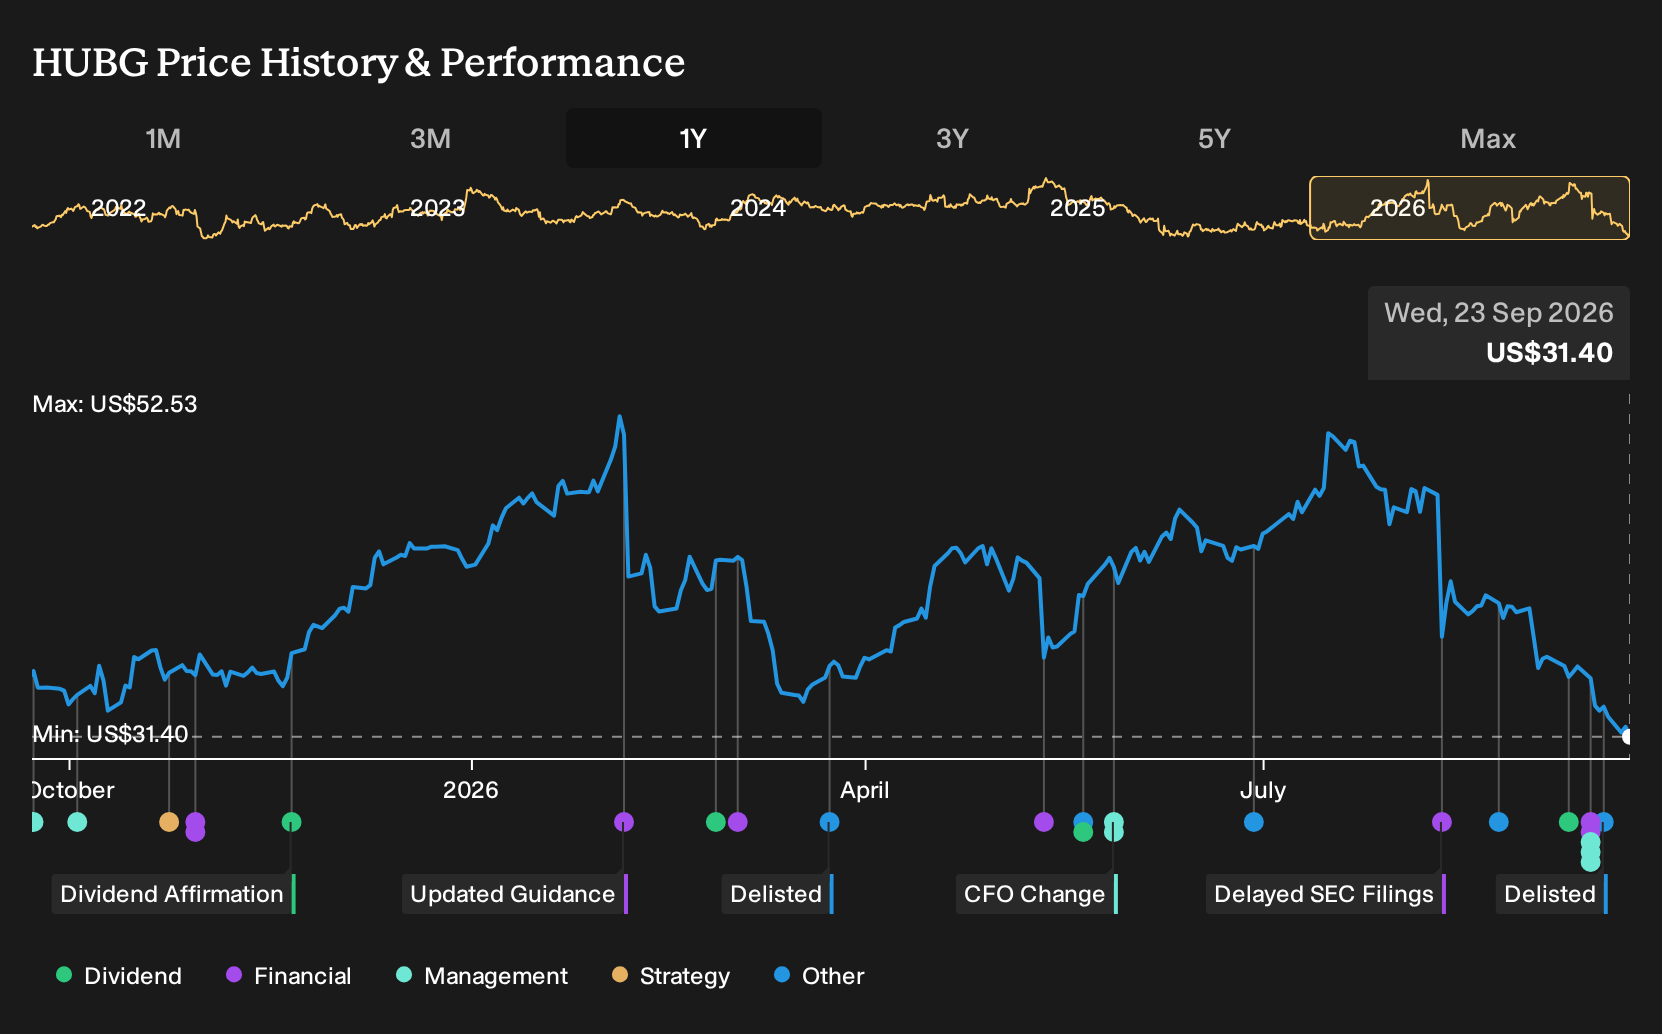
- Hub Group received a Nasdaq Staff Delisting Determination in September 2026 after missing multiple SEC filing deadlines, while also outlining 2026 revenue guidance of about US$3.6b to US$3.8b and amending its credit agreement to accommodate extended reporting timelines.
- The appointment of a new CFO, the return of David Yeager as CEO, and lender flexibility on EBITDA calculations point to a business focused on fixing accounting issues while keeping credit access and day to day logistics operations functioning.
- We will now look at how Hub Group's investment narrative could shift given the Nasdaq delisting risk tied to delayed financial filings.
Hub Group Investment Narrative Recap
To own Hub Group, you need to believe its intermodal and logistics platform can keep attracting freight volumes while customers increasingly want integrated, tech enabled supply chains. The big near term swing factor is simple: can the company keep operating with minimal disruption while working through late SEC filings and the Nasdaq appeal process?
The largest risk right now is that prolonged reporting delays affect confidence from shippers, rail partners, employees, and equity holders. Recent 2026 revenue guidance of about US$3.6b to US$3.8b suggests management still sees demand for services, although execution on restatements and controls sits in the foreground.
The most relevant update tied to this delisting notice is the amended revolving credit agreement, which extends financial statement delivery deadlines to November 30, 2026. That extension gives Hub Group more room to complete its accounting review while keeping access to liquidity, something operational managers and customers will watch closely.
The ability to add accounting review and restatement costs back to EBITDA for covenant purposes also matters. It reduces the risk that restatement expenses constrain near term flexibility just as the business pursues contracts, digital investments, and intermodal capacity decisions that underpin longer term catalysts in e commerce and logistics outsourcing.
What Analysts Are Baking Into The Hub Group Story
Hub Group's narrative projects US$4.3b revenue and US$156.2m earnings by 2029. This assumes 4.5% yearly revenue growth and an earnings increase of about US$51.2m from US$105.0m today.
Uncover why Hub Group's fair value indicates a 34% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Hub Group, the sharpest contrast is on earnings power. The most optimistic analysts were modeling revenue of about US$4.5b and earnings of roughly US$171.3m by 2029, which is well above the consensus of US$4.3b and US$156.2m. Those views were set before this delisting process, so you should expect opinions to shift and explore several angles yourself.
Explore 2 other Hub Group fair value estimates, including one that suggests as much as 290475% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider going with your instincts.
- A great starting point for your Hub Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Hub Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hub Group's overall financial health at a glance.
Looking for more investment ideas beyond Hub Group?
If Hub Group's situation has sharpened your focus on risk, reporting quality, and balance sheet strength, it can be useful to compare it with other listed businesses that fit different profiles. The Simply Wall St Screener can help you quickly line up alternatives that better match your own comfort with volatility, yield, and financial resilience.
- Prefer stocks that prioritize stability and lower perceived risk over potential drama? Start with our screener focused on 31 resilient stocks with low risk scores to see which businesses currently fit that brief.
- Hunting for mispriced opportunities where quality and price seem out of sync? Filter for potential value ideas with the 30 high quality undervalued stocks and build a watchlist tailored to your return goals and risk limits.
- Rely on income as a key part of your portfolio? Scan for higher yielding payers with more robust profiles using the 7 dividend fortresses and compare their payout characteristics side by side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com